

Crafting an Effective Email

By Dennis Ford, CEO, LSN

A excellent piece of email tracking software and a great target list are both essentially worthless if the email itself is created hastily or without careful thought. It essentially boils down to two elements: a subject line and the body, but these must be carefully curated to ensure an effective mailing.

The subject is the first thing your recipients see, and it often dictates whether your message is opened and read. In fact, some studies report that 90 percent of the time the subject alone determines whether a recipient will read your message. The importance of how you phrase the subject cannot be overestimated.

In general, it is best to make the subject long enough to explain the purpose of the email, but also short enough for the reader to grasp the purpose quickly—as long as it is stated in a simple and straightforward manner. Also remember that different investors have different degrees of scientific sophistication. You cannot approach a private equity investor specialized in oncology the same angle as one would approach a philanthropically-minded family office. The subject and message must be thoughtfully tailored.

Email campaigns conducted to set up meetings for a road trip receive the highest open and response rates when they tell the potential investor exactly what they need. An email that quickly explains the purpose of your communication and cuts through the “noise” often results in a higher open rate. So the first thing to do is begin the subject with the purpose of your message: “Meeting Request.”

Next, give the prospect you are contacting a little context—tell him or her who you are. One option is to use the name of the firm: “Meeting Request—Manager of XYZ inc.” Another option is to use a manager’s name to make the email have more of a personal touch: “Meeting Request—John Smith, Manager of XYZ Inc.” You can adjust the style and format to your liking, but always be experimenting to find a subject that gets the highest response rate.

Note the use of dashes in the subject lines above. Spacing characters such as these can help potential investors quickly scan the email header and decide if they want to read it. A subject heading that is easy to scan means that your email will get considered. If your subject heading contains a lot of info without allowing for prospects to easily digest its meaning, they usually hit the delete button. So after stating the purpose of your email, use a spacing character for ease of reading.

The next step is to complete the heading with the final details of the marketing trip, which is the location and date. An option is to keep it broad: “Meeting Request—Manager of XYZ Inc., California Trip, July 7-12.” Or you could mention the cities: “Meeting Request—Manager of XYZ Inc., Trip to LA and SF Bay area, July 7–12.”

In some cases, you may want to keep the location purposely broad—even if you don’t have the flexibility to visit other cities. The reason is simple: the wider the area, the higher the response rate. The point is, you want to establish relationships with as many prospects as possible, so target as broad an area as is reasonably possible.

Email campaigns for marketing trips usually benefit from multiple attempts to reach prospects. It is important that subsequent attempts be reflected in the subject heading. In many cases, your original email message never reached its target, was deleted before it was reviewed, or simply got lost in cyberspace. With the large amount of email communication received by prospects, you can assume that about half of the recipients never saw your original email or didn’t recognize who it was from. So it is usually best practice to attempt a second email campaign to your target audience after removing those who responded to your original email.

In many cases, a second email attempt can have a higher response rate than the original email. The primary reason for this rests in the wording of the subject. At the very start of the subject line, include the words “2nd Attempt.” Follow this with the original email heading. For example, “2nd Attempt—Meeting Request—Manager of XYZ Inc., California Trip, July 7-12.” By making recipients aware that you have tried to reach them previously, they are more likely to review your email.

Finally, as you approach the date of your marketing trip, you may have meeting slots open and prospective investors you have not heard from. A different email technique can be applied here. The format of this type of email usually is shorter than your original one. The purpose of the truncated format is to express a sense of informality: on the eve of the trip, you are dashing off an invitation for a last-minute meeting. The informality of the email, along with the quickly approaching date, usually results in higher response rates from prospects who are moved to respond, since you are going to be in their area soon.

The subject is key to using this technique effectively. Instead of the more formal “Meeting Request,” it should take the form of a short note to a colleague asking for the meeting. For example, “Possible Meeting Next Week in LA?” Note that you want to be more specific with the location in this type of email. You can also use this type of email during the trip as well to fill in any remaining slots. Simply change “Next Week” to “This Week.” The informal style and short time frame usually results in shaking a few leads free.

After constructing a compelling subject that gets prospects’ attention, you need to write a message that holds their interest and results in action. The trick is to adequately explain your purpose for contacting them without making the message too long. For our purposes here we are going to deal with general email marketing campaigns and not touch on specific correspondence to prospects with whom you are already communicating.

To construct an email message that results in a dialogue with a prospect, it is best to divide the message into short, concise paragraphs. Ideally, you want the body of the email to display directly on the screen when your recipient opens it. At most, the recipient should have to scroll down once if he or she is using a compressed reading pane. Aim for two to four paragraphs, each comprising two to four sentences that explain who, what, when, where, and how. Remember that these points should be tailored differently depending on the investor category, as scientific literacy is variable among different investor categories.

The first paragraph is your introduction. It should explain why you are reaching out and offer your prospect a reason to continue reading. If you want to schedule a meeting, you may want to introduce your firm, and say what you do and why you are reaching out: “I hope this email finds you well. I am a partner at XYZ Inc. I will be traveling to London next week and I wanted to see if a meeting makes sense.” If you have never met before, sometimes it helps to say that you don’t believe the recipient has been introduced to your firm or has worked with your firm in the past.

The few short paragraphs following the introduction should explain your purpose in a bit more detail. The ultimate goal is to get your prospect to act, so the body of the email is simply a tool used to create communication. Many fundraisers fail in this respect. They think they need to put all their cards on the table and include a lot of details. Or they believe that prospective investors only want laboratory research or trial data. As a result, their communiqués are long and wordy, or read like an annual audit statement, which only encourages the prospect to click the “delete” button.

Remember, your prospects are human and thus the common metrics of marketing apply: You have only a few seconds, assuming that your prospects have decided to read your email, to capture their interest, convey your purpose, and get them to act. You need to be concise.

Overall, if you get to the point, state it clearly, and back it up with key data points, your email will have a better chance of cutting through the clutter and noise, grabbing the prospects’ attention, and getting them to act.

You may wonder how to craft a message to prospects you have spoken with in the past, but are not actively communicating with. If it has been six months or more since you last spoke, it is probably a good idea to refresh their memory on your firm’s product. Never assume that a prospect knows or remembers exactly what you do. Every day since your last meeting, your prospects have been speaking with countless other firms. When in doubt, always err on the side of re-explaining and re-introducing your firm and putting a potential investor in context with what you are doing today.

The tone of these emails should also be more conversational than an email blast. The point is to engage your contact in a more informal manner, as if to pick up on your last conversation. To use the road-show example, you could first begin by stating the topic of the email and why you are reaching out: “I am going to be back in San Francisco next week. When we last met nine months ago, you stated your firm was not yet ready for an offering like ours. I wanted to circle back to meet and give you an update on my firm.”

Before distributing an email to prospects, many marketers often feel compelled to include an attachment—sometimes many. There is the common misunderstanding that more is better. However, for an introductory email, it is usually best to limit the number of attachments—perhaps a one- or two-page firm overview, or the most recent commentary on your firm. Remember your goal and avoid the temptation to overwhelm them with data. Email campaigns are meant to wet a prospect’s appetite, not answer every possible question they might have.

By following these principles, it is far more likely that your campaign will have the desired results, and get you more meetings in a shorter timeframe. Stay focused, be confident, and be tenacious!
Developing a Global Target List of Prospective Investors

By Max Klietmann, VP of Marketing, LSN

Before moving any further, it is important to address a critical piece of the equation while looking at structuring an institutional-style fundraising campaign. The issue of referral vs. fit is one of the most misunderstood parts of the fundraising process, and countless companies fail to raise money, simply because their fundraising executives won’t believe that a cold email can be effective. We at LSN speak to a lot of entrepreneurs who refuse to accept that outbound marketing works, and it is our belief that this is due to an unwillingness to commit rather than genuine disbelief. Once you have made the commitment to go outbound, things become a little easier.

On to the issue of the cold e-mail. It has been proven time and time again that cold emails with diligent follow-up targeting the right group can be extremely effective. This is primarily because cold emails help you to reach the target person – with cold emails you can immediately reach exactly the right people in the investor organization, and that makes a significant difference. Of course this won’t work with just a random list of emails, you need a targeted list of specific entities. Beyond that, you need to reach the right people, not just the right firms.

Now that we’ve covered that, let’s look at the potential pool of investors and narrow it down to a target list. There are two types of investors: mandate-driven and opportunistic. Mandate driven investors are usually restricted to investing in opportunities that match a particular main sector, subsector, development phase, growth phase, indication preference, capital structure or need above or below a certain amount of investment. These restrictions are formed at the inception of the fund in order to provide serve as unique investment vehicle that matches the investment interests of the limited partner’s participating in the fund. By limiting the investment opportunities the limited partners can benefit from the unique risk and reward characteristics of the fund. For example an investor might specialize in investing in late stage oncology opportunities that requires equity financing. As a result opportunities outside of the mandate’s scope are immediately disqualified. Opportunistic investors on the other hand are defined by their lack of a mandate driven investment strategy. As a result they will not disqualify opportunities and therefore tend to have a broad range of investments.

As a fundraising executive you must understand each investor’s investment criteria, and make an effort to target those that are a match your company’s unique investment profile. Otherwise, you will find yourself wasting your time reaching out to investors that are not a fit. Note however, that your list should not be restricted to only fits for your current round, as you want to create a dialogue with investors that will be a fit further down the road. That way, when the next fundraising hurdle is reached, you already have a dialogue with the next source of capital.

Here’s a good benchmark to use: for every 100 investors that you reach out that that are un-validated without any clear indication of potential fit, a hit rate of 1-2 is the absolute upper limit. However, of a list of 100 investors with a pre-validated declared interest in an opportunity like yours, one should expect to schedule a conference call or meeting with 15–20 of those prospects. This is in stark contrast to the one or two prospects that you will yield from a un-targeted list. Assuming you are able to obtain a vetted target list and you’ve taken the time to evaluate your resources for follow-up, you can now get an idea of how many investors you will need on your email target list.

Generally, a fundraising executive starts be mining their internal database of potential investors—a list of current, past, and prospective investors—which they have built up over the years. This is a start, but your work is not done. To augment such a list, you can purchase one of the hundreds of commercially available databases, or take some time to research potential investors on your own.

Researching investors on your own is time consuming process, and painful process. Sophisticated investor database providers on the other hand can provide you with a list of potential investors that meet your investment profile with a couple clicks. They do this by employing staff that actively interviews investors regarding their investment preferences. Although these providers charge a fee they can save you significant time and effort.


Introduction: The LSN Email Marketing Issue

By Tom Crosby, Marketing Manager, LSN

The biggest issue that Life Science Nation deals with on a daily basis is a question that is constantly stifling progress in the industry: can a fundraising executive send a cold email to an investor that has a self-declared interest in their particular technology’s profile, and arrange a meeting with them – without an introduction? The answer to this question – Life Science Nation’s underlying thesis – is unequivocally, yes.

So, ask yourself this question that we hear so much: do you truly believe that you can get a list of self-declared investor mandates that are a fit for your company’s technology or services, put together a clear, cohesive, convincing email that effectively establishes your value, and then follow up on your responses with calls that begin a dialogue? Read on, and decide for yourself!

Because we had such an overwhelming response to last week’s email marketing article by LSN’s VP of Business Development, Alejandro Zamorano, we are reprinting that piece, along with two accompanying articles on building a target list and crafting an effective email.

These will also include a PDF on Email Marketing Strategy, which is the basis of a workshop that myself, Alejandro, and LSN’s VP of Marketing, Max Klietmann, put on at various conferences and universities, and for life science entrepreneurs involved in all areas of the life sciences.

Validating the New Investment Dynamic Between the US and Europe

By Max Klietmann, VP of Marketing, LSN

LSN tracks investor behavior within the life sciences on a global basis, and in recent times, an interesting trend has emerged in terms of capital dynamics between the US and the EU. Though early stage life science companies globally have fallen victim to the consolidation of venture capital, Europe has been particularly troubled. I wrote last month about an accelerating trend of investment dollars flowing into EU life science companies, but my theories were confirmed over the course of this week.

I attended a major west coast investor conference in San Francisco earlier this week, and I was astounded at the ratio of European companies represented among the firms seeking capital. Indeed, many of the conference circuit “veterans” agreed that this was unprecedented, especially for a west coast event. So without question, the capital environment in Europe has caused a mass migration of fund-raisers to turn towards US investors. Moreover, due to lower valuations among European companies driven by competition for financing, EU based firms are being invested in or snatched up at significantly lower multiples than comparable assets in the US and Canada.

I spoke with a few of the investors present (mostly VCs, but a few mid-level PE and virtual pharma folks),and many who historically were focused on US investments only. All of those that I spoke with agreed that European opportunities have become too compelling to ignore. In fact, I even met with a partner from a firm closing its first fund of approximately $100m in the coming weeks. The firm is exclusively focused on taking advantage of the significant opportunity that has arisen in the European marketplace.

So what’s the big deal? This trend has two significant benefits for the industry in my eyes. First and foremost, this is an opportunity for the European market to jump-start itself back into a relevant position in terms of commercialized innovation. This is a short-term benefit. In the longterm, there is a much more profound impact, which is that this temporary value gap between the US and EU is incentivizing a cross-over of investment. Many funds are dipping their toes into the European pool for the first time, and once the infrastructure and market familiarity is in place, the investment will continue. This means that investors have a larger pool of assets to choose from, increasing competition and market efficiency, and further globalizing one of the leading growth industries in the world. Welcome to the new economy, ladies and gentlemen.

Innovations at RESI: Diagnostics Gone Wild

By Lucy Parkinson, Research Analyst, LSN

When a potential investor approaches a diagnostics company, some of the first words out of their mouth are likely to be “How are you going to deal with the reimbursement problem?” At the Redefining Early Stage Investments Conference, we heard from diagnostic entrepreneurs who were rethinking the reimbursement model from the ground up.

A traditional business model for a diagnostics company involves persuading care providers that they ought to use the test, and then convincing HMOs that they ought to reimburse it. For a new product, this can be a tough sell; insurance plans often won’t specifically cover an innovative test, leaving the company to scratch for reimbursement on a case-by-case basis. They have to prove over and over that the test is more accurate or more cost-effective than the competition. Even companies providing an established product may find their revenues at the mercy of Centers for Medicare & Medicaid Services billing coding changes. Given these challenges, how can a diagnostics company build an attractive business plan that will win over investors?

Find the gaps in a divided marketplace. Most healthcare practitioners work in a highly specific area, yet many medical conditions manifest in ways that cut across these divisions. Sometimes, linked comorbidities are split between two different areas of medicine – for example, diabetes and eye problems. A diabetic patient might not have the time or inclination (or even the insurance coverage) to get their eyes checked out. An innovative business plan for an ophthalmic diagnostic might therefore include targeting clinics that deal with diabetes, and vice versa. We’ve heard from diabetes diagnostics looking to eye clinics for a new market; these related yet divided conditions show up all over the life science map, and diagnostics for many indications could take advantage of them.

Bypass the gatekeepers. We heard one diagnostics CEO say “I want to see people using our device in Walmart and CVS.”  If you have the right product – in this case, a device for a huge potential market that can deliver an automated result in minutes at a sub-$100 cost – you can seek direct routes to consumers. Similarly, the consumer market for wearable medical devices is exploding; this is, thus far, the only subsector of the medical device space where a company has successfully crowdsourced development of a product.

Rethink what your technology can do.  We heard from the developer of a diagnostic test so sensitive and robust that it can be administered entirely by mail, with the patient receiving a diagnostic kit at home and returning a swab straight to the diagnostic lab.  What is this company’s new business idea for this powerful new platform? Crowdsourced clinical trials. Rather than trial participants having to be regularly monitored by researchers at one location, they can be enrolled in the trial and then participate remotely, anywhere, anytime, bringing a huge increase in scale and a decrease in costs (including for participants).

Diagnostics might seem like a crowded field, but if your technology is powerful, a little innovative thinking about what it can do can completely change your approach to attaining revenue. You’ll stand out to investors if the reimbursement problem isn’t a problem to you at all.

An Introduction to Email Marketing for Fundraising Executives

By Alejandro Zamorano, VP of Business Development, LSN

One of the most valuable and cost-effective tools for a successful fundraising campaign in the life science space is email marketing. It allows you to introduce your firm to potential investors inexpensively, and on a scale unmatched by other forms of outbound marketing.

Today, services such as Constant Contact, iContact, and VerticalResponse offer Web-based email marketing platforms that greatly reduce the time and effort it takes to produce and distribute the many emails associated with your marketing campaign.

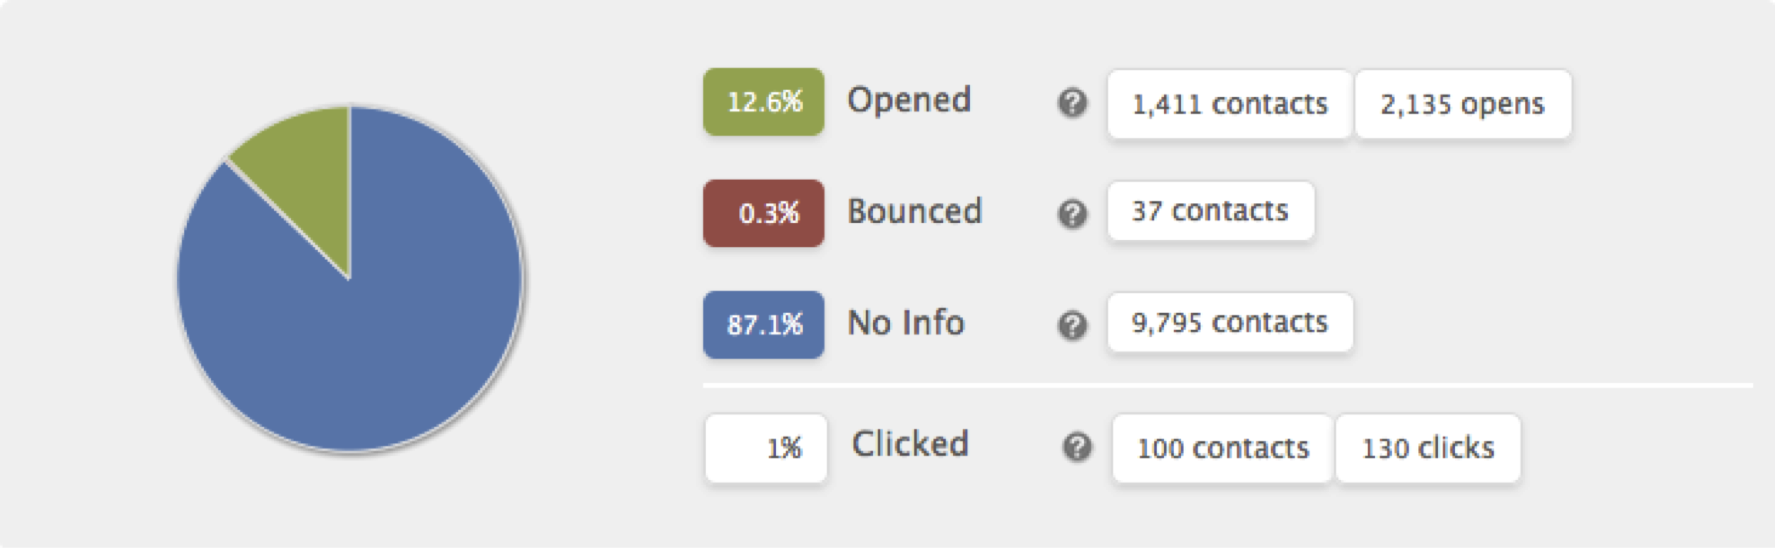
There are several other advantages to using outbound email marketing software. It’s cheap, simple to use and can be easily targeted. However, the single most significant advantage is trackability. After an email is sent, the software can monitor the campaign. Using tracking dashboards, a marketer can see the percentage of recipients who opened the email, clicked on the links, or requested to be removed from the list.

Going a step further, email marketing platforms can also list the email addresses of the recipients that carried out any of these actions. After an email is sent, the software can monitor the campaign. Using tracking dashboards, you can see the percentage of recipients who opened the email, clicked on the links, or requested to be removed from the list.

Example of an analytic dashboard

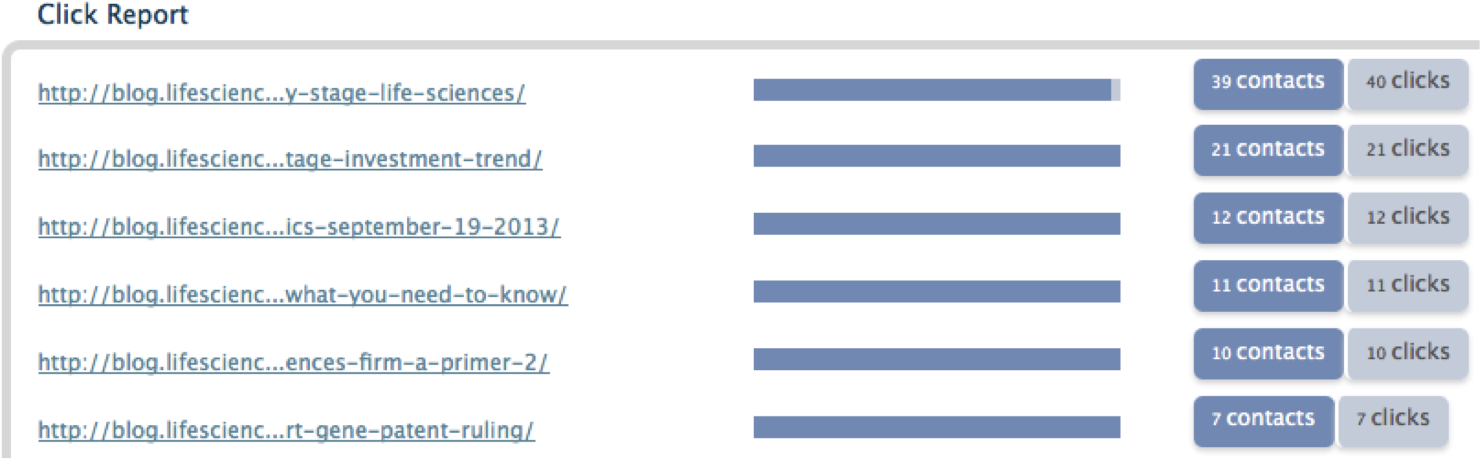
dash2This is the primary benefit of email marketing software; by knowing who clicked on your content and showed interest, you immediately have a list of good targets to call.

Example of a click report

clicksOnce your email is well-crafted and relevant to your audience, it’s time to send it out and begin following up with the most interested parties first. However, it’s not as easy as it may seem, and the phone canvassing metrics are not in favor of the canvasser.

What this means for the fundraising executive is that you have to be diligent. To start, it takes between 10-15 calls to get someone you have not met and want to start a dialogue with on the phone.

Once you finally get that someone on the phone and have started a dialogue, it can take 7-10 phone calls just to reconnect. After all that, if you manage to create a relationship and know someone fairly well, it can take 5-7 attempts to get a person on the phone. The most surprising statistic here is that most people give up after the first 3-4 attempts. The message here is to be persistent and tenacious, and whatever you do, just don’t give up. Your tenacity will impress investors, as it will speak to your commitment to advance the company to the next level.

The Quest for the Perfect Investor Fit: How Much Does Life Science Expertise Matter?

By Danielle Silva, Business Development, LSN

Here at LSN, I speak with many life science entrepreneurs about investor fit. Typically, life science executives believe that fit is a one-way street, meaning that they need to do all they can to prove they are a fit for a prospective investor. While it is certainly true that an integral part of the fundraising process is proving that your company is a fit for the firm’s investment thesis, this is not a one-sided negotiation. It is just as important for life science companies to make sure a potential investor is a fit for what the firm is looking to attain, and therefore, finding a potential investor needs to be both a strategic and tactical play.

What many life science CEOs struggle with is whether they should favor investors that have expertise in a particular area versus investors that are experienced in a certain phase of development. The answer, by and large, depends on what the life science company is looking to achieve in the long run, but there is of course no easy answer to this dilemma. Many entrepreneurs consider the problem a simple one – why would you want an investor that doesn’t understand your technology, or one who does not have expertise in your particular indication area?

While it is certainly important for investors to have a basic understanding of your disease area, this is only truly important if you are seeking scientific advisors for your firm. If this is the case, then finding a partner that has expertise in your disease area may be favorable to finding an investor that has knowledge of your stage of development. But what if, conversely, the executive is seeking a quick exit or a recapitalization? In this case, it may be more attractive to find an investor with a laser focus on your particular area. These investors already have a great knowledge of the space and thus probably already have a solid network that will be willing to acquire the company once the firm hits certain milestones.

Most life science executives I speak with, however, are not seeking scientific advisors, and instead are seeking investors with the business acumen to help take their product from discovery to distribution. These companies would benefit from a relationship with an investor that has knowledge of their particular phase of development, and who can thereby help to scale their business. It is also very beneficial for companies to be partnered with investors who have a deep knowledge of their phase of the clinical development cycle. These investors will have the expertise to help life science firms partner with appropriate firms in the R&D services space (such as CROs and other service providers).

Again, there is no clear solution to this problem. If your company is seeking an investor with a deep network in the space, then choosing an investor with sector expertise may be the answer. These investors, however, may not be able to help you scale your business to the point where your firm is an attractive investment or acquisition target for a larger investor within their network. Simply put, the answer is convoluted, no investor is the same, and everyone brings something different to the table. Life science executives should clearly define their goals in terms of growth and exit before deciding on an investor based on sector fit versus development phase fit.