Orphan R&D Shows Greater Returns over Conventional Drug Development

By Jack Fuller, Investor Analyst, LSN

A recent report that took a look at the current trends and future forecasts for drug development found that compared to conventional drug development, the research and development of drugs for orphan indications showed a greater overall return on investment. [1] Orphan drugs are classified as pharmaceutical products aimed at rare diseases or disorders, which in the US means a potential market of less than 200,000 patients. In 1983, the US government passed the financially incentivizing initiative, the ‘Orphan Drug Act of 1983’. Additional markets have emerged since 2000 with the adoption of similar acts in EU and Japan. Drug developers targeting orphan indications have the additional benefits of 7 years of market exclusivity from ‘same drug’ recombinant products (baring clinical superiority), a 50 % tax credit on R&D cost, special grants for phase I – III clinical trial, and user fees waived on revenues <$50 million. These incentives have allowed the development of therapeutics with a limited market financially feasible and as we will see, actually provide a stronger return on investment (ROI) than non-orphan drugs.

According to the new report, worldwide markets for orphan drugs are set to grow from $83 billion in 2012 to $127 billion in 2018 at a compound annual growth return (CAGR) of 7.4 % as compared to 3.7 % for the overall prescription drug market.  The financial incentives and expanding market make a strong case for investment in orphan indications; however, the true value to big pharma is derived from the smaller required patient size for approval. Phase III drug development costs can be cut in half or more with an average of 43 % reduced patient size. These results translate into big pharma achieving a 1.7 times greater ROI compared to non-orphan drugs.

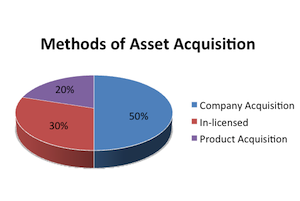
jack1So what is the end result for early stage life science investors? Companies such as Eli Lilly, Roche, and Biogen Idec are acquiring more orphan drug development companies. Of the top 10 orphan R&D products (by NPV) acquired externally, 50% have been the result of company acquisitions, 30% have been in-licensed, and 20% product acquisitions. This is good news for institutional investors looking to exit their investments and foundations looking to advance promising new therapeutics into later stage clinical trials.

Beyond the financial incentives for investors and life science companies, this push toward fostering development of previously underdeveloped diseases is benefiting patient groups who previously had scarce treatment options. Take the Cambridge, MA based Aegerion Pharmaceuticals, which is developing the orphan drug lomitapide for patients suffering from a rare form of familial hypercholesterolemia that causes cholesterol levels to soar, followed by almost certain death from heart disease by age 30. The success of the ‘Orphan Drug Act’ leads us to wonder if the poor market performance of other necessary indications will result in similar legislation and resulting financial opportunities.  Will we be seeing an ‘Antibacterial Development Initiative Act’ in the future? We’ll keep you posted.

[1] “EvaluatePharma Orphan Drug Report 2013.” EvaluatePharma, n.d. Web. 24 Apr. 2013.

Big Device Firms Focusing on Early Stage Opportunities

By Max Klietmann, VP of Research, LSN

It is no secret that venture capital firms are distancing themselves from early stage med-tech investments and are focusing more on later-stage opportunities. Interestingly, there is an emerging trend among the large, established players in the device space, whereby they are making strategic allocations to emerging device companies. What is especially interesting is that in certain indication areas, device companies are starting to see themselves as competitors to pharmaceutical products, meaning that we may be seeing the beginning of a new competitive landscape.

Medical devices were traditionally viewed as a distinct entity in the medical field, and not in direct competition with drug companies. However, as various major sectors in the space are converging, and the concepts of personalized medicine, companion diagnostics, and therapeutically-oriented devices are becoming mainstream, all this is changing. Take for example a major indication like cardiovascular disease – this is an area that has shown limited promise in terms of drug development over the past decade. However, devices might offer a solution for many patients that can be tailored on an individual basis. Consider the faster time to market and significantly lower risk surrounding devices, and you have a major new source of competition in the space.

Of course, the device firms recognize it, and have begun to outwit big pharma using their own strategy. Rather than develop devices in house or focus on later-stage products, many large device firms are investing in seed-stage companies or forging licensing deals early on in the R&D process to build a robust product portfolio. The implications are huge: Device companies may rapidly become the leading solution to many major indication areas, and pharma might be in even bigger trouble than anticipated. However, for the emerging biotechs and medtechs, this is excellent news – the emergence of a new industry-wide arms race means demand for product and a desire to invest capital, helping to accelerate the industry forward and bring cures to patients faster. Brace for impact!

CRO Marketing 101: The Value of Email Campaigns

By Tom Crosby, Marketing Manager, LSN

A recent study found that among most small-medium sized businesses, approximately 15% of marketing budgets are allocated towards email marketing (by far the largest single line item). By comparison, SEO and social media budgets came in at 8% a piece, and the confidence levels in the effectiveness of each were dramatically lower than they were for email marketing. This may sound surprising, considering the hype that surrounds social media outlets, but the data clearly shows that new and flashy doesn’t necessarily mean effective. CROs marketing their services should be mindful of how to effectively approach this tool.

In the current state of CRO service marketing inbound leads are few and far between, and small & emerging biotech opportunities are hard to map out. In this environment there is no easier and more efficient outbound attempt that a marketing team can make than email. This is reflected in the findings of the study. Personally, I see the positive effects of our newsletter campaign every day at LSN – most notably is that the few inbound connections that we are able to establish often come directly from the newsletter.

Email marketing is definitely a sales tool. However, there is a right way and a wrong way to go about email marketing. Many marketing professionals make the mistake of believing that the wider your audience is, the better your chances are of making that connection. We’ve all seen the cold emails coming into our Outlook inboxes every morning from marketers at nameless list providers. However, the reality is that a clean and narrow list of good targets is infinitely better than a large, clunky list of cold contacts.

The key to an effective campaign is targeted, interesting content that is being sent to interested readership on a regular basis. You want to create a dialogue with customers so they feel engaged, rather than throwing things against a wall and seeing what sticks. Direct, sales-driven “pseudo-articles” will only cheapen your brand, and will likely put your domain name on the spam list. However, if your prospects feel engaged, you can bring the business to you by solidifying your firm’s position in the marketplace as a leader with niche expertise. In other words, show how your CRO is differentiated from the competition by highlighting the unique advantages you offer. Having created a dialogue with prospects, it will then also be easier for you to adapt as conditions shift.

The aforementioned study showed that one of the main concerns with email marketing was losing subscribers when sending out weekly mailings. In my mind, this is a good sign, because it means that our list is getting stronger, and that we’re not reaching out to people who aren’t a fit for our product. This comes with the added benefit of staying in good favor with the community at large. If somebody doesn’t want to receive emails from us anymore, it’s made quick and easy to just say ‘no thanks.’ This is a simple courtesy that has far-reaching implications in terms of your company’s image – nobody wants to be seen as an annoyance. More importantly, this helps to keep your list fluid and up-to-date, allowing for more targeted campaigns and more effective dialogue.

The key take-away is that email marketing requires planning, strategy, and consistent execution and follow-up. Marketers need to maintain a conversation with their prospect audiences, and make their mailings interesting and easy to read. The goal is to connect your brand with insight and expertise that no one else can offer. When successfully executed, this can be an incredibly powerful tool that enhances the efficacy of the business development team.

LSN Database Feature: Trends Suggest Oncology, Antibody & Early Stage Licensing Demand Increasing

By Dr. Karin Bakker, Managing Director, PharmaPlus Consultancy, B.V.

LSN’s deals database is a powerful tool for investors and corporate strategic groups looking to follow key trends in the area of licensing and product/technology specific transactions. This week, LSN takes a deeper look at three popular parts of the space with compelling activity in 2011 and 2012: These are oncology-focused therapeutics, antibodies, and early-stage products. The tables below explain the latest shifts in the space.

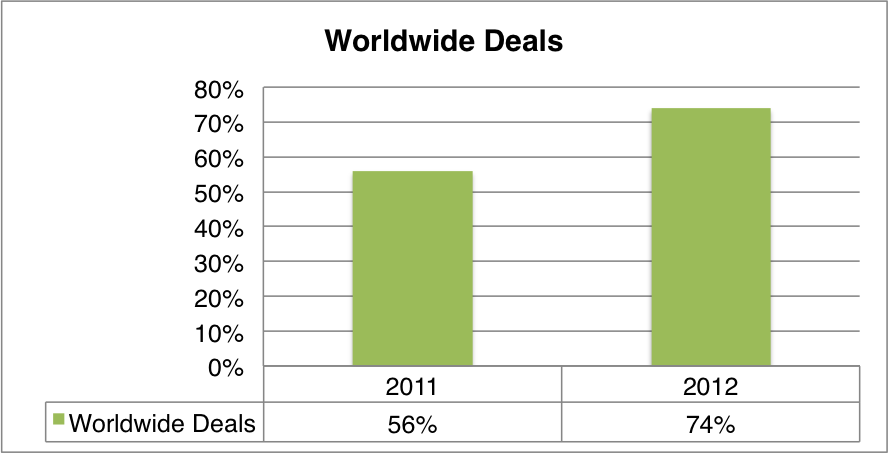
Worldwide deals increase dramatically: For oncology deals done between 2011 and 2012, there was a nearly 20% rise in deals that had worldwide licensing rights.

WorldWideDeals

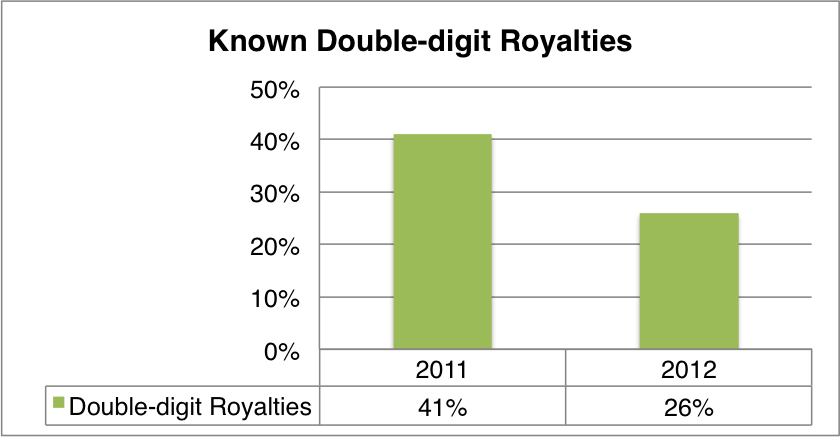
This means that the licensee has exclusive rights to research, develop, manufacture & commercialize, regardless of territory. Of these deals, at least 41% in 2011, and at least 26% in 2012, were reported to pay double-digit royalties to the licensor (10% or more.) It is important to note that this number tends to fluctuate positively, because royalty figures are not necessarily publicly disclosed in licensing deals.

DDRoyalties

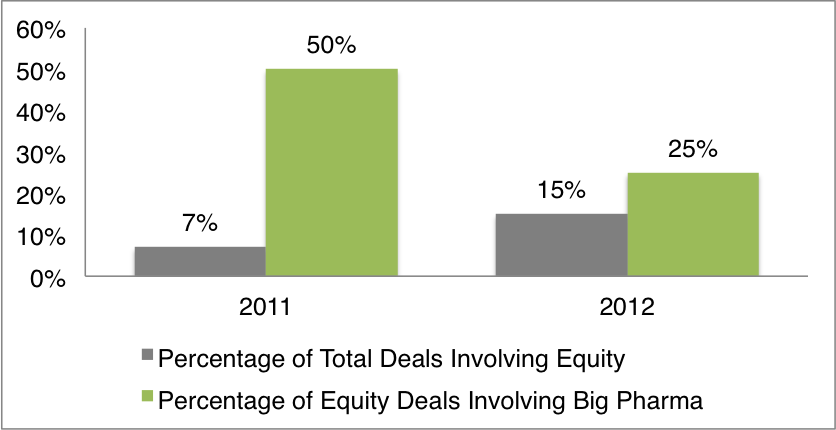
In at least 7% of the deals of 2011, and at least 15% of the deals in 2012, equity payments became publicly available in the database. In 50% of the deals with equity in 2011, the investor was a large pharmaceutical company. In 2012, this figure fell to 25%. This statistic highlights another trend – companies are licensing more to smaller private companies than to big pharma.

EquityDeals2

In terms of deals involving antibody-based therapeutics, there was a 2% rise (from 28% to 30%) between 2011 and 2012. It is important to note here that a majority of these are early stage deals – for example, deals with research alliances and companies in the preclinical stages.

AntibodyDeals

In summary, there is an increase in licensing activity surrounding oncology, antibody-based therapeutics, and among earlier stage products. This shift represents a positive trend for those emerging biotechs targeting this major indication area, who are considering early stage licensing as an alternative route to capital or exit.

Elucidating the Timeline to Capital

By Dennis Ford, CEO, LSN

LSN has written extensively on several facets of the capital-raising process, from the various new types of investors active in the space, to the technologies most actively being targeted by investors. However, we have not yet delved into the actual timeline required to raise money. This is the big question, as most emerging life sciences companies exist in a life-or-death situation. A misconceived notion of the required timeline to capital is the kiss of death for many; this article seeks to correctly define this critical period in the life of a company.

First things first: all of your collateral must be in order – this includes getting the business plan written along with the necessary investor presentation documents (powerpoint, executive summary, and website – yes, your website is an investor presentation tool!). This is a multifaceted process, which goes far beyond just explaining the science. Adroit entrepreneurs will know that as they write their plan, they are also creating a brand and a message that they are delivering to a marketplace of investors, and hopefully beyond. When writing the plan, keep in mind that the document you are creating is for distribution, and that it will be compared and contrasted with other companies that are going after the same capital as you are. If you take the time to present the data and create compelling facts & forecasts around your plan, then you have a leg up. Technology, market sizing and financial forecasting are all important elements, but don’t forget the most important one: your plan is your identity as a company! It can take anywhere from 6-8 weeks to develop and write a business plan, and then a considerable amount of ongoing time to hone and edit it as you move through the fundraising process.

The next step is compiling a global target list of investors that are likely candidates. You need to do your research and outline all of the likely candidate investors. This includes researching past investments in products like yours, groups targeting your specific disease area, and other relevant criteria that are major components of your company. This is why it is so important to have a cohesive understanding of who you are before seeking out investors. You will also want to research & target investors that have declared that they have a current or future mandate for investment in products that are like yours. This can be easy if you decide to buy an up-to-date database of investors, such as LSN’s. Alternatively, it can be incredibly time consuming if you decide to do this by vetting a list of likely investor fits through Internet research. Essentially, this is a process that can take a few clicks of your mouse with a good database, or over a month (or more) if researched manually. Here you must remember that accurate, current information on investors and investor contacts is paramount. Nothing creates thrashing like out-of-date data.

Then it is off to the outbound marketing campaign, and actually contacting investors – creating dialogue that turns into a relationship and, eventually, nets you an allocation. Contacting investors is a tedious, time consuming, and difficult process. It takes incredible tenacity to work your investor list and stay on the mission. Most of the time you spend will be doing referred outreach, cold calls, follow up, and more follow up. Most meetings involve multiple incantations and various follow-ups. This is because, realistically, it takes 2-6 weeks to regroup between follow-ups. What’s more, repeated meetings with various stakeholders can take months. All in all, the process of creating dialogue and developing a relationship takes a serious commitment of time and effort.

This is why it is important to know and understand the cycles of a fundraising campaign. Fundraising used to be more product-centric, but now a big part of the investment is vetting and building a relationship with the executive teams. Fundraising is a numbers game, and if you do get an investor on your radar screen, and the interest is really there, it is a still at most a one-in-four chance of getting through the due diligence, and an even smaller chance of being selected and funded after that. The fact is you really have to find, develop, and maintain an investor target list that includes hundreds of investors that are a fit to go after. If you understand this process, you will understand why it takes a dedicated commitment to raise capital, and therefore, why it takes so much time.

The last step, which is similarly time consuming and expensive, is to get you and your lawyer negotiating and closing the capital allocation down, and getting the cash into your account. Although there are no hard rules on this process, here are some of the things I’ve observed:

  • If you are fortunate enough to be in the right place at the right time with a compelling product or technology, you can raise your required capital in 3-6 months, but this represents a very small fraction of the players. Adding to this, angels, venture philanthropy, and patient investor groups can act swiftly, but they are a minority of investors. This is largely an issue of “passion versus risk” – meaning the venture philanthropy and patient groups move faster because of a sense of urgency in finding a cure.
  • From my firsthand accounts with fundraising clients, somewhere between 6 and 12 months is a reasonable timeline to raise capital, assuming investor climate is suitable and proper campaign execution is present.
  • The rest of the major categories of investors have firm “institutional” best practice investment processes. This means a stringent, time-consuming methodology and adhering to established protocols for the particular investment mandate. In other words, it takes time.
  • 2008 and 2011 drastically elongated fundraising timelines (for obvious reasons) to 9-18 months. This is beginning to soften now, but things can still be tough.
  • Investors are not going it alone anymore, so “herding” spells more time, as more players opt in.
  • Entrepreneurs can plan on spending around 1,000 hours (or about 9 months), which is at the top of the bell curve in my estimate. The 6-9 month point is when you will have a good idea of your funding potential in terms of investor’s feedback and interest. If it’s not working out, something needs to change.
  • A campaign is a living vehicle that needs to be honed and morphed as the investor reaction is calculated, which either enhances or delays your timeline.
  • Finding the right investor fit is critical. If you don’t achieve this, you’re looking at churn, churn and more churn – which can be expected today.


The State of Investment Banks in Early Stage Life Science Investing

By Max Klietmann, VP of Research, LSN

As LSN has been tracking the shift in the investor landscape over the past year or so, an interesting trend has emerged among some boutique investment banks in the space. Traditionally, investment banks in the life science arena were more focused on institutional transactions, and buy-side & sell-side activity. However, as family offices have begun to play a more significant role in the space, some tactically-minded I-banks have reoriented their businesses to focus on serving these constituents.

This is not a trend among the bulge bracket banks for several reasons: first, there is too much separation between the investment banking and private wealth business areas. This lack of communication makes it hard to consistently source direct investment opportunities for family office clients with specific interests. Secondly, family offices want industry specialists to serve as navigators in the space – they are not merely looking for an investment advisor. Finally, the family offices tend to prefer the personal touch gained by working with a smaller, more flexible boutique partner – it is simply the nature of this investor group to look for long-term relationship potential.

The boutique banks that are doing this effectively are maintaining a custom-tailored approach – they are taking a family office’s interest in a specific disease area, and enhancing their search with institutional quality deal sourcing, a high level of industry & sector expertise, and high quality due diligence processes. This yields superior results for family offices that typically have a genuine desire to make allocations, but lack the technical insight to navigate the space on their own.

So what does this mean for the space? Beyond investment banks having a new prospective client base in the life sciences space, there are some other very interesting considerations to make: Entrepreneurs targeting capital should consider boutique, industry-specific investment banks as a source of potential investors. Family offices looking to enter the space should evaluate whether one of these entities might be the right partner with which to approach direct investment in life sciences. The sands are shifting, and those that adapt to these trends first will have the upper hand.

Venture Philanthropy Providing Capital for Early Stage Science

By Dennis Ford, CEO, LSN

The single most important issue in the life sciences space today is that traditional sources of capital have slowed, creating a void, and fundraisers are left navigating using outdated maps & trying to play catch up. Anyone who has recently attempted to raise capital knows that this causes a lot of frustration and churn. Times have changed, and adjustments must be made. There is a distinct sentiment that the old funding models were broken to begin with (which I won’t belabor here), and the past investor segments aren’t going to return. The new landscape is substantially different, and new investor breeds are emerging across the space. Enter the Venture Philanthropist.

Venture philanthropists, or VPs, are extremely active investors and want to see results. However, this is not your typical exit-hunting venture firm; VPs mission is to speed up medical progress by eliminating the myriad of obstacles that researchers face, thereby hastening the delivery of breakthrough solutions to patients. Essentially, we’re talking about a mandate for medical progress and improved outcomes (hence philanthropy). VPs are impatient, and their goal is to accelerate the development of treatments and cures for the world’s most challenging diseases. There is a high degree of direct involvement as these investors are hands-on – they are more open, and therefore, flexible deal terms with multi-year allocation timelines can be negotiated. VPs know how to get things done, so expect milestones and carefully scrutinized metrics, along with action plans & organizational input.

VP firms provide funding for scientists and young life sciences companies in order to move along the development of therapies for certain diseases. Unlike traditional philanthropic organizations, venture philanthropists expect the companies and individuals they invest in to achieve certain milestones and focus on accountability. This isn’t just funding basic research; it’s driving products to patients as quickly and efficiently as possible.

These investors are becoming increasingly important, especially due to many scientists’ inability to translate discoveries into compelling market opportunities, and because of impending cuts in the NIH budget, which could cripple future therapy development. Venture philanthropy currently only represents less than 3% of the spending on medical R&D in the US, but this figure is expected to grow as the need for funding from scientists and early stage biotech firms continues.

There doesn’t seem to be a global source on exactly how many of these Venture Philanthropist entities exist, although preliminary research indicates around 150 and growing. Both North America and Europe have burgeoning grassroots groups that are starting to organize and recruit fellow family offices, using the ideology of expediting science for the good of the world.