Hot Life Science Investor Mandate 2: Private Investment Firm Looking for Shipping Medical Devices

A private investment group based in Canada is looking to make growth stage investments in medical device companies. The firm does not manage a committed fund of capital. The firm’s partners generally make up 20-25% of the capital and raises additional capital on a deal-by-deal basis from a small group of high net worth investors. The firm invests in companies that are based in North America. The firm is actively looking for new investment opportunities.

In the Life Sciences the firm is currently seeking to invest in medical devices with market approval. The firm is opportunistic in terms of the class and indications. Historically, the firm invested in an image guided medical laser technology although they are open to all recently approved devices.

ECP seeks to be an active investor and will require a board seat/observer rights. The firm only invests in commercial stage companies but the firm does not have revenue requirements.


Hot Life Science Investor Mandate 3: CVC Arm of Healthcare Provider Looking for Devices and Diagnostics

The corporate venture capital arm of a large health care system in the United States is looking to invest in on early-stage companies across the healthcare sector. The firm typically allocates $500K to $1.5M initially and up to $3M over the life of an investment. The firm looks for companies that are based in the United States and is actively seeking new investment opportunities.

In the Life Sciences the firm is currently seeking to invest in medical devices and diagnostics devices. The firm looks for all classes of devices and is opportunistic in terms of indications. The firm will consider devices as early as in development stage and all the way to commercialization stage. Current investments include companies operating in wound care, neurovascular and surgical tools though they are open to all types of medical devices. The firm is most interest in devices that have a strong potential to lower healthcare cost, thus benefiting the firm’s parents company. The firm looks to invest in privately held companies with a strong and experienced management team.

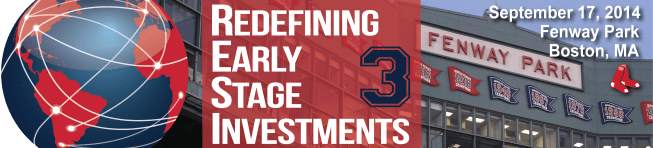
Save the Date for the Next RESI Conference: September 17, 2014

By Maximilian Klietmann, VP of Marketing, LSN

Max Smile 2

Join LSN for the next Redefining Early Stage Investments Conference at the iconic Fenway Park—home of the Boston Red Sox.

This conference will be the best one yet, attracting more scientist-entrepreneurs, investors, and strategic partners from around the world.

RESI was created to connect emerging biotech and medtech companies with active, early stage life science investors. The conference provides a venue for companies and investors to find each other, have a dialogue, begin a relationship, and determine if there is a compelling fit for both parties.

The RESI panels will feature 10 categories of life science investors who will provide insight into how they choose companies to invest in. If you are interested in attending, sponsoring, exhibiting, or receiving more information about RESI, click here to contact Tom Crosby, Conference Manager, or call 617.600.0668.

Homepage

Follow us: #RESI3

Rules of Engagement: Keys to Effective Partnering Conferences

By Alejandro Zamorano, VP of Business Development, LSN

Alejandro 10*10

On the global life sciences conference circuit, events are usually divided into two categories: partnering and non-partnering conferences. Partnering conferences are different from the classic “fixed agenda plus networking reception” format in that they provide an online portal that allows attendees to identify one another in advance and schedule one-on-one meetings.

When it comes to raising funds for your emerging life science company, partnering conferences constitute the industry standard, offering a distinct advantage to savvy fundraising executives. However, because the quality of these conferences varies, it is important to understand how to successfully navigate the system and effectively connect with the right people.

The first key element is to determine how much work the conference provider has put into the partnering system. This can make or break your efficacy as a fundraising executive. All too often, the profiles in the partnering system are not populated, and the search ontology isn’t tailored to the attendee base, rendering the partnering system largely ineffective.

A matching platform is only as good as the data it contains, and there are only a handful of conferences that allow companies to import full profiles into their systems, and only one or two sponsors that manually curate the profiles to ensure completeness in advance of the event. These are the cream of the crop when it comes to partnering conferences, and they make it easy to identify fits quickly and efficiently.

However, because most partnering conferences are not hands-on when it comes to their databases, there is a significant amount of noise. This forces busy executives to manually research each prospect to see if a company is a fit. Most executives fail to do their homework simply because it is too labor intensive, resulting in an untargeted or shotgun approach when they send out meeting requests. This causes not only inefficiency but also leads to frustration on the part of investors who find themselves inundated.

A big pharma licensing executive recently remarked to BioWorld:“Many of the nation’s young biotechs ignore even the most fundamental rules of engagement by failing to do basic homework. More often than not, when we’re contacted by a potential partner, [the request] has nothing to do with our strategy.”

As the industry advances, more conference providers will increasingly recognize the importance of a well-curated partnering system. But what should a biotech entrepreneur do in the meantime? Fundamentally, it’s a question of doing some careful research and identifying a “short list” of key people you need to meet based on a clearly identifiable fit. This can be done well in advance of an event, and your partnering request messages can be carefully tailored to show you are a potential fit.

Rather than trying to send out 100-plus requests over the 48 hours before an event, a methodical approach during the 10 to 15 days prior allows you to carefully identify who is a fit. This will improve your ratio of accepted meeting requests and will provide you with a much more productive partnering experience.

Remember, investors and your potential partners are there to meet companies like you, so don’t be afraid to reach out, but do keep it targeted. One well-crafted message to a likely fit beats ten vague messages to unlikely fits any day.
What Should the Next Generation of Incubators Look Like?

By Jack Fuller, Business Development, LSN

Jack 2

If you reside in one of the many growing or established life science clusters around the U.S., you have probably encountered the growing plethora of incubators or accelerators that are emerging to support nascent and semi-virtual companies. Often, these incubators are funded by a combination of state grants, corporate partnerships, and revenue generated from renting space to emerging companies.

When giving a tour, incubators are quick to point out the pristine lab space and glass-walled conference rooms they provide to start-ups. However, they often have little knowledge about what it takes to fundraise in the life sciences: a tactical approach that requires expertise in branding, marketing, and cloud infrastructure.

Dennis Ford, CEO of LSN, often speaks about the need for emerging entrepreneurs and experienced fundraising executives alike to upgrade their approach to outbound marketing. Phone and email canvassing techniques require the same diligence and determination that even the most complex scientific experiments demand. If an emerging scientist-entrepreneur can perform 100 experiments and get one positive result, there may be hope to teach them how to make 100 phone calls to a targeted audience based on fit and get one great meeting.

LSN has spoken with hundreds of emerging life science companies, and we have realized that not everyone can take this step. If that is the case, incubators that integrate a team of marketers and business development experts should be in the future. Incubators could create an infrastructure of experts to market the companies, providing everything from branding and messaging support to website design and cloud infrastructure—even seasoned business development to aid in scheduling and running investor meetings. This is an enormous void in the current incubator environment. Early stage companies are slowly realizing that good science alone won’t get them funded. Providing that next level of tactical infrastructure will help streamline a company’s fundraising efforts and help them see the straightest line to cash.

In return, the incubator would take a transaction fee if capital was raised—a fee that could be re-invested into the incubator to provide additional staff, expertise, and infrastructure to further promote an evergreen approach to incubating companies to bring them to the next step.

Would this model work? Time will tell, but as we say here at LSN: you can walk a mile, but at the last three feet, you still need to reach across a desk and shake someone’s hand.

Hot Life Science Investor Mandate 1: Private Wealth Fund Looking for Clinical Stage Assets/Technologies

A private investment firm located in the Northeastern United Sates is looking to make investments in the life sciences space, and does so on a case by case basis without a traditional fund structure. Since the members are investing their own capital, the investment size and capital structure are highly flexible and will depend on the financial needs of the company. However the minimum amount the fund is willing to invest is $2 million, and can go upwards of $40 million. The firm invests in private or public companies and prefers to be the lead investor, but is open to syndicate as well. The firm is willing to invest in opportunities from all across the Globe. The firm is looking to conduct as many investments as possible over the course of the next 12 months, and is open to qualified deal flow.

The firm is very opportunistic and will consider a broad range of life science opportunities. The firm will consider Biotech, Medical Technology, R&D services, however the firm prefers not to invest in Healthcare IT, Dermatology, or Wound Care. The firm focuses on companies with clinical assets with some efficacy data, through those who have products on the market are also considered. The firm has a strong interest in technologies that significantly improve the standard of care.

The firm evaluates the company’s management team on a case by case basis. The firm is open to working with both experienced teams, as well as new entrepreneurs, and only requires that the team be competent. The firm does not require a board seat.

Hot Life Science Investor Mandate 2: Family Office Seeking Devices and Diagnostics

A family office with offices in the Northeast and Midwestern United Sates invests its principal capital into high growth companies in both the private and public sectors. The firm’s investment size is highly variable and dependent on the financial needs of the company. The firm often leads investment rounds and also has the ability to leverage its additional network of High-net worth families and like-mined co investors to syndicate for larger deals as well as follow on investments.  The firm looks to invest in companies throughout the United States and has no set number of investments in plans to make, however they are actively reviewing new opportunities.

Within healthcare, the firm is most interested in companies developing Devices and Diagnostics. The firm is looking for companies devices that solve a significant medical problem with strong IP supporting it. The firm is willing to invest in companies from the prototype stage to those that already have their product on the market and is generally agnostic in terms of indication. Historically the firm has invested in companies working with cardiac devices and also has held special interest in the pediatrics space. The firm is generally not as interested in consumer facing devices. The firm is also willing to consider investments in the Therapeutics space though this area is less of a focus.

The firm is looking for companies that have experienced management teams and a strong board behind them. The firm is willing to invest in both privately and public held companies with special interested in making PIPE investments. The firm looks to take a board seat into companies on a case by case basis.