Longevity Global Shapes the Longevity Track at RESI Boston

By Justin Taylor, Vice President of Communications, Longevity Global (Special Guest Contributor)

Innovation and Investment to Beat Aging and Age-Related Disease

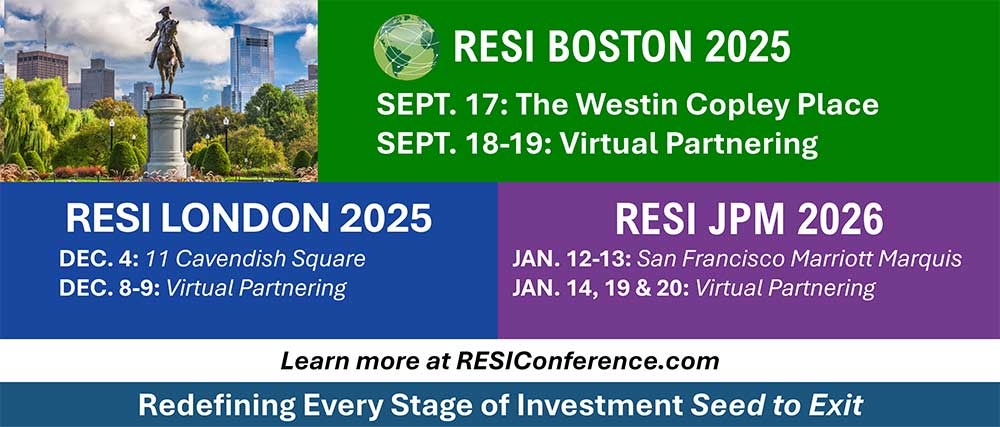
Longevity Global is coming to RESI Boston on Wednesday, September 17, with a full day of programming dedicated to innovation and investment in the longevity space. This curated track will highlight cutting-edge science, startup founders, and investors who are accelerating solutions for aging and age-related diseases.

The day begins with coffee, networking, and opening remarks, followed by a keynote from Eric Morgen, Co-founder of BioAge, setting the stage for thought-provoking discussions on advancing longevity research. Morning sessions feature presentations from leaders such as Raghav Seghal (Yale), Christin Glorioso, MD, PhD (CEO, NeuroAge and Longevity Global), and Spring Behrouz (Vincere Bio), who will share perspectives on mitochondrial aging and fundraising in the field.

A Pharma Chat with Suguna Rachakonda (VP, Insilico) and Jon McClain (Executive Director, Lilly) will provide an industry lens on where big pharma sees opportunities in longevity.

The afternoon program kicks off with a keynote from Sharon Rosenzweig-Lipson (CSO, Life Biosciences), followed by Umbereen S. Nehal, MD, MPH, MBA (Founder, HER Heard, MIT) on the importance of women’s health interventions in extending lifespan and healthspan. Additional sessions include Ethan Berg (Founder, Winthrop Estate) on the case for investing in longevity, alongside an Investor Panel featuring Sally Wang (Managing Partner, XPanse Ventures), Ruta Laukien (VP, US Capital; Managing Partner, GrayBella Capital), and Fiona Miller (Managing Partner, quadraScope).

The Innovation Panel, moderated by Tom Zuber (Managing Partner, Zuber Lawler), will showcase voices across legal, biotech, and clinical perspectives, with speakers Frank Gerratana (Partner, Calyx Law), Shane Hegarty (CSO, AXONIS), and Jay Luthar, MD (Founder, Lutanen Health).

The program culminates with the Longevity Global Pitch Competition (Series A), where startups will showcase their technologies to a panel of seasoned investors. Winners will be announced by Daniel Dacey and The Engine, which will also award the winning company a full year of lab space—an invaluable resource for advancing early-stage science.

The day closes with the RESI Cocktail Hour, featuring wine and hors d’oeuvres, offering attendees the chance to network and celebrate innovation.

By bringing Longevity Global to RESI, this track provides an unparalleled platform for entrepreneurs and investors focused on combating aging and age-related disease. From scientific insights to investment strategies, the agenda is designed to drive meaningful dialogue and new connections in this rapidly advancing field.

Join us at RESI Boston to connect with the innovators and investors defining the future of longevity. Learn more

Recent Life Sciences Deal Trends

By Andrew Merken, Shareholder, Polsinelli (Special Guest Contributor)

Andrew-Merken

Keep the faith.   

When it comes to life sciences industry transactions, the business cycle is alive and well. After a spectacular second half of 2020 and all of 2021 – which took most everyone by surprise given COVID – the past three years have seen a marked decrease in the volume – though not the dollar value – of activity. The number of venture capital financings, Merger & Acquisition (M&A) transactions, licensing deals and Initial Public Offerings (IPOs) dropped – in some cases fairly significantly – in 2022 through 2024. 

Underlying the 2022-2024 slowdown was inflation, a rise in interest rates and a slackening economy. From a borrowing perspective, higher interest rates raised the cost of capital, requiring companies to lean less on debt and more on equity in financing their operations and transactions. At the same time, however, those same higher interest rates caused investors to cycle away from the stock market and to park more capital in bonds. As the IPO markets cooled, so did public market liquidity opportunities for venture capital investors, resulting in less new capital available for new investments. And as the economy slowed, venture capital investors were forced to reserve more capital to keep existing portfolio companies afloat, exacerbating the lack of funding available for new investments. By one estimate, US venture capital funding declined from $47 billion in 2021 to $34 billion in 2022 (a 22% decrease), to $25 billion in 2023 (an additional 27% drop), before increasing slightly to $27 billion in 2024. Drug discovery and therapeutics companies tended to be the most active recipients of VC funding. 

Interestingly, though, while the overall amount of capital invested decreased as did the number of deals, the average deal size increased. Investors pivoted toward later stage deals – Series B, C and D rounds – which tend to be less risky but which require more capital and, arguably, a number of well-known life sciences VCs transitioned to being growth equity investors in their most recent funds. Early-stage (Series Seed and Series A rounds) investing decreased. At all stages, premoney valuations fell, with down rounds becoming more frequent and, often, dramatic.  

M&A activity showed similar trends; in the US life sciences industry, M&A deals dropped in value from $180 billion in 2021 to $70 billion in 2022 (a 61% decrease) before increasing to $113 billion in 2023 and then decreasing again to $111 billion in 2024. The number of transactions also decreased, by 31% from 2021 to 2022 before increasing by a modest 5% in 2023 and then decreasing again by 23% in 2024. As with VC investing, though, the median average deal size increased during this same timeframe – from $110 million in 2021 to $160 million in 2022, before decreasing to $100 million in 2023 and increasing again to $199 million in 2024 – as did the trend of transactions favoring later stage, less risky assets (late stage development/early commercialization) over early stage ones, in part because strategic acquirers looked to acquisitions to supplement declining revenue growth. The big winners in M&A were companies focusing on oncology, immunology and neurology. Licensing deals also decreased, from 215 in 2021 to 182 in 2022 (a 15% decrease) and then again to 134 in 2023 (an additional 26% decrease).  

Following a strong 2021 in which there were 99 life sciences IPOs that raised a total of $15.6 billion, 2022 saw only 17 life sciences IPOs ($2.4 billion) and only 13 IPOs in 2023 ($2.7 billion). The flight to debt and the slowing economy were to blame, with the trickle-down effect of less IPO liquidity impacting the venture capital markets and lower stock prices of already public companies making stock acquisitions more difficult. In addition, much like in venture capital and M&A, IPOs have been trending toward less risky later stage, clinical asset companies.   

Then, as the calendar turned to 2025, there was a renewed sense of optimism.  Those who were in San Francisco in January 2025 for the JPMorgan Healthcare Conference noticed that attendance was back to pre-COVID levels, partnering meetings for companies raising capital with potential investors were for the first time in a number of years being scheduled with ease, and overall there was a palpable sense of excitement about the coming year. 

Toward the end of January, however, policy changes in Washington served to change the environment.   The uncertainty around the regulatory framework – FDA staffing and priorities, the FTC’s approach to mergers, NIH funding, HHS’ approach to vaccines and the SEC’s oversight of the capital markets, along with the discussion around and imposition of tariffs – put a fairly quick stop to the optimism.  Interest rates and inflation that had decreased in the second half of 2024 – resulting in lower costs of borrowing and a renewed trend toward equity – and which were expected to jump start the economy became less favorable. Term sheets that were expected to be signed were shelved, deals for which the transaction documents were being negotiated were put on hold, and overall a renewed sense of anxiety washed over the ecosystem. 

According to JPMorgan, VC financings and IPOs continued their downward trend in the first half of 2025: 

  • VC deals in therapeutics and drug discovery totaled $11.2 billion, as compared to $14.2 billion in the first half of 2024. 
  • There were only 5 biopharma IPOs over $15 million in the first half of 2025, versus 10 in the same period of 2024. 

However, M&A and licensing deals turned the corner in the first half of 2025, according to JPMorgan: 

  • M&A deals totaled $42.5 billion, which is a significant increased from the $15.9 billion in the first half of 2024. 
  • Licensing deals totaled app. $120 billion announced deal value in the first half of 2025, versus $76.3 billion for the first half of 2024.  

JPMorgan and others attribute these increases to several factors, primary among them Big Pharma’s need to replace revenue lost to the impending patent cliff –  with the patents on a significant number of blockbuster drugs expiring between 2025 and 2033 – and the continued shift to acquiring less-risky later stage assets versus funding more risky earlier stage assets. 

In addition to the uptick in M&A and Licensing deals for later stage companies, there is also good news for early-stage companies.  Over the summer, we have started to see a slight thaw – not the supercharged environment that we saw in early January, but a slight uptick in activity.  Companies who have not given up and who have been persistent in sourcing investments are starting to find new opportunities. Some NIH funding has also been restored – at least temporarily.  The uncertainty seems to be lessening, and the industry is learning to work around the new realities.  The ordinary course business cycle upturn that started in early 2025 seems to have derailed, but the ultimate uptick will not be precluded – simply delayed. It’s very possible that January 2026 will bring what January 2025 signaled.  While that optimism doesn’t pay the bills or get the deal done, it will hopefully be of some comfort to those who had hoped 2025 would be their breakthrough year.   

Andrew Merken is a Shareholder in Polsinelli’s Venture Capital and Emerging Growth practice where he focuses on corporate and transactional matters for life sciences clients covering the entire business life cycle, from start-up (formation and organizational matters) to seed and venture stage funding to growth stage (later stage funding, corporate collaborations and buy-side M&A) and ultimately exit (sell-side M&A or IPO).  

About Polsinelli 

Polsinelli is an Am Law 100 firm with more than 1,200 attorneys in over 25 offices nationwide. Recognized as one of the top firms for excellent client service and client relationships, Polsinelli is committed to meeting our clients’ expectations of what a law firm should be. Our attorneys provide value through practical legal counsel infused with business insight, offering comprehensive corporate, transactional, litigation and regulatory services with a focus on health care, real estate, finance, technology, private equity and life sciences. Polsinelli PC, Polsinelli LLP in California, Polsinelli PC (Inc) in Florida. 

Get on Pharma’s Radar: What Big Companies Look for in Early-Stage Innovation

Live at RESI Boston – September 17 | Westin Copley Place 

By Momo Yamamoto, Senior Investor Research Analyst, LSN

For many early-stage life science companies, partnering with a major pharmaceutical firm can be a transformative milestone. Beyond capital, Big Pharma brings global reach, regulatory know-how, and commercialization muscle, opening doors that would otherwise be out of reach. But breaking through the noise and earning that opportunity requires more than a strong pitch deck.

The “Partnering with Big Pharma” panel at RESI Boston will offer a rare, inside look at how business development and licensing leaders identify and evaluate emerging innovation, including therapeutics and enabling technologies.

What Does Big Pharma Look For?

This 50-minute session will dive into the key criteria pharma decision-makers use to vet early-stage companies. From the strength of the data package and differentiation in a crowded landscape to alignment with therapeutic priorities and unmet need, the panel will shed light on how early is too early and when is just right to engage.

Attendees will also gain insight into how large pharma teams structure search & evaluation processes, how red flags are interpreted, and what signals strong partnership potential.

 Moderated by Jeremy Sohn, Managing Partner at P74 Ventures, this conversation brings together key voices shaping pharma’s external innovation strategy:

Jeremy-Sohn Hyelim-Cho Nikhil-Mutyal
Jeremy SohnManaging Partner
P74 Ventures
(Moderator)
Hyelim ChoSenior Director, BD and Alliance Management
RayzeBio
(a Bristol Myers Squibb company)
Nikhil MutyalHead of Search and Evaluation, Respiratory and Immunology
AstraZeneca
Armin-Rump Jenny-Wang
Armin RumpDirector of Global Business Development
Otsuka Pharmaceutical Co., Ltd.
Jenny WangDirector, Search & Evaluation, Oncology
AbbVie

These leaders are actively scouting for high-impact innovations and will share how their organizations assess risk, potential, and fit in a rapidly evolving landscape. You will hear how shifting trends are reshaping pharma’s partnering approach, and what startups can do to stand out in a competitive environment.

Whether you are aiming for a strategic investment, licensing deal, or co-development partnership, this panel offers direct access to the minds shaping pharma’s innovation agenda. Founders, BD professionals, and investors alike will walk away with actionable insights into what it takes to get – and stay on – Big Pharma’s radar.

Register today and save with early bird rates.

Partnering Launches August 11 for RESI Boston September 

By Max Braht, Director of Business Development, LSN

Max-Braht-Headshot

Partnering at RESI Boston 2025 is set to launch next Monday, August 11. The RESI series have consistently been the largest early-stage life science partnering events, in terms of investor attendance, and with 400+ investors/ strategic licensing partners expected to participate in September, RESI Boston September will be a turnkey event for entrepreneurs who are looking to raise capital.

With both in person and virtual registration options, as well as a handful of remaining spots open in our Innovator’s Pitch Challenge, companies can take advantage of Life Science Nation (LSN)’s unique partnering system to set meetings directly with global investors/ in-licensors who are a fit for their product’s sector, indication, stage of development and geographic region.

Companies looking to register can do so before this Friday, August 8th to take advantage of our Early Bird Pricing discounts. LSN will also be hosting a free partnering tutorial webinar on August 18th to help companies maximize the number of secured meetings.

Beyond the Pitch: Why Life Science Startups Fail and How BD Assist Closes the Execution Gap

A deeper dive into what really moves the needle for early-stage fundraising

By Dennis Ford, Founder & CEO, Life Science Nation (LSN)

DF-News-09142022A few weeks ago, we introduced BD Assist, Life Science Nation’s full-service global partnering campaign designed to take the burden of business development off the founder’s desk and get real investor meetings on the calendar. The response from experienced founders was immediate.

Here is the truth: BD Assist is not for first-time founders who are still learning the ropes. It is built for the second, third, or fourth time scientist-entrepreneur. The one who already knows how hard this game is, who is tired of chasing down investor meetings between running a company, and who understands the real value of having a professional team help run the global campaign infrastructure.

If you missed the original rollout, you can view the BD Assist overview deck here for a clear breakdown of how the system works.

Why Execution Still Kills Good Science
Even with scientific momentum and breakthrough data, more than 90 percent of early-stage life science companies still fail. Not because the science is not good, but because most founders never make it through the long middle: the grind of targeting, messaging, outreach, and follow-up. They do not reach enough of the right capital investors and licensing partners. They do not have a CRM that tracks investor touchpoints. They do not have time to build and run a campaign while also managing a preclinical program or preparing for the next financing round.

BD Assist exists to fill that gap. To build the campaign, manage the outreach, and hand the founder a pipeline of matched meetings so they can do what they do best. Show up, pitch hard, and close deals.

What BD Assist Actually Does
At its core, BD Assist is a global investor and partner matching engine, backed by a professional services team that handles the heavy lifting. It is not just coaching or strategy. It is a full campaign execution.

  • Matching 600 to 800 capital investors and licensing partners based on stage, product, and deal profile
  • Direct introductions, meeting scheduling, and post-meeting follow-up across LSN’s global network and the RESI conference series
  • CRM setup and outreach execution so you can track progress, engagement, and pipeline movement
  • Messaging and content coaching to sharpen your story across decks, summaries, and calls
  • Strategic support from executive coaches who have helped close hundreds of investor and licensing deals

Need to See the System
Watch our Investor Database demo to understand how we match based on fit, not just category.
Take our free campaign readiness assessment to see if you are ready to scale your outreach.
Or sign up for the next RESI Conference to meet matched investors and pitch in the Innovator’s Pitch Challenge.

This BD Assist Model Works
Our partnership with the Brisbane Economic Development Agency proved it. Over the course of two years, 90% of companies raised more than $ 110 million. Why? Because we did not just teach them how to pitch. We provided them with a comprehensive global campaign system and assisted in its implementation. Click here to read the case study article.

Who is BD Assist Really For
BD Assist is for scientist-entrepreneurs who are already in motion. Founders who have been through a raise know how time-consuming investor engagement really is and are ready to hand off the execution to a trusted team.

Your job is to show up to meetings and move the needle. Our job is to fill the calendar with the right meetings, every week, for the next 9 to 18 months.

Want to Get Started
Contact resi@lifesciencenation.com to learn more.

Because in life sciences, science gets you noticed. Execution gets you funded.

Why Impactful Storytelling Isn’t Optional in Life Sciences

By Tinotenda Chanakira, CEO of Revnuu | Life Sciences Commercialization Strategist (Special Guest Contributor)

In the life sciences, great science isn’t enough to make it out of the lab. Across biotech, medtech, and diagnostics, many teams are advancing transformative healthcare innovations—but still struggle to secure the funding, partnerships, or clinical traction they need. The culprit is rarely bad research, data or scientific innovation. More often, it’s an unclear or underdeveloped narrative.

Too often, life sciences companies present their breakthroughs in ways that prioritize technical complexity over clarity and resonance —visually and orally. Their decks are filled with mechanism-of-action diagrams, regulatory timelines, and patent claims—but little about real-world human impact. Meanwhile, capital markets are tightening, partner deal cycles are lengthening, and competition for attention has never been fiercer. In this environment, storytelling isn’t a marketing tactic. It’s a core business competency.

The challenge is that life sciences companies must communicate across very different audiences. Technical stakeholders—Key Opinion Leaders (KOLs), regulators, clinical advisors—require precision and depth. Commercial stakeholders—investors, distributors, potential acquirers—want proof of market potential and differentiation. And at the center of it all, patients and physicians seek hope, clarity, and relevance.

When a company’s narrative fractures across these touchpoints, the result is confusion, inconsistency, and distrust. Alignment stalls. Partnerships hesitate. Capital walks. To avoid this, founders and leadership teams must develop a coherent, multi-layered story that is not only technically sound but also emotionally and strategically compelling.

Over time, I’ve found that the most successful companies tend to master four core narratives. While the terms themselves have been shaped by broader industry dialogue—especially the work of Life Science Nation—this is how I’ve seen them come to life across real-world negotiations and commercialization journeys.

1. The Founder’s Core Motivation

Investors fund conviction as much as they fund IP. A founder’s story becomes the emotional and philosophical backbone of the venture. In life sciences, this often stems from a moment of deep personal or clinical proximity to the problem—a diagnostic delay, a therapeutic failure, or the loss of someone close.

The most resonant founder narratives don’t just showcase academic credentials. They surface the “why” behind the work. One oncology startup I advised pivoted its entire strategy when the founder lost a parent to late-stage metastasis. That story reshaped how partners viewed the company—not just as a platform, but as a mission-driven force.

2. From Lab to Life-Changing Impact

In science-based ventures, it’s easy to over-index on technical novelty. But partners don’t invest in “clever.” They invest in outcomes. The core question your technology story must answer is: What becomes possible now that wasn’t before?

In life sciences, this means anchoring your innovation in patient outcomes—not just mechanisms. “Our CRISPR-edited CAR-T therapy reduces relapse rates by 47% in refractory ALL” communicates far more than “novel lipid nanoparticle delivery system.” Precision and proof points win here. In fact, 83% of business development executives cite “clear patient impact language” as the single most missing element in pitch materials (LSN Survey, 2024).

3. When Treatment Becomes Transformation
Human outcomes are more compelling than preclinical data—always. This story focuses on transformation: how lives change because of what your product enables. Whether it’s earlier diagnosis, improved quality of life, or reduced healthcare burden, this is where the emotional gravity sits.

But emotion alone isn’t enough. The most effective patient stories also tie into economic logic. For example: “Maria’s Stage I diagnosis saved $218,000 in late-stage care costs.” That intersection of human and system-level impact is what resonates with both payers and partners.

4. From Validation to Velocity
Finally, partners want to see signals of commercial discipline. This doesn’t mean focusing solely on how much funding you’ve raised. Instead, highlight validation milestones that reduce perceived risk—real-world pilots, clinical endpoints, regulatory wins.

“CE Mark secured with 94% sensitivity in a real-world cohort” tells a far more powerful story than “Closed $20M Series B.” The emphasis should always be on de-risking through traction—not just hype.

These four stories don’t live in a pitch deck—they live across your organization. They must be practiced, refined, and embedded from leadership through to field teams. When aligned, they help companies accelerate partnership timelines, deepen investor conviction, and drive internal cohesion across functions.

If you’re unsure whether your narratives are aligned, ask yourself:

  • Can our team clearly articulate the founder’s “why” without defaulting to credentials?
  • Do our technology explanations compel clinicians to lean in?
  • Do our patient stories move decision-makers beyond the data?
  • Do our commercial milestones give partners confidence in our go-to-market plan?

If the answer to any of these is “no,” then it’s time to sharpen the story. Because in this industry, the science must speak—but the story must win.

About the Author
Tinotenda Chanakira is the founder and CEO of Revnuu, a commercialization strategy firm serving deep tech and life sciences ventures globally. With over 50 clients supported across Europe, North America, and the EMEA regions, Revnuu helps founders turn scientific breakthroughs into scalable, market-ready impact. The firm operates between Barcelona and Basel, guiding companies through the real-world complexities of product, capital, and growth.
London Life Sciences Partnering & Venture Investment Week 

By Greg Mannix, VP, EMEA Business Development, LSN

The first week of December marks the largest life science partnering and venture week in the UK. If you’re raising pre-seed, seed, round A or round B, or are in phase 2 or earlier development, Life Science Nation’s (LSN) RESI London, One Nucleus’ Gensis, and ELRIG/SLAS events offer far better partnering, investment, learning, and procurement opportunities compared to the health care week in late November (concurrent with the Jefferies investment banking event), for a fraction of the cost. That week tends to focus on recent IPOs and companies that are close to IPO, along with phase 3 or more advanced companies looking for partnerships. If you’re not at that stage, save your critical conference and travel budgets for an event series that’s right for you.

RESI London and Gensis are combining to offer a multi-day investment, partnering and thought leadership event for venture stage companies seeking funding and strategic alliances:

December 2nd

  • Free course on fundraising, including networking, offered by LSN
  • Free ELRIG / SLAS drug-discovery focused networking event
  • Genesis welcome reception for Genesis and RESI registrants

December 3rd

  • Genesis “Maximising Returns from Life Science Innovation” KOL & partnering event
  • Genesis evening reception

December 4th

  • RESI London fundraising & partnering event, featuring 200 investors & in-licensors
  • RESI London evening reception

During the entire week you are also welcome to attend the Genesis Fringe events for free including networking breakfasts, lunches and other events with topics similar to Building a World Class Life Science Ecosystem, Accessing US Investors and Exits, IP Strategies in Advanced Therapy Dealmaking, Top Talent Trends for Life Sciences in 2025 and Pay Transparency, R&D to Commercialization in Rare Diseases, and more.

Join us in the rich life science ecosystem in London during the first week of December. To learn more, contact us at RESI@lifesciencenation.com

Register for RESI London