

LSN Investor Database Feature: What are investors seeking in 2014?

By Lucy Parkinson, Research Manager, LSN

lucy 10*10

LSN tracks about 5,000 life science investors around the globe. In the last issue, I took a dive into the LSN Investor Database, and looked at who was planning to back early-stage innovation in 2014. In this article, we’ll look at where in the life science sector these investors plan to put their funds. This data is based on the last 250 investor mandates LSN’s research team has collected from 1-on-1 interviews with investors. Some major trends we’ve uncovered include:

  • VC comprises under 25% of investors active in the life sciences, based on LSN’s most recent investor mandates.
  • Most investors have multiple sector interests.
  • Devices are hot for many investors, but especially very early stage investors such as angels.
  • Corporate venture and private equity represent some of the most opportunistic investor groups.
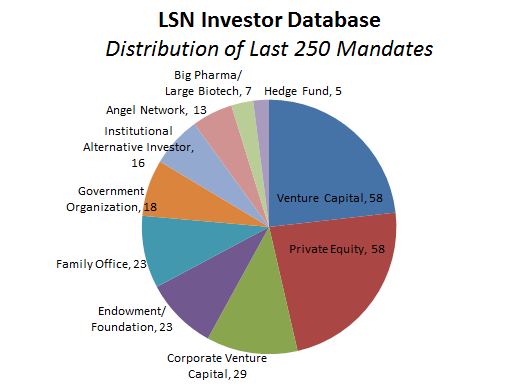
image002

A fascinating piece of information that is presented by the mandate data is that VC comprises less than 25% of the active investors in the space based on forward-looking mandates. LSN has identified about 1,500 VCs in life sciences broadly, and about 500 that claim to be active. However, based on the last 250 mandates collected by LSN research, they are comprising a shrinking percentage of total capital available to companies. This shows that the number of non-traditional investor categories, such as family offices that are going direct, is increasing on a relative basis.

Many of the active life science investors we’ve spoken to have multiple sector interests; only about 30% restrict their life science mandate to only one sector (such as therapeutics, diagnostics, or medical devices).  Foundations are a major exception; almost half of the foundations we’ve spoken to are solely interested in supporting therapeutic and diagnostic companies.  Pharma firms and large biotech search and evaluation groups tend to be focused in this area; however corporate VC funds are more opportunistic, and many of these funds are willing to look at other sectors where they see the potential to complement their parent company’s portfolios.

What about the device space?  LSN meets many emerging device companies that claim there is a dearth of capital available to them. Perhaps surprisingly, about a third of angel networks in the life science space are focused only on medical devices.  While there are many angel groups out there who back therapeutic companies, the shorter exit-horizons associated with devices, makes them compelling opportunities for very early stage investors.

Another possible reason is that the former entrepreneurs who join angel networks usually invest in areas where they can apply their expertise; those who made their fortunes in the technology industry may have more confidence in their ability to assess a device technology than a molecular technology. Family offices may similarly be guided by the family’s expertise and existing business network, and these investors are notably more focused than most; about a quarter of those we’ve spoken to are only interested in medical devices, whilst another quarter are interested only in drug development.

At the other end of the scale, who are the life science sector’s most generalist investors?  Private equity funds are largely interested in making established businesses more profitable across a variety of industries, and if they know the life science sector they tend to seek their opportunities widely.  Notably, very few PEs invest only in therapeutic companies, although several have a focus on medical devices; these tend to be funds that have a general interest in high-tech manufacturing.

So what’s going to be the hot sector in 2014 – medical devices or drug development?  It’s almost neck and neck, but overall we’ve spoken to slightly more medical device investors than therapeutic investors.  Stay tuned as we revisit the data as the year progresses!

The Myth of JP Morgan

By Alejandro Zamorano, VP of Business Development, LSN

Alejandro 10*10Early January in the life sciences tends to revolve around preparing for what is believed by many to be the most important investor week in the biotech industry – JP Morgan. 2,500-3,000 biotech and medtech professionals representing a significant part of the industry will come together in San Francisco next week. The conference, and all of the smaller satellite events surrounding it, will seek to deliver compelling content, and provide executives a central location to facilitate face-to-face conversations with much needed strategic partners and investors.

However, though JP Morgan provides some great opportunity, the industry has created (and perpetuated) a myth around the event. It is often falsely considered the single defining moment for networking and partnering in the industry. When talking to life science executives during the past weeks, many have told me that they are waiting for JP Morgan to launch their fundraising campaigns. They act as though JP Morgan is a fundraiser’s paradise, where they will serendipitously find their perfect investor match. The reality is that very few life science executives will find their investor match at JP Morgan. Those who have success there will have most likely have been in dialogue with their prospective investors for some time.

The most successful fundraising executives understand that JP Morgan is not a place to initiate conversation; it is a way of organizing a week of meetings as a part of an ongoing fundraising campaign. Waiting until JP Morgan (or any other conference, for that matter) to launch a fundraising campaign is the wrong way to approach the process. More importantly, if you have waited to start your fundraising campaign based on an arbitrary date (rather than when you are ready to go outbound) you have already failed. Fundraising is not a baton race (raising money at each interval), it’s a marathon (it never stops). The most successful biotech executives are constantly in fundraising mode. They build relationships with investors over a long period of time and reach out to prospects well in advance of needing capital. This allows them to build long-term relationships with qualified investors making the fundraising process more efficient and effective.

The most successful approach to managing your fundraising campaign around the conference calendar is to start as early as possible, and then manage the subsequent relationships face-to-face at events. Of course, you’ll always meet some new people, and conferences are valuable for keeping a pulse on the industry. However, it is key to keep in mind that fundraising is a numbers game, and the more people you are able to get in front of, the better. Remember, JP Morgan is not the beginning or the end of your fundraising journey. It is another stop along the road.

Announcement: LSN Company Database Updates

By Alejandro Zamorano, VP of Business Development, LSN

LSN’s ongoing commitment to provide the highest quality offering to our clients, we are excited to launch a new software release for the LSN Company Database and the Licensing Deals Database! Here is a brief overview of the new functionalities that have been implemented based on feedback we’ve gotten from our users:

  • Save Search + Bookmarks – Allows you to receive targeted alerts about your bookmarked companies, technologies, and products.
  • Enhanced interface for Licensing Deals – Allows for more intuitive navigation of search results and includes new filters such as the ability to search deals across specific territories
  • Enhanced interface for bookmarking – provides you with the ability to search within your book marked companies, and products
  • Direct links to each bookmark section on the toolbar – Allows for quicker navigation

LSN continues to carefully evaluate all of our clients’ comments and suggestions to make our products more powerful. Stay tuned for more new features to help you and your organization operate smarter and more efficiently!

The Market Strata for Early Stage Innovation

By Dennis Ford, CEO, LSN

Understanding where emerging life science companies fit into the competitive landscape and how to position them in front of an investor audience are two of LSN’s guiding mantras. It is critical to take the time to understand where your firm fits and to develop a cogent, lucid and compelling brand and message. This helps investors understand the bet they are making. Understanding the “technology impact” of your product or service and its relationship with the general marketplace is crucial.

Personally, I parse technology according to my own rule of three.  Is the product disruptive, breakthrough or iterative?  Answering the question allows me to map the technology against the universe of investors that are a good fit.  After all, context is really what you are trying to achieve when meeting with an investor. Being able to quickly get the investor to understand where your technology sits in the overall scheme of things counts a lot. I spend lots of my time with life science entrepreneurs and I will share some of my insights regarding the few categories.

Life science companies with “disruptive” technologies have the potential to change the world in a big way. The word “disruptive” is often overused in the life science industry, so let’s take a moment to discuss exactly what it means: These are technologies that literally disrupt the industry – This is the rare, once in a blue moon, technology that literally changes the game (However, in the “golden age” of life science, these disruptive technologies may be on the rise.) This could be a cure for diabetes, an AIDS vaccine, or something similarly groundbreaking on a huge scale. These disruptive technologies are the holy grail that all investors are looking for and when identified are quickly shepherded to the A-list VCs. That is all well and good except that it’s 20 or so high flying VCs and 30-40 chosen companies (anyone’s guess). So what about the rest of the marketplace?

The “breakthrough” technology companies have significant technology solutions for major medical needs. These can be viewed as “leapfrog technologies” that change treatment paradigms or improve outcomes in a big way. These are not necessarily “disruptive,” but they are undoubtedly valuable innovations that impact patients in a very major way. Let’s just say for arguments sake that these breakthroughs companies number in the hundreds, and they are tasked with marketing themselves to the right investors, because the shrinking VC population isn’t necessarily accessible or the best route for them. The breakthrough companies need to be educated on the new categories of  investors are filling the void left by the VCs.

The “iterative” technologies are next generation innovations. This can be distilled down to a better, faster, cheaper, or otherwise improved next generation of existing technologies. These are easy to understand, because the previous version exists, so investors can easily grasp the value. However, these companies number in the thousands, and they have a challenge getting on any investor radar screens.  These companies are tasked with having to really dig deep in terms of finding the right investor fit and translating that into a cogent, targeted marketing campaign.

I started Life Science Nation (LSN) to track the other 10 categories of life science investor that are filling the VC void. LSN researchers create profiles through one-on-one personal interviews regarding their particular interest in life science investment. These investors are family offices (single and multi), venture philanthropy/patient groups, virtual pharma, mid-level PE, angel syndicates, hedge funds, foundations, endowments, pensions and corporate venture. At the end of the day LSN’s job is do the research, find investors, interview them, write up their profiles and investment mandates and get that data into the marketplace. Understanding how your technology fits into the marketplace allows you to understand which investors you should be targeting.

Corporate Venture & Foundations Investing Early

By Lucy Parkinson, Research Analyst, LSN

When the LSN research team gathers mandates from investors, we’re taking the pulse of the future; we ask about what the investor is seeking going forward, what areas of their portfolio they want to build up, and which new breakthrough technologies they want to be a part of.  This has allowed LSN to identify a few trends that 2014 may hold for life science investment.  Today, I took a deep dive into what our mandate data says about who is seeking to invest at which stage in a product’s development. Here’s what I discovered:

Venture capital is going later.  Traditionally, venture capital firms were seen as the go-to for a new life science company in need of capital to fuel their earliest trials.  But of the active venture capital firms LSN has spoken to, 15% say they refuse to consider investing in preclinical projects at all. The bulk of VCs (about 50%) now declare that they’re agnostic about developmental phase, and will invest at any point through to Phase III.  About 25% consider investments in therapeutic companies that have a product on the market and are generating revenues – a realm of investment that was traditionally reserved for private equity funds.  Among medtech investors, very early-stage companies may have an even tougher time with VCs; a third of VCs that invest in medtech don’t consider opportunities in companies that have no in-human data.

So which new investor categories are most aggressively targeting early-stage therapeutics?  Here are a few of the trends that could forecast the coming year’s activity: Foundations are backing commercial work.  Of the foundations we’ve spoken to who are interested in making research grants to for-profit companies in 2014 as well as to academics and non-profit institutions, almost 50% will only consider funding preclinical and Phase I work.  These groups often tell us that this strategy is designed to make their research dollars go further, and to de-risk projects that they see as important.  If a foundation thinks your research work is important, they may be able to offer you a $100,000 grant to conduct some risky preclinical research; if that trial produces a solid result, another investor with deeper pockets is likely to step in, make an investment and advance the product to market – and getting new treatments to patients is what a foundation cares most about.

Another notable player at this stage is corporate venture capital; unlike VCs, almost all corporate VCs are looking to invest in preclinical work in 2014. Also, they have deep pockets and a declared need to uncover innovative science, so these may be some of the leading players when it comes to capital allocations in the coming year.

So what factor do corporate VCs and research foundations have in common that enables them to put money into breakthrough preclinical work?  Judging from the conversations we’ve had with them, the common factor is scientific expertise.  These groups are notably more specific than VCs; many foundations are pursuing a cure for a specific disease, and corporate VCs usually have specific strategic interests dictated by their parent companies.  About two thirds of venture capital firms are opportunistic generalists when it comes to choosing which indications to pursue; under half of corporate VCs are opportunistic in this regard.  As foundations and corporate VCs have specific focus areas, they’ll also have deep understanding of these areas and that means they’ll have more faith in their ability to pick outstanding preclinical projects to support.  If your company is at an early stage, reaching out to these fellow experts in your field could be much more beneficial to your search for funding than approaching a venture capital firm.

Investors Building Life Science Companies from the Ground Up

By Alejandro Zamorano, VP of Business Development, LSN

LSN tracks ten categories of life science investors around the globe. Recently, we have begun to follow and emerging trend of established investors creating and launching their own companies. These investors are cognizant of the critical importance of good management when it comes to asset commercialization. The school of thought behind this innovate approach is that emerging technologies stand more of a chance when strong leadership and organization is put around an asset from the get-go. So, why is this occurring and how exactly is this being executed?

From the firms LSN has spoken with, this approach is essentially an fusing two key elements – Access to capital and access to a network of experts, both of which help to make leaner, faster, and more efficient companies. It all starts with sourcing novel science from a translational researcher, and building a business structure around it.

Since the investor is starting the company, it is possible to structure the “perfect” company from the ground up. This goes beyond investor fit – it’s a custom tailored company to fill a portfolio need. This can create significant advantages early on in the company’s life cycle, as fundraising seed capital isn’t a problem. By avoiding this part of the process, the company can focus on moving the science forward. Moreover, the company can structure the management strategically from the get-go, by having a business-savvy CEO in place who has the sales experience required to turn innovative science into a company.

Add to this that the investor can shepherd multiple assets through the pipeline by outsourcing work to CROs, and you have a great lean model for building a portfolio of companies. This model is gaining traction, so stay tuned as LSN tracks this evolving trend.

Adapting Your Start-up to the Investor Mindset

By Max Klietmann, VP of Marketing, LSN

LSN spends a lot of time speaking with both investors and early stage life science executives. One of the constant themes in our experience is the disconnect between what investors want to see when evaluating companies, and the way in which early stage executives present themselves. Though there is a broad spectrum of elements that influence an investor’s decision to allocate, there is only a handful of factors that can make or break an investor dialogue early on. If you, as an early stage entrepreneur, understand how to address these points up front, you are likely to see significantly higher success in your fundraising efforts:

  • Competent Management – A racecar is only as good as its driver. Similarly, a technology without excellent management is dead in the water. Savvy investors invest in people, and the ones that have been around the block are able to see if a CEO has what it takes. Take a look at yourself and your team – the scientific acumen is undoubtedly there, but take a hard look at the business acumen and sales ability of your management team – do they have what it takes? If not, find someone who can drive, while you engineer.
  • Technology – This is a big one, whether your technology is a disruptive innovation or an iterative improvement to existing technology. Learn to explain your product succinctly, and be able to tell an investor exactly how it fills a demonstrated market need. Show investors the nature of your technology – showcase it, and explain why the competition doesn’t stand a chance in your slice of the marketplace.
  • Focused Approach – It’s easy to get caught up in the potential applications of your technology, but this can be a pitfall. Many CEO’s are eager to show all of the diseases that could be addressable by their small molecule, but it translates to a lack of focus from an investor standpoint. Don’t get me wrong – having backup plans in your back pocket is always a good thing, but pick one product, one indication, and show your investor prospect that you have the laser focus to get it done.
  • The right target population – We’ve spoken about knowing your marketplace at length. Do your research, and make sure you are targeting the right population from your investor audience’s standpoint. Are you a solution for a broad indication with lots of prospective customers, or are you better suited for the shortened regulatory path around a niche orphan disease? Choose one and be able to explain why your product is the hottest thing to hit this area.
  • A clear path to market – Have a roadmap for your regulatory path and key partners to help you move forward. Nothing is ever set in stone, and things will constantly change, but it means a great deal to an investor that you aren’t only thinking of stepping from A to B, but C, D & E are also being considered in your present decision making.

At the end of the day, you need to sell each prospective investor on these points. There will always be further criteria to discuss and deal terms to navigate, but in order to have the ability to choose investors, you need to have a relationship with several. Meet these key points, and you should be well on your way to raising a round on terms that fit your company’s needs.