The Myth of the NDA

By Danielle Silva, VP of Business Development, LSN

Most fledgling entrepreneurs are (understandably) protective about their technologies. In turn, it is common for them to ask investors to sign an NDA before engaging in a dialogue. An NDA (Non-Disclosure Agreement) is essentially a confidentiality agreement that two parties engage in to ensure that the information shared amongst the two parties is not made publicly available. Companies do this in an attempt to ensure that any technologies or processes that are integral to the firm’s operations are not disclosed to any other party. However, an NDA can discourage conversation, especially if incorporated into the introductory dialogue. So what is the right path to follow when considering whether or not to put an NDA in place?

Firstly, always consult your lawyer. This article isn’t intended to be legal advice, rather it is intended to help you think strategically when engaging investors. Many life science entrepreneurs may be tempted to make investors sign NDAs before even speaking with them. However, these investors typically look at hundreds or even thousands of deals every single year. An NDA could discourage a conversation. Especially when targeting investors that get a lot of solicitations, and NDA will probably constitute a burden. If you can’t express to an investor in the initial dialogue why your company has value, you’re probably not ready to start talking to investors. That doesn’t mean that there is information worth protecting, but you needn’t disclose “the secret sauce” in the introductory email.

Secondly, keep in mind that investors aren’t purely looking at your technology, they are also looking at you. Ideas are more like mushroom spores than lightning strikes – They emerge simultaneously from various sources, and the right leadership (not just the right idea) makes the difference between success and failure. Management is just as important as product from an investor standpoint. Many entrepreneurs we speak with are surprised by how many companies are in their competitive landscape. There is probably someone else doing something very similar to you, so rather than hiding your idea, show investors how you, as an executive, can do it better, faster, and more effectively.

Finally, remember that the purpose of your initial dialogue is supposed to facilitate a relationship. If things look promising and meetings surface, that’s the right time to discuss putting together an NDA with your lawyer. Avoid making it appear that it’s complicated to do business with you from the get-go. Again, always consult your lawyer before engaging in investor dialogue, but remember to keep a tactical mindset. Fundraising is a numbers game and the easier you make it to start a dialogue, the more meetings you’ll net.

CRO Trends in 2014

By Alejandro Zamorano, VP of Business Development, LSN

As we round out the final quarter of 2013, LSN looks towards the new year and what it holds for CROs (Contract Research Organizations) within the life sciences. LSN maintains regular dialogue with a broad spectrum of CROs – from top-tier full service organizations, to small niche-specialized research companies. Based on our market insight, here are the top behavior trends among CROs for 2013 as we continue to see strong growth in this critically important sector of our industry:

The Death of the Passive Business Development

The CRO space has become increasingly crowded over the past year, and with mounting pressure on biotech companies to achieve capital efficiency, the market is becoming increasingly competitive. CROs that rely on inbound leads and recurring revenues from longstanding partners will face serious challenges in an environment where only the hunters survive. Those organizations that iterate their business development tactics will be the winners, and outbound sales will rule the day. As the industry matures, we will begin to see more sophisticated marketing campaigns as sales organizations adapt to the new market dynamic.

Developing Therapeutics

Tempted by the success of their clients, and a wealth of in-house expertise, a handful of CROs are starting to leverage their proprietary technology platforms in the hopes of developing their own novel assets. This will cause a shift within the industry as the lines start to blur between a CRO and a biotech company. The biggest obstacle to success in 2014 will be the ability to raise the necessary funds needed to shepherd the asset through clinical development, especially when the focus of management will be split. However, considering the fact that CROs already have revenues from the service side of the business, they may require less outside capital for asset developments, making for an enticing investment opportunity.

Consolidation

Private equity groups are becoming a major play in the CRO space, providing much-needed capital for growth. Many of the PE players in the space are purchasing and consolidating mid-level players to create economies of scale and synergies of business. Buyouts will certainly provide some liquidity events, but more importantly, consolidation will be an important counterbalance to the growing number of CROs. Moreover, as private equity groups create more efficient players via M&A activity, the pressure is on for smaller players to stay competitive.

Investor Partnerships

Today, the growing trend among service providers is to team up with well-known investors that have a continuing demand for certain basic services such as clinical development and contract manufacturing. By building these alliances and by outlining a discounted rate, CROs can create a consistent supply of customers by providing investors with a price break. This is a win-win in both situations, where investors get increased control and cost efficiency for their portfolios, while CROs gain a powerful dealflow engine.

Investment Activity

LSN recently covered the trend of CROs making direct investments into life science companies. This trend is also likely to accelerate as CROs take advantage of the opportunity presented by early stage companies strapped for cash in the form of services-for-equity arrangements, or outright corporate venture activity.

2014 will be an interesting year for CROs, as the increasing competitive nature of the industry will leave only the most innovate companies to enjoy market growth. Be sure to stay tuned as LSN continues to track the key market dynamics affecting service providers going forward.

Understanding Technology Risk & Investor Mindset


By Lucy Parkinson, Research Analyst, LSN

LSN recently released an article detailing the competitive landscape for therapeutic indications, and how your asset fits in. We all know that not all subsectors are equal from an investor standpoint; if you’ve been out there looking for investors, you’ve probably discovered whether your particular niche is currently ‘hot’ or ‘cold’. You’ve also probably noticed that investor appetite shifts, and that cold sectors can quickly turn red hot, and vice-versa.

So what drives these trends in life science investment, and what does it mean for your company?
 
Given the rapid pace of progress in life sciences, many investors find it hard to keep on top of every new innovation, particularly if their firm doesn’t specialize in life sciences. Though things change, opinions are often influenced by past experience. “We’re only human,” one investor told me last week. “We lost money on our diabetes investments, so we’d think twice about investing in that field again.” Many factors influence an investor’s risk assessments. One is the size of the potential market; it’s ironic that some investors have come to see larger markets such as diabetes and heart disease as unacceptably risky. A large market means established competition, expensive clinical trials and high overhead costs required to attain market share.

Even if an investor feels like they can rely on the science behind your product, they may have a prior opinion of your technology.  Some subsectors came to be seen as damaged goods due to publicized failures, and rather than focusing on the mistakes that were made and learning from those mistakes, investors may see an entire technology area as being a poor investment. Such failures can set a field back for years, as the gene therapy field experienced after a patient death in a clinical trial at the University of Pennsylvania in 1999. Fortunately, gene therapy has slowly recovered from this setback and is starting to see investment interest again.

So how can you optimize your search for financing if you’re working on something that’s seen as a tough sell?  The most important thing to keep in mind is that it’s not just about your technology; investors are also looking at you, and perhaps 50% of the factors that influence their investment decision will be related to you and your management team, not simply your products.  If you can show them that you’re a great business leader with enough experience in your field to learn from past mistakes made by others, and that you’ve got a solid team who have the skills to succeed where others failed, they may be willing to take a risk on you.

Next, look at investors who have backed successes in your field; finding an investor who’s a fit for your company and has invested in your area in the past is one of the most important aspects of fundraising. Seeking out the winners can help you hit the right target investors.

Finally, target funding sources who have incentives other than risks and returns. Foundations, patient groups and government funds might regard the promise of a potential breakthrough in your field as being worth placing a stake on, even without any guarantee of returns, accelerating the funding cycle, and shortening your time to market.

LSN Investor Database Feature: Non-VC Interest in Early Stage Medtech

By Max Klietmann, VP of Marketing, LSN

Recently, I wrote a feature detailing the increasing number of non-VC entities investing in early stage biotech companies. Due to the interest that article generated, we’ve decided to follow on with another LSN Investor Database Feature; this edition will focus on the early-stage investor interest in the medtech arena.

As mentioned in the previous feature, LSN’s investor research group maintains quarterly contact with over 5,000 active investors in the life science space, with a particular focus on those categories filling the void left by Venture Capital. This gives LSN unprecedented insight into what private investor trends look like today and going forward.

The chart below shows the results of an LSN Investor Database search mapping out all non-venture capital investors tracked by LSN with a declared interest – or mandate – in seed/venture stage medical technology companies with a prototype or early-stage clinical asset. The result is 561 investors globally. This should be very encouraging news to the executives of a space that has seen a great deal of turbulence in recent years in terms of fundraising trends.

Chart Issue 46Click to Enlarge

So what’s the next step? If you’re an early-stage medtech looking to raise money, these investor categories should certainly be on your radar. Second, do your homework on how exactly these categories behave in terms of investment activity. LSN’s research team can help elucidate this information on an investor-by investor basis. Finally, the space is in flux, so stay tuned as LSN continues to offer insights on the changing medical technology investor landscape.

Understanding your Therapeutic Asset’s Landscape

By Alejandro Zamorano, VP of Business Development, LSN

Most early stage biotech assets have the potential to target several disease areas. However, it is critical for entrepreneurs to maintain focus in a specific area – this helps to efficiently bring a product to market, and to show investors a firm commitment to a specific goal. But how do you choose which indication to pursue? Of course, there are advantages surrounding orphan drug regulation, hot disease areas, and other major factors. However, one area that many entrepreneurs do not investigate thoroughly is the early stage competitive landscape in their target indication area. This should, however, be a consideration in any entrepreneur’s mind.

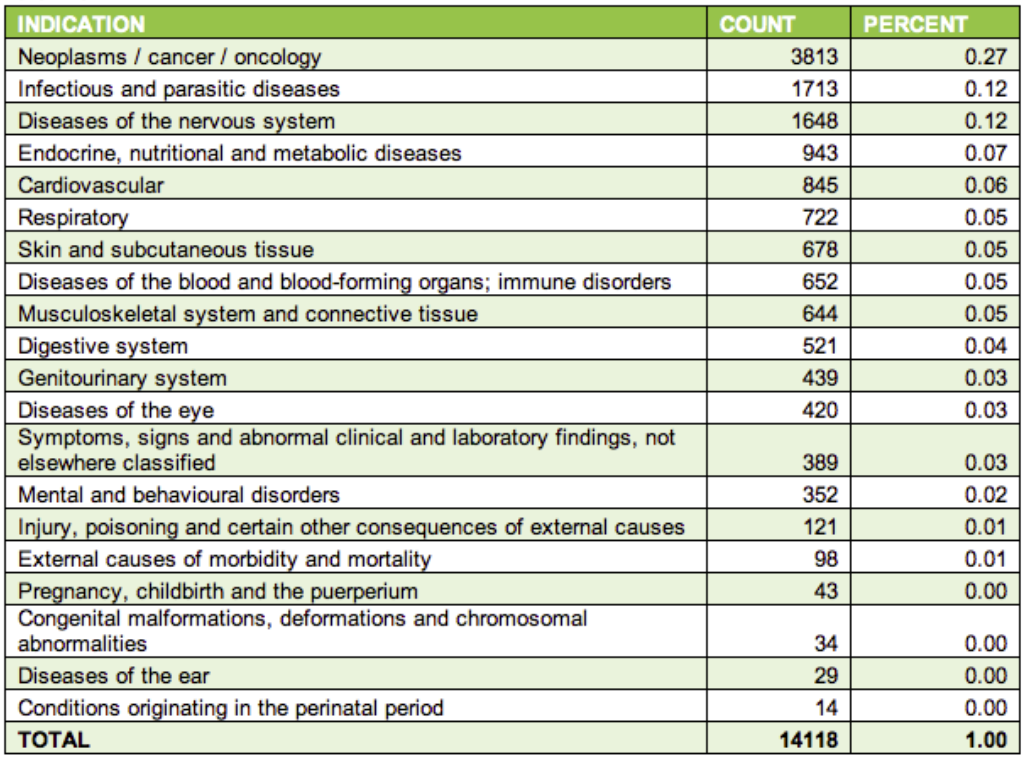
This article seeks to offer a 30,000-foot view of the therapeutic landscape, based on a sample of over 14,000 therapeutic assets. As demonstrated by the graphic below, there is a dense concentration of therapeutic assets in a select few disease areas. In fact, the top 3 main indications represent over 50% of all therapeutic assets currently being developed. This high concentration means that differentiating your asset will potentially be more challenging.

Number of Therapeutic Assets by Disease Area

Screen shot 2013-11-20 at 12.51.39 PM (2)Click to enlarge

Competition will surface not only in the form of showing clinical significance, but also in the fundraising process. However, on a positive note, the clinical path for development should be much clearer, as companies have most likely traversed the same regulatory path your therapeutic is now embarking on. Learning from your competitors always pays dividends.

At the end of the day, you know your asset best, and how you fit into the competitive landscape. What is true for one company may not be true for another, but it is undeniable that every company looking to commercialize an asset needs to understand the therapeutic landscape and how to maneuver it most effectively.

LSN Announces RESI II

By Max Klietmann, Conference Co-Chair and VP of Marketing, LSN

The LSN team is very pleased to announce the second Redefining Early Stage Investments conference, to be held Monday, March 24, 2014 in Boston. This event is the next in LSN’s ongoing conference series focused on creating a dialogue between emerging life science companies and active early stage investors from ten categories around the world. LSN is committed to maintaining its mission of moving science forward by creating a forum for early stage innovation and capital to meet, and we are building on last September’s success. We’ve made some exciting changes for the March event – Here are some highlights:

Full Day Partnering – RESI will have partnering meetings available for the full duration of the day.

More Investor Panels – We’ve increased the number and variety of investor panels available to conference participants, based on cutting-edge content derived from our constant research of the industry.

Free Workshops – RESI will host a series of in-depth workshops in the areas of outbound fundraising, valuation, and the legal landscape.

Disruptive Technology Horizon – RESI will host a half-day session on the emerging disruptive technologies that have the potential to redefine the industry in the future.

New Company Presentation Format – RESI is offering innovative life science companies the opportunity to showcase their technologies to investors via poster displays throughout the (expanded) exhibit hall, giving them full-day exposure to investors and other conference participants.

If you haven’t attended RESI yet, here is a quick overview of attendance distribution from last year:

  • Over 300 attendees last year (targeted 200), estimating 500 this year
  • Over 115 early stage investors from around the world
  • 43% International / 57% Domestic
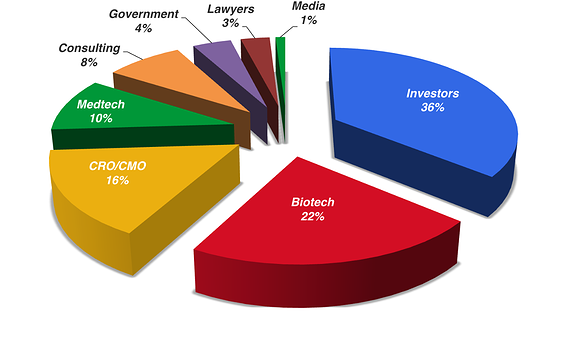
  • Attendee profile split per the chart below:

RESI Attendance BreakdownSpecial reduced earlybird registration rates for attending and exhibiting are available for a limited time only, so be sure to register now!

Special sponsorship opportunities are also available now.

We look forward to seeing you in March. Stay tuned for more RESI II conference updates.

A Word on Emerging Clusters

By Jack Fuller, Business Development, LSN

As a Boston-based company, Life Science Nation is by all accounts located in one of the greatest life science hubs in the world. An emerging company that can claim residence in Kendall Square somehow finds a certain level of implied acumen simply by virtue of being there. Investors also tend to gravitate toward the east and west coast “superclusters” when setting up offices. So how do companies outside of these geographic areas find and engage potential investors, given this apparent disadvantage?

Emerging Bioclusters such as St. Louis, Chicago, Colorado, and Florida – to name a few – have been growing through a combination of university, government, and private initiatives. Each cluster brings a unique dynamic of infrastructure and resources that have allowed the formation of innovative companies. I have spoken with several individuals at regional investment organizations who suggest that these are vibrant, growing communities of first class entrepreneurs and scientists.

As important as a regional network may be, an executive in an emerging cluster must maintain a global perspective. Any person looking to raise capital in today’s life science industry needs to think and act globally. Local investors and clusters are excellent at taking the first step, and have great experience in new company formation. Typically, good science and a solid management team are able to seed a company. However, in an emerging cluster, the funding gap between seed and a substantial series A tends to be larger than on the coasts.

Companies in emerging clusters have a few interesting value propositions they can distinctly take advantage of. First, many clusters are established around high-quality research institutions that provide a steady supply of qualified talent and innovation. Similarly, other clusters are home to major players in non-traditional “biotech” spaces such as AgBio and healthcare IT that can be taken advantage of when establishing local infrastructure and expertise.

One of the most important factors to an investor is the return per dollar invested.  There is a significant reduction in the cost of running a biotech company outside of Boston or the Bay area. When done correctly, a company can stretch $3-4M in the Midwest, to the equivalent of $6-7M on the coast. This decrease in operating costs means bigger returns for the investor. Investment in emerging clusters has been underfocused, and a savvy entrepreneur needs to leverage the regional momentum and resources available to become even more attractive than a similar company based in a major cluster.

When targeting global investors, the capital efficiency and strength of the management team become key factors in attracting significant interest. The question many investors will ask is: is this team going to be able to execute? The history of success stories, while present in emerging clusters, is still an area of concern to an investor.

All life science companies face the same challenges when raising capital. However, companies in an emerging cluster now have an opportunity to take the leap to the global stage. Take the question of execution out of the picture, and highlight the significant upside of investing in a company based in your region.