The Place to Meet Early Stage Investors

By Dennis Ford, Founder & CEO, LSN
Dennis book

LSN’s third Redefining Early Stage Investments (RESI) conference is fast approaching. Held twice a year, this event is the ideal place for scientist-entrepreneurs to meet early stage investors.

The idea for RESI came about while I was traveling and participating in a variety of domestic and international partnering and investor events. Considering the advertisements, I was surprised that so few qualified active investors attended many of the conferences. I was also shocked at the price given the limited investors turned out. The number of investors registered usually ranged from 20 for a medium-sized event to 40 or so for a large event. I knew that LSN could do much better because we had relationships already established with many of the early stage investors and strategic partners that scientist-entrepreneurs were seeking to meet. Thus, RESI was born, and this past March, 142 investors attended RESI.

The LSN investor-outreach process for the upcoming RESI conference has de-emphasized venture capital firms, which headline most life science partnering events. We welcome VCs, but we’ve been reaching out to many other investors with the goal of making both our panel content and our attendees as diverse as possible. By increasing the investor reach, we are broadening the variety of interests in the RESI partnering ecosystem. The investors who attend RESI include angels seeking high-risk, high-return early stage opportunities, foundations hoping to advance breakthroughs to improve patient care, family offices seeking long-term, high-impact investment opportunities, and the corporate development staff from pharma and large medical-device companies looking externally to fill gaps in their pipelines. Exhibit 1 shows the breakdown of early stage investor categories attending our upcoming fall event.
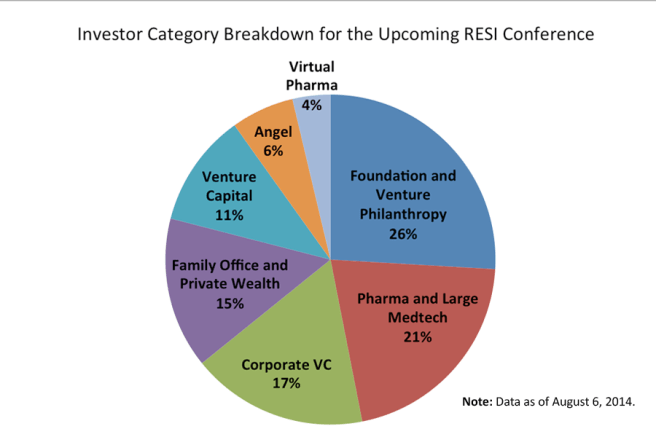
RESI Exhibit 1
Exhibit 1


The next RESI conference will be held at the iconic Fenway Park on September 17. With six weeks left to register, we already have exceeded our forecasts. All told, active investors from ten categories will attend. LSN will be host to 30 RESI Innovation Challenge participants and dozens of emerging life science entrepreneurs who will use our meta-tagged partnering system to connect with investors who are a fit for various industry sectors and stages of development. Using the LSN partnering system, a company executive can arrange meetings with a dozen or more investors in a day.

The majority of companies attending the fall event are in the biotech, diagnostic, and medtech sectors. A wide variety of service providers will also visit RESI, including contract research organizations and those that provide financial and legal services. To further diversify the RESI ecosystem and welcome more early stage device developers to the partnering table, we are hosting a new panel discussion on medtech investment. To see the complete one-of-a-kind content agenda, click here. Going to the panels alone will be an education in the changing landscape of early stage investment. Hope to see you there.
The Case for Small Markets with Large Returns: RESI Conference Announces Orphan Disease Panel

By Tom Crosby, RESI Conference Manager, LSN

Tom 2

In the United States, the orphan disease space has gained significant interest from the investment community due to the expedited regulatory approval process, combined with the lack of current treatment options that address many of these uncommon conditions. A wide range of investor types are targeting these diseases for many different reasons. RESI brings together veterans in the orphan disease space to compare and contrast the strategies and motivations of different investors in the field.

Moderated by Peter Saltonstall, President & CEO at The National Organization for Rare Diseases (NORD), the audience will hear from:

Mark Day, Senior Director, Strategic Evaluation, Alexion

Jean-Marc Quach, Executive Director, The Alpha-1 Project

Chris Adams, CEO, Cydan

Mark Barrett, VP, Head Strategy & BD, Rare Diseases, Genzyme

Panelists will introduce and cover the areas of the orphan disease field they are most involved with and interested in. What stage and level of data are they looking for prior to making an allocation? What is the best way to present an orphan opportunity to a potential investor? The session will outline how orphan disease opportunities are evaluated and valued differently than non-orphan technologies. What is their outlook for investment and scientific advancement for these niche diseases going forward?

RESI3

Corporate VCs Have a Global and Early Stage Focus

By Michael Quigley, Director of Research, LSN

mike-2

As large pharmaceutical companies have cut internal R&D spending, they have established and financed venture capital branches, which have quickly become a critical source of capital for emerging life science companies. In a previous article, we discussed the two types of corporate VCs and why they can be a beneficial source of funding. This article sheds more light on corporate VCs by examining some data points from the last 50 mandates that we received from this group and by making comparisons with the rest of the investor community.

A Global Perspective

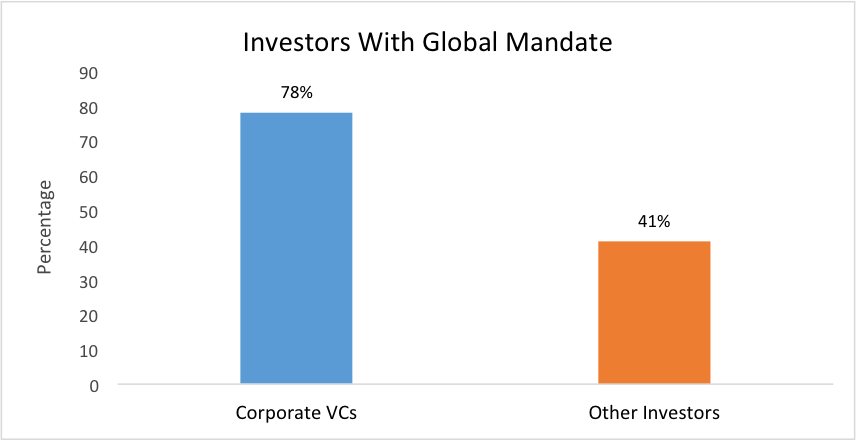
In general, more and more life science investors are pursuing opportunities worldwide; leading the pack are corporate VC players. Of the corporate VCs that LSN has spoken to, 78% have global mandates, compared with only 41% of investors from all other categories combined. (See Exhibit 1.)

Exhibit 1

The global investment focus of large pharma companies makes sense, as the majority operate worldwide. To uncover potential investments, these companies set up multiple offices around the world to act as external innovation engines or feeders for their parent companies.

An Early Focus

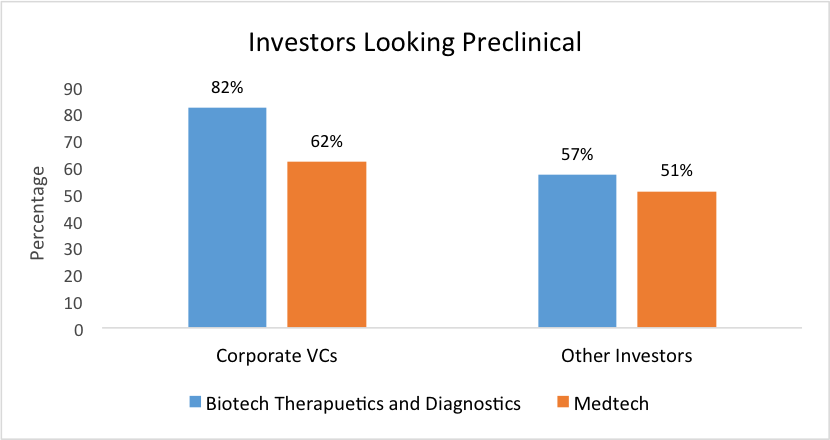
Another data point that can be extrapolated from LSN’s research is that corporate VC investors tend to be interested in companies and products at the earliest stages of development. This is true in the biotech and medtech sectors. For example, 82% of corporate VCs are interested in therapeutic and diagnostic companies that have technology or products in the preclinical stage, compared with 57% of other investors. (See Exhibit 2.)

Exhibit 2

Corporate VCs tend to have a good understanding of the scientific and regulatory hurdles that technologies face; therefore, these investors are more willing to evaluate and allocate to companies in the early stages of development. Additionally, corporate VCs are looking to fill their parent companies’ development pipelines. By identifying opportunities early, they are able to secure equity positions when the valuation of a technology or company is relatively low.

Large pharma companies aren’t the only corporate VCs in the life science space. LSN has also noticed that the venture divisions of a number of high-tech companies, such as Google and Samsung, have a growing interest in the healthcare sector. It is a positive development for the life science space that high-tech corporate VCs are joining large pharma to fill a crucial funding void that is being felt on a global scale.

July Roundup: 76 Mandates

By Lucy Parkinson, Senior Research Manager, LSN

lucy 10*10It’s been a busy month here at LSN, with our researchers gathering 76 mandates from a wide variety of investors between July 1 and July 25. (See Exhibit 1.)


investor type copy
Exhibit 1

If we had focused solely on talking to VCs this month, we would have had about a quarter of the number of investor conversations we actually had.

As always, we spoke to many investors who are interested in opportunities globally. Of those investors focused on one or more regions, most were interested in Canada, Europe, or the U.S. (See Exhibit 2.)

Exposure copy
Exhibit 2

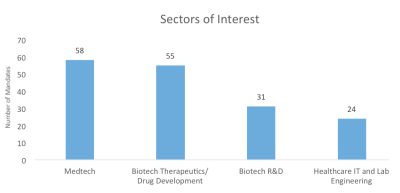
Investors who were interested in medical technology slightly outnumbered those focused on drug development. We also spoke to many investors who were interested in biotech R&D services or healthcare IT and lab engineering. (See Exhibit 3.)

Sectors of Interest
Exhibit 3

According to MedCity News, CB Insights Venture Capital Activity report confirms a continuing interest in medtech. The report notes that medical devices accounted for most of the deals during the second quarter, followed by biotechnology and drug development companies.

Are you surprised that we’ve had so much success in reaching out to investors during the month of July? In the past two years, we’ve learned that making contact with investors can often be a countercyclical process; while the rest of the business world is winding down for the summer or making the most of a holiday week, investors may have more time to respond to calls and emails and start building a relationship. Summer is no time to take a break from your fundraising campaign. Rather, it’s a great opportunity to follow up with people who haven’t gotten back to you or who expressed initial interest but haven’t taken the next step. The lighter summer schedule may provide the right opportunity to win a moment of an investor’s time.


Engineering the Future of Healthcare: RESI Conference Announces Medical Device Strategics Panel

By Tom Crosby, RESI Conference Manager, LSN

Tom 2

The medtech space currently represents an attractive opportunity for a large number of investors, as recent LSN data shows that there is a steady interest in medical devices. This all-new RESI panel focuses on investors who seek emerging medtech opportunities. LSN has assembled a stellar group of top medtech investors to give attendees a better understanding of how these investors view the market, evaluate a sector and parse early stage medtech firms and technologies.

Moderated by Karthik Ranganathan, Strategic Innovation at Becton, Dickinson & Company, the audience will hear from:

Josh Phillips, Managing Partner, Catalyst Health Ventures

Juan Carlos Serna, Vice President, HPA Ventures

Lawrence Cho, Senior Director, Corporate Strategy & BD, Medtronic

Aaron Sandoski, Co-Founder & Managing Director, Norwich Ventures

Specifically, panelists will introduce and cover  the types and classes of devices they seek to invest in. How do they work with their portfolio companies? What stage of device and level of data are they looking for? What is the role of intellectual property in initial correspondence? Panelists will also discuss preferences for investment size and structure, geographical and team requirements, and how to better identify organizations that are actively investing in early stage medtech companies.

RESI3

Early Stage Investors and Your Website

By Michael Quigley, Director of Research, LSN

mike-2When speaking with investors during the past week, I made a point of asking what information they look for on a life science company’s website in order to determine if they want to have a more in-depth conversation. The responses tended to be very similar despite coming from investors in multiple categories, including traditional VCs and family offices. Here are the six items that were most cited.

A Clear and Concise Description of What a Company Is Trying to Achieve

Your firm’s tagline should be the first thing that catches investors’ attention when they come to your website. In approximately four to eight words, your tagline should describe simply and adroitly your value added. You should elaborate on this in an elevator pitch, which describes your technology and mission in four to six sentences. Both your tagline and elevator pitch should describe your technology in a fundamental way that can be easily understood by people without a scientific background. Having these items supported by a few relevant images or a video is something that can really help investors visualize and better comprehend what it is that makes your investment opportunity interesting. By keeping the initial message as simple as possible, you can grab the interest of investors who may not be scientific experts in your particular field.

Information that Elaborates on the Opportunity

After catching investors’ interest with your tagline, elevator pitch, and visuals, you need to elucidate the market opportunity for your technology. This means clarifying the target market, its size, and any niche area that highlights the unmet need. Many technologies have the potential to target multiple indications and serve more than one market. However, it is very important that you demonstrate which of those markets you are targeting first. The majority of investors look for focused companies that have a clear path to a value-inflection point or exit. I am not advising against mentioning other possible uses for your technology, as these can add value to your opportunity. However, it is imperative that you make your immediate plans clear to investors.

A Company’s Complete Funding History

All of the investors who I spoke with specifically mentioned having a complete funding history available on the website. They said it makes it easier to decide whether or not to have a further conversation. Their preferences differed, however, with some investors looking for well-known institutional investors to already be on board, while other investors, particularly those that classify themselves as very early stage investors, prefer to be one of the first institutional sources of capital so that they can get in while the valuation is low and the cap table is still intact. NIH grants, incubator awards, a Series A round—investors want to know about all organizations that have invested in you and how much you have raised. By showing who has allocated capital to your company, you both establish credibility with investors and give them a better understanding of whether or not you are a fit for their investment mandates.

Management Biographies

A company’s management is arguably its most important asset when garnering interest—and ultimately an allocation—from potential investors. Your website should list every member of your management team with a photo and a short biography that covers their career accomplishments thus far. Again, this establishes credibility by showing investors what the members of your core team have been involved in prior to now. It is also important to note that both successes and failures can establish credibility in the space. Some of the investors I have spoken with specifically mentioned that they like working with management teams that have had an unsuccessful company, as teams often learn more from failure than success. Many investors consider management as important as, and sometimes even more important than, the technology, so by giving them a small window into your management team, you have the chance to directly market one of your most influential assets.

The Origin of the Technology

Investors want to know where your technology came from. Did you in-license the product from a university or did you develop it in house? If the former, which university and how did that relationship come to be? Were there any strong academics working on the technology, and if so, what are their backgrounds? By answering these questions on your website, your story becomes more complete, allowing investors to more fully understand how your company came to be and why the investment opportunity is a good one.

The Replicability of the Results

Although not always available, having your results and data validated by a third party through replication, the gold standard of scientific research, is becoming an extremely valuable piece of information to present to potential investors. If you have this kind of validation, it is crucial that you include it on your website, as the inability to replicate results is becoming a growing problem.

By incorporating these items into your website, you will make the decision process easier for investors, which will in turn earn you responses more quickly and save your campaign valuable time. Additionally, by having this information easily accessible, you have the opportunity to learn why investors are interested in your technology—or why they aren’t. Understanding your strengths and weaknesses lets you further hone your message and improve your ability to market yourself. Your website will likely not be the deciding factor that pushes an investor to make an allocation. However, a good site can save you invaluable time by reaching more investors with increasing effectiveness, which ultimately improves your odds of success.

For more information on website messaging, see our new book, The Life Science Executive’s Fundraising Manifesto, and the “Establishing a Web Presence” chapter.

Bookcover-Front

Virtual Pharma Partners: Guiding Assets to Commercialization

By Lucy Parkinson, Research Manager, LSN

lucy 10*10

There are many investment models used in the therapeutics sector, including the partnership model used by the innovative, hands-on, asset-centric Virtual Pharma groups. These investors, otherwise known as pharmaceutical management companies or pharmaceutical development companies, partner with small biotechs with the goal of building a portfolio of therapeutic assets and efficiently developing them for an exit opportunity. But how do virtual pharmas operate, and why might it make sense to partner with one?

The research team at LSN keeps in contact with virtual pharma groups because, quite simply, they are investors in early stage biotech. Rather than investing directly in companies, virtual pharmas invest in assets (in most cases, by in-licensing and then funding the asset’s development; in a few cases, by acquiring assets completely, often with the original rights owner maintaining a royalty share). Some virtual pharmas have been spun out by an investment firm, such as CMEA‘s Velocity Pharmaceutical Development or NEA‘s Tesaro Bio; others raise their funds independently. In many cases, the virtual pharma firm spins off each asset into a separate company. With their focus on a single asset, these new companies are more streamlined for the purpose of attracting other investors or making later-stage strategic deals.

There are some obvious tactical benefits to considering a virtual pharma partner.

Expertise. For scientist-entrepreneurs with deep research experience but who are new to the world of commercial drug development, it makes sense to partner with a company that specializes in getting drugs to market. Some of the virtual pharmas we’ve contacted specialize in a particular field, such as oncology or dermatology, and they are experts at the regulatory and market issues in that field. Others specialize in a particular part of the development process, such as Phase III trials, and are experts in managing those stages.

Strategic assistance. Virtual pharmas tend to have a very strong awareness of their space, and as one virtual pharma executive told me recently, “We don’t invest in assets that aren’t going to get later-stage funding.” In addition to knowing how to market the asset to investors, virtual pharmas also often have good relationships with CROs and big pharma corporations that can be harnessed to bring the asset through to an exit.

Focus. A virtual pharma director told me that his group generally works with biotech companies that have multiple promising assets. The virtual pharma takes over management of one asset and spins off that asset into a new company with staff focused solely on its development. This allows the biotech company to focus on developing the rest of its pipeline.

Monetization. Although the structure of these partnerships varies (much as big pharma partnerships do), many will involve up-front payments that can be used to finance the development of other programs.

Although the strategies of virtual pharmas are highly varied, there’s one consistent value they all share: it’s all about the asset. Make-or-break factors for other investors, such as where your company is located or whether it’s a privately held or publicly traded company, generally don’t apply. If you’re making a pitch to a virtual pharma investor, you should bear this in mind and keep the focus entirely on what’s unique about your asset, how the research data demonstrates its value, and how a partnership on this asset will make sense for both sides.