What Should the Next Generation of Incubators Look Like?

By Jack Fuller, Business Development, LSN

Jack 2

If you reside in one of the many growing or established life science clusters around the U.S., you have probably encountered the growing plethora of incubators or accelerators that are emerging to support nascent and semi-virtual companies. Often, these incubators are funded by a combination of state grants, corporate partnerships, and revenue generated from renting space to emerging companies.

When giving a tour, incubators are quick to point out the pristine lab space and glass-walled conference rooms they provide to start-ups. However, they often have little knowledge about what it takes to fundraise in the life sciences: a tactical approach that requires expertise in branding, marketing, and cloud infrastructure.

Dennis Ford, CEO of LSN, often speaks about the need for emerging entrepreneurs and experienced fundraising executives alike to upgrade their approach to outbound marketing. Phone and email canvassing techniques require the same diligence and determination that even the most complex scientific experiments demand. If an emerging scientist-entrepreneur can perform 100 experiments and get one positive result, there may be hope to teach them how to make 100 phone calls to a targeted audience based on fit and get one great meeting.

LSN has spoken with hundreds of emerging life science companies, and we have realized that not everyone can take this step. If that is the case, incubators that integrate a team of marketers and business development experts should be in the future. Incubators could create an infrastructure of experts to market the companies, providing everything from branding and messaging support to website design and cloud infrastructure—even seasoned business development to aid in scheduling and running investor meetings. This is an enormous void in the current incubator environment. Early stage companies are slowly realizing that good science alone won’t get them funded. Providing that next level of tactical infrastructure will help streamline a company’s fundraising efforts and help them see the straightest line to cash.

In return, the incubator would take a transaction fee if capital was raised—a fee that could be re-invested into the incubator to provide additional staff, expertise, and infrastructure to further promote an evergreen approach to incubating companies to bring them to the next step.

Would this model work? Time will tell, but as we say here at LSN: you can walk a mile, but at the last three feet, you still need to reach across a desk and shake someone’s hand.
Filtering the Noise: How Life Science Investors Manage Prospects

By Maximilian Klietmann, VP of Marketing, LSN

Max Smile 2

In this newsletter, we often discuss how emerging life science entrepreneurs should think about their fundraising strategy. This week, we’re going to look at the fundraising process from the perspective of a couple of investors.

I called a corporate VC fund and a family office in the LSN network; each is actively making allocations and has a mandate to make at least five investments over the next year. I asked a simple question: What does your typical month look like?

The deal-sourcing executive at the corporate venture fund was quick to say, “We get a lot of referrals, but more often than not, they’re only generally targeted. There are a few people in my network who really understand what we are looking for. I trust their judgment, and they pass me more relevant leads. However, most of the referrals I get aren’t great fits for us.”

Entrepreneurs should keep this in mind. You may get referred, but that doesn’t mean you are going to get funded. You may even get a meeting, but very often it will be what we at LSN refer to as mercy meetings: investors agree to meet with you not because your technology is a fit but because they feel obliged because you were referred, or thought they’d do you a favor. Such meetings rarely lead to anything substantial and investors will not spend a lot of time on.

“On average, I probably get 30 to 50 business plan submissions a week,” remarked a manager at a California-based family office. “Some are referrals, but most are unsolicited emails.” That equates to about 1,500 to 2,500 business plan submissions in a year for an investor that is looking to make only five investments. “Simply put,” he said, “I can’t reasonably go through that much information. I have to make a decision whether or not to continue reading after the first few sentences.”

This underscores how important it is for entrepreneurs to succinctly communicate their value to investors. “I’m sure there’s some great technology I’ve passed on, but if the CEO can’t tell me why his company is special in the first page, I’m not interested in doing business,” noted the family office investor.

So how many meetings result from unsolicited submissions? Answers from the interviewees varied from 15 to 30 meetings a month. This is an average hit rate of one out of ten. However, only a fraction of these ever move into due diligence and ultimately get funded. At the end of the process, a typical ratio for these investors is approximately one allocation for every 300 potential deals they come across.

How do emerging scientist-entrepreneurs improve their odds then? An accurate and up-to-date global target list of relevant investors that are a fit is critical. However, it’s not productive if you can’t immediately communicate why you are a great fit for an investor. This requires crisp marketing collateral that clearly explains what sets you apart from the other 30 to 50 proposals an investor received that week. In addition, you should stay focused and get as much feedback as you can. If an investor passes, ask why—that might be all it takes to get them to take another look and agree to a meeting.

Pharma-Licensing Deal Trends in 2014

By Lucy Parkinson, Research Manager, LSN

lucy 10*10

LSN gathers data on early stage life science companies and investors worldwide, but we also track global licensing activity and trends through the LSN Deal Platform. We analyzed 20 pharma deals that were publicly announced from January through April and spotted three trends that offer a glimpse of what the industry may expect from pharma-licensing activity in 2014.

Orphan Diseases Are Hot

About 25% of the pharma-licensing deals so far this year involve an orphan or rare disease asset.  The accelerated approval pathway for these drugs is driving pharma strategies toward small biotechs that have cultivated expertise and assets in these rare diseases.

Discovery and Target Validation Platforms Are in High Demand 

As big pharma companies have trimmed their in-house R&D operations, they are increasingly turning to outside partnerships for very early stage drug discovery. Four months into 2014, about 40% of the licensing deals in our data set relate to discovery and target validation.

Collaboration Continues to Be a Popular Model

Traditionally, big pharma companies license assets and are wholly responsible for drug development. However, as BioAssociate observed regarding 2013 deals, collaboration models are becoming more popular, because pharma companies can de-risk their strategic investments: they license assets early and collaborate on the development. Of the deals in our platform that involve assets rather than a discovery platform, over one-third are known to be structured as collaborations.

What These Trends Mean for You

Big pharma’s interest in orphan diseases, partnerships for early stage drug discovery, and collaboration for drug development bode well for small biotech companies. A deal with a large industry player can provide a source of revenue and a stamp of approval, both of which are helpful if you’re looking for investment. Collaboration in particular means that you can retain more control and influence when it comes to your assets.

In addition to big pharma companies, an increasing number of virtual pharma investors are focusing heavily either on licensing or acquiring assets rather than simply investing in biotech companies. These are typically investors that specialize in putting assets through clinical trials and then exiting through a deal with a big pharma company. Partners such as these could provide another pathway for your company to reach the market.

Source: http://bio-associate.blogspot.com/2014/01/biotech-pharma-2013-licensing.html


Angel Groups Are Evolving into Bigger Players

By Michael Quigley, Research Manager, LSN

mike-2As we enter the so-called “golden age” of life sciences, there is no shortage of funding opportunities for savvy investors. This has not been lost on angel groups.

There has been a significant rise in the number of angel groups targeting early stage life science companies. In the past year, approximately 25% of all angel dollars invested has been in the healthcare sector. Angel groups are making not only more investments but also larger ones, and their focus is longer term.

Syndication has allowed angels to take more substantial positions and to take advantage of the many opportunities available since the contraction in the VC sector. Also, the rise of capital-efficient life science startups, which outsource development, has allowed angels to place more bets and be longer-term players. Granted, angels like all investors prefer a low-risk investment with a fast turnaround, but the changing landscape in the life science arena is enticing them to increase their holding periods in order to achieve that profitable exit.

At LSN we actively track over 150 angel groups, one-third of which are looking to make investments of $1 million or more prior to any syndication. That’s a much higher investment than the $100,000 to $200,000 angels are often identified with. Moreover, many of these groups are becoming increasingly sophisticated in terms of their investment mandates and industry focus. As syndication continues to become more prevalent, angel investors could become important players in the course of a company’s fundraising cycle.

Sources:

http://www.fosters.com/apps/pbcs.dll/article?AID=/20140504/GJBUSINESS_01/140509798/0/FOSNEWS

http://www.lifescienceleader.com/doc/angel-investors-look-at-biotech-0001

Do Traditional Marketing Techniques Apply to Life Sciences?

By Dennis Ford, Founder & CEO, LSN

Dennis book

I am a big fan of Steve Blank. For those who are unfamiliar he’s an entrepreneur and startup thought leader who has created and promoted relevant timely programs revolving around  startup strategy, fundraising, and iterating small business.

A recent focus of his is i-Corps, an audacious effort supported by a number of government organizations and spearheaded by the National Science Foundation. The goal of this program is to help early stage innovators make their ideas and technologies into real products.

Steve really stresses being “market-focused.” I am simplifying here, but he teaches how to go about validating the market for a product. He is a proponent of polling and surveying techniques that help scientists determine if there are potential clients or users for a particular product. He then encourages scientists to find large groups of these potential users and vet them. If the scientists get agreement, they have validated the market and it’s full speed ahead. If they don’t, the scientists may have to iterate or pivot until they get a group consensus and thus, market validation.

Steve’s process is a universe onto itself. He teaches through his programs why using practical common sense methodologies can drastically help in determining market acceptability. Given the NIH’s recent announcement that they will participate in i-Corps, I’m anxious to see how he adapts his philosophy (developed for software and new age media) to life sciences. I expect that much of his philosophy will transfer well. Nevertheless, the life sciences arena is unique: More often than not, the need is rather obvious: these technologies are changing or saving lives.

Probably half of the early stage life science investors (for example, family offices, venture philanthropy, patient groups, and foundations) are not as concerned as other investors about rate of return on dollars invested. They want to find a treatment for a specific type of patient (in the case of family offices, it is often a family member). This goes beyond “market adoption” and requires a different way of thinking about how to approach fundraising.

The goal for these investors is finding the best assets and the best scientists to move science forward and improve patient lives. It’s not a question of justifying a market. These technologies are addressing serious medical needs, and the key for emerging scientist-entrepreneurs is to identify where they fit and how to target the investors that are right for them. Raising capital in the life sciences is different than a traditional “market validation” approach. It’s all about finding the right investor for you, and positioning yourself accordingly. The real news here is that the NIH is embracing the fact that scientist-entrepreneurs have to broaden their understanding of rudimentary sales and marketing.

Fundraising Tactics Spotlight: Communicating Clearly with Taglines

By Jack Fuller, Business Development, LSN

Jack 2

Life Science companies pitching investors have a tough job: It’s not easy to convince people to invest in a capital-intensive industry with a low rate of product commercialization. Then there’s the challenge of conveying an extremely specialized and complex idea to people who want to net out the technology quickly. To be successful, companies must work hard to communicate complex ideas at a level that is easily understood by all potential investors, not just the “science-literate.” As Charles Bukowski once said “Genius could be the ability to say a profound thing in a simple way.”

The first place this needs to be accomplished is in a company’s tagline. Taglines are ubiquitous in the industry, but very rarely does a tagline accurately summarize that “special sauce” that makes a company so exceptional. Prospects should be able to read a tagline and grasp the goal of the company.

Take a look at the taglines below. What do they tell you?


As you can see, taglines run the gamut from completely ambiguous and semi-descriptive  to great ones that communicate a company’s brand and value to potential investors.

The goal of a tagline is not to be clever or cute but to powerfully and succinctly communicate a company’s unique value proposition. There is no one formula for a tagline, as each company needs to distill its entire investor pitch into a crisp statement.

Take a moment to think about your tagline. Crafting a clear one is the first step in the process of creating a cohesive and compelling brand and will form the basis of your outbound campaign.

Validating the Importance of a Global Target List

By Alejandro Zamorano, VP of Business Development, LSN

Alejandro 10*10

One of LSN’s Investor Platform clients recently provided some insight on his fundraising campaign. We encourage feedback from our clients as it helps us to validate our methodology and to integrate improvements into our product. Our client is a molecular diagnostics company looking to raise $3 million to $8 million to expand and perform some key clinical studies.

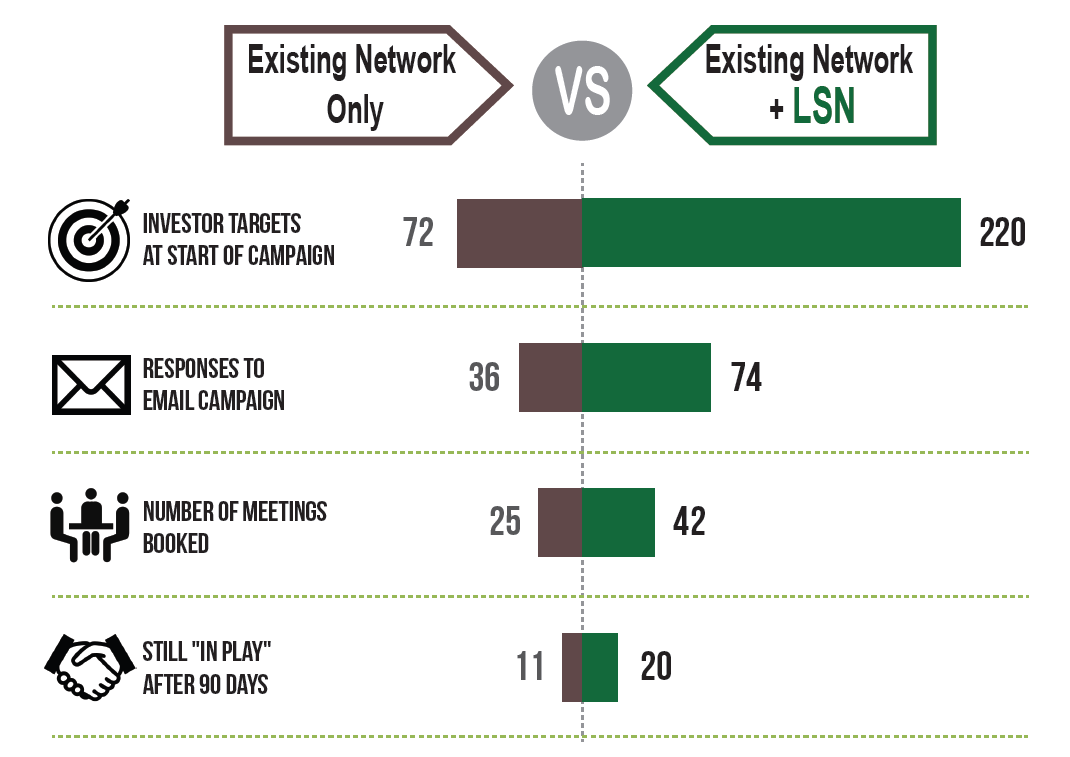
We first met the co-founder a few months before he elected to subscribe to the LSN platform. At first, like many emerging biotech and medtech entrepreneurs, he relied on the executive team’s personal network and referrals to find potential investors. He had a relatively large pre-existing network of almost 72 identified investor targets; thus, he felt that he did not need any additional help. The concept of “fit versus referral” was clear to him, but nevertheless, he felt sufficiently armed to pursue the campaign under his own steam.

In his first few months of fundraising, he reached out to his network and received responses from 36 of his prospects. He was then able to convert 25 of those responses into meetings, of which 11 remained interested in continuing the dialog. Despite his initial success, he soon hit a wall and was left waiting as his investor prospects began discussions internally. Weeks passed and investors delayed their decisions. It became apparent that in order to master the numbers game, he would need more prospects that were strong fits for his particular company. Before long, he resurfaced to LSN and elected to subscribe to the investor platform.

In the first 90 days of using the LSN Investor Platform, LSN was able to help this client identify and reach out to a global target list of 148 potential investors outside of his network. With the help of a clearly defined campaign strategy, and armed with all of the necessary cloud infrastructure to run an effective campaign, he was able to get 38 positive responses from investors he had previously not known about. He was then able to convert 17 of those responses into meetings, of which 9 were interested in continuing the dialog.

By expanding his list of qualified fits, our client was able to triple his meetings and double his investor conversations. He remains in negotiations with 20 investors currently. This is a shining example of why it is important to contact investors outside of your network and not to exclusively rely on referrals. Moreover, it shows that the same result could have been achieved in half the time, had our client started his campaign using the LSN Investor Platform form the outset. It all comes down to finding the maximum number of prospects and tactically working those leads into a handful of relationships that ultimately end in allocations.

Screen Shot 2014-04-30 at 3.32.33 PM