The Importance of Single-Asset Focus

By Maximilian Klietmann, VP of Marketing, LSN

Max Smile 2

LSN regularly speaks with numerous early stage entrepreneurs on the subject of asset focus. All too frequently, scientist entrepreneurs are reluctant to choose a single asset for the focus of their company unwilling to believe that it is in their best interest. Despite the feedback LSN gets from ongoing conversations with life science investors, many emerging biotech entrepreneurs still see this as a debatable point.

The typical arguments that emerging life science CEOs make against a single-asset focus may appear to make sense at first: Investors should prefer multiple shots on the goal or a portfolio of products is worth more than the sum of its parts. However, the key point that is often missed is that multiple assets frequently spell increased risk from an investor’s perspective. Why is this? It can be boiled down to three basic factors.

Capital Efficiency: The process of moving a therapeutic from discovery through the clinical trial process is extremely expensive, and it’s not getting cheaper anytime soon. Many investors tell us that given the inherent risks already present in the development process, they want their capital to be going towards the development of a single product that the whole company is focused on. This is preferable to spreading funds across a number of projects (increased overhead) that will get a portion of everyone’s focus (decreased attention).

Time to Market: The value inflection created by FDA approval is huge. A single asset on the market is almost always more valuable than a handful awaiting approval to move to the next trial phase. Relating to the capital efficiency point above, most investors we speak with would rather see one asset receive all the capital to move it across the finish line faster, regardless of the promise any other drug candidates may have.

Management Focus: This is the big one. Picking a single asset and having a laser-like focus on how to move it through the pipeline and to market shows that the management is dedicated, has clarity of vision, and is aligned with the investor. It exudes a “shortest line to cash” attitude and lets the investor be confident that the entrepreneur is able to lead the company.

VC Strategies Diverge in the Valley of Death

By Lucy Parkinson, Research Manager, LSN

lucy 10*10

We’ve talked about the fact that many venture capital firms have withdrawn from investing in early stage biotech startups, contributing to the so-called “Valley of Death.” However, there are still a number of life science VCs that remain active, so what are they doing with their dry powder now and why?

Talking to VCs recently, we found that the bulk of these funds are diverging in two directions. Some VCs are looking for nascent technological breakthroughs that are, generally, still a long way from becoming biotech startup companies. These VCs are building companies around these breakthroughs, gaining access to new scientific works either by maintaining a network of leading academics or by performing initial research entirely in-house.

There are some clear benefits to VCs taking this approach. Firstly, they can acquire assets for very low prices, before any of the classic value-inflection points. Secondly, the VCs can control a company’s direction from start to finish; they can select a management team and make strategic decisions, without a scientist entrepreneur getting in their way.

However, this strategy requires that VCs have a lot of connections and expertise. Scientists must be willing to hand their work over to the VCs, and the VCs must be capable of selecting and developing the most promising of these risky, very early stage assets. These VCs can cherry-pick the most compelling breakthrough ideas and build companies in-house, from the ground up, around these new assets. This then leaves real biotech startups—companies with pipelines and management teams—out in the cold (as far as VC investment goes). As a representative anecdote, an investment partner at a VC firm told us that in the past year, the firm reviewed 982 outside plans and invested in none of them. Another partner at the same firm later told us that it would consider investing in an external biotech startup but only in opportunities that were about three years pre-IND.

Other VCs have abandoned their appetite for technological risk and are instead focused on finding promising late-stage assets that they shepherd towards a rapid exit. These VCs typically look for investments that can be realized (often via a sale to big pharma) in a timeframe of 18 months to 3 years. Some have adopted a virtual pharma model and are focused solely on investing in assets rather than companies, either by in-licensing or simply acquiring late-stage product candidates and then managing the entire development of the asset until the exit point. Others do make equity investments in biotech companies, but some of these investors nevertheless see the company’s existing management as an optional add-on; one partner at a late-stage VC firm told us, “The development team is not necessarily the commercialization team.”

So what’s the takeaway? If you’re a late preclinical or early clinical-stage biotech company with a fully-formed team and a long development path ahead of you, this may actually be good news. More non-traditional investors will likely continue to move into this piece of the market to take advantage of the opportunity left by the VCs. The turbulence in the VC arena is far from over, however, and LSN will continue to monitor the latest trends in the investor space as the sands continue to shift.

FDA Proposes Expedited Access Program for Medical Devices

By Michael Quigley, Research Manager, LSN

mike-2Earlier this week, the FDA announced a new program that intended to provide earlier access to unapproved medical devices for certain patients. The EAP (Expedited Access Premarket Approval Application) program will allow companies to directly engage with the FDA sooner to collaboratively develop a plan for collecting scientific and clinical data in order to get patients safer and more effective devices sooner. The basic objective of the program is to diagnose and treat patients who are suffering from serious conditions and have medical needs that are unmet by current technology.

So, which companies are allowed to apply for the program? According to the FDA, a company is eligible for participation in the program as long as the medical device in question meets these standards:

• It is intended to treat or diagnose a life-threatening or irreversibly debilitating disease or condition.

• It is able to meet at least one of the following criteria:

1. The device targets an indication where no approved alternative treatment/diagnostic exists.

2. The device is technology that provides a “clinically meaningful” advantage over existing technology and/or approved alternatives.

3. Availability must be in the patient’s best interest (as determined by the FDA).

• The device has an acceptable data-development plan that has been approved by the FDA.

So what does the EAP program mean for the industry as a whole? One obvious foreseeable impact is the attraction of more direct investment into early stage devices.  This is great news, especially since early stage devices have had a tough time raising capital in recent times.  Moreover, early collaboration with the FDA means more guidance in setting clear clinical endpoints and having a better definition of what data is required to move forward. This increased regulatory transparency will hopefully increase the odds of approval (another checkbox for more risk-averse investors). At this point, the FDA has only released preliminary information on the program, but device companies and investors should keep an ear to the ground, as the details of the new program are released over the coming weeks.

Source: http://www.fda.gov/NewsEvents/Newsroom/PressAnnouncements/ucm394294.htm

Top 5 Indications For Non-VC Early Stage Investors

By Maximilian Klietmann, VP of Marketing, LSN

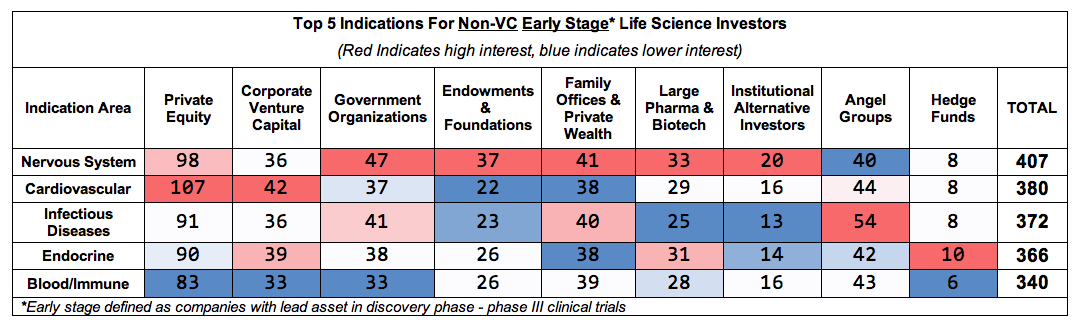
Max Smile 2One of the LSN’s Research Team’s key points of focus is on investors filling the void left by Venture Capital in the life sciences space. Today, we’ll take a look at the non-VC early stage (discovery-ph. III) investors in biotech therapeutics. Let’s take a look below:#58 1

As far as indication interests go, CNS leads the way, with over 400 non-VC’s seeking opportunities in this indication area. This is followed closely by cardiovascular and infectious diseases. Endocrine and Immune disorders are also close behind. All disease areas in the top 5 have over 300 active early stage investors seeking opportunities.

So what is the takeaway? Well, for one thing, this is clear validation that non-VC investors are active in early stage biotech. Moreover, if you are raising money for an asset in one of these indication areas, but you aren’t looking at non-traditional investors, you are missing out on 300-400 potential investor fits. Keep following LSN for updates on where early stage investor interest is moving as the landscape continues to shift!

Generic Companies Becoming More Active In Licensing

By Patrik Frei, CEO, Venture Valuation

The recent acquisition of Forest Laboratories Inc. by Actavis for 25 billion USD shows the trend of generic producers moving into the innovative drug space; with fewer blockbusters on the market, companies focused on generics will need to move into innovative therapeutics.

The acquisition of Forest Laboratories Inc. by Actavis is indicative of where we may see much future growth of generic companies – namely, patented innovation. Such projects can either be generated in-house or through licensing / M&A of innovative emerging biotech companies. Through the extension of the business model of generic companies, they will be able to control the whole life cycle of drugs from the patent protection into the generic phase. Novartis actually implemented this approach many years ago with the purchase of Hexal and Eon Labs, which later became Sandoz. However, it is now evident that generic companies are going the opposite direction from generic to innovation. This makes sense, as generic companies are in an increasingly attractive market position, and have the revenues to support significant licensing activities.

The same trend is not limited to the US and EU. It is also visible in Asia where many generic companies are based. Based on our own analysis, the demand in Asia is led by China, followed by South Korea. About a third of the companies that are seeking in-licensing opportunities in Asia focus on oncology followed by metabolic diseases. In terms of stage, over half are looking for pre-clinical products and about a quarter for clinical stage products. LSN and Venture Valuation track this activity on a global basis, and as this trend develops, we will keep you up to date on how this emerging category is changing the landscape for emerging biotechs around the world.

Investors Seeking Software-Enabled Medtech

By Michael Quigley, Research Manager, LSN

mike-2Big data has not gone unnoticed among early stage life science investors. The intersection of software and biology is one that the LSN research team has noticed to be an area of increased investor focus in recent months. The technologies in this space include devices or tools that are able to record and/or transmit biological data as well as software systems that are able to analyze sets of biological data for further use. Basically, this is the convergence of mobile technology, cloud data infrastructure, and next generation medical devices.

LSN tracks 244 investors active this space, and has secured over 100 mandates to invest in this sector over the last 10 months. Examples of technologies in this space include implantable or wearable devices that are able to generate and wirelessly transmit live information on the patient, or genomics platforms that are able to diagnose disease long before any symptoms are shown. These are just a few of the possibilities of those technologies, and applications for their use include increasing the efficiency of drug discovery and lead optimization, increasing the effectiveness of personalized medicine, increasing efficacy in clinical trials and ultimately significantly lowering the cost of healthcare all the way from drug discovery to critical care.

One class of investor that has taken particular interest in this space is the corporate venture capital arms of large healthcare providers. This is due to these devices’ ability to greatly lower the point of care cost by getting doctors and nurses accurate information on a patient’s health sooner, saving valuable time in emergency situations. Another interesting investor group with high interest here is investors and companies that historically have been more involved in the software and IT sectors, and see this as an opportunity to engage in the life sciences sector without straying too far from technologies they already understand.

This is a time of opportunities for companies in the space, as many of these sources of capital are just beginning to focus their energies on this sector. It means more capital, more opportunities to secure funding, and hopefully more products making it to market sooner. Stay tuned as LSN tracks upcoming developments in this space.

Early Stage Investors Go Global

By Dennis Ford, Founder & CEO, LSN
Dennis bookDoes it make sense for a life science fundraising executive in Europe to look internationally for early-stage funding? Should U.S. based firms look at investors in Europe and Asia?  As the folk singer Bob Dylan sang “the times they are a changing” and the answer is yes!

To someone looking to fund a life science startup ten years ago, the funding possibilities would have been primarily local.  Government programs and angel networks are almost invariably regionally-focused, as are many VCs (particularly within the long tail of smaller VC funds that used to provide capital to life science start-ups, many of which have now closed their doors).  However, the new investors on the stage today are typically much broader in scope.  Large pharma companies and global PE companies that used to focus on mid to late-stage opportunities are now looking to capture the value of emerging technologies; from the opposite direction, medical foundations that used to support only basic biology research are now focusing on getting new breakthroughs out of the lab and into the marketplace, and while some foundations are regionally based, many are looking for advancements in their field globally.  Family offices, too, are most often interested in opportunities worldwide.

To an entrepreneur unaware of how the world has changed around him, regional investment can become a self-fulfilling prophecy; the entrepreneur will focus their fundraising campaign on the traditional, mostly regional sources, and never reach out to the new global investors that might be very interested in the opportunity.

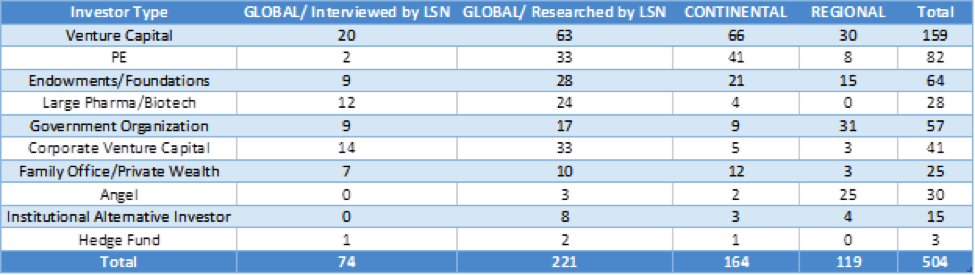
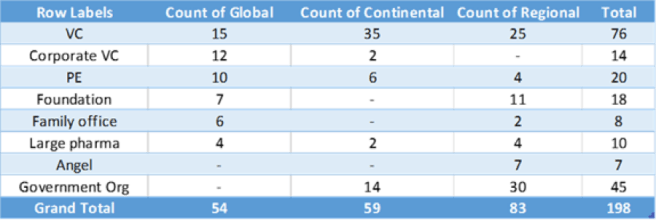
LSN Research in collaboration with Venture Valuation, Biotechgate Database has examined the geographical scope of the investors who take part in early-stage life science deals.  We looked at the trove of financial data available via the BTG Company Platform, and took a sample of small financing rounds ($10m or less) raised by companies developing a preclinical or Phase I therapeutic product.  From this sample, we aggregated a list of all the lead and co-investors who had participated in these deals, and then we took a more detailed look at each of these investors and assessed the range of their activities.  To keep things simple, we categorized the scope of each investor’s allocations as

1)    Global, anywhere on the planet where companies are a fit for investor.

2)    Continental, North America, Europe or Asia.

3)    Regionally, focused on small discrete geographies like Massachusetts, California, or specific countries in Europe.

Sample 1: From Biotechgate Company Database

 Lead and Co-investors that have Allocated <$10 Million to Pre-clinical or Phase I
Sample 2

As you can see, about 25% of the investors that are active in these early stage deals reported in BTG financing rounds database are global investors. To further support this, we also pulled data from investors in the LSN Investor Database who are willing to allocate under to $10 million in a single round into Pre-clinical and Phase I stage therapeutics companies.

Sample 2: From LSN Investor Database

Investor that are willing to Allocate under $10 Million and are looking at Pre-Clinical and Phase I
sample 1

About half of the investors who take part in early-stage funding rounds are regional or continental players.  Government organizations dominate the regional category, and most angel networks are regional in scope, as are many VCs.  It’s worth noting that the BTG data is historical, and we can expect regional-based investment to be a shrinking category in the immediate future, as recent cutbacks to both US and European government funding in the name of austerity and sequestration will reduce the role of regional government in life science financing.

The other half of the investors in our sample are looking for opportunities more broadly, whether that be across a whole continent (such as pan-European investors and firms that look all over North America for opportunities) or worldwide.  Global investors include many big pharma firms and their corporate VCs, who naturally look worldwide to fulfill their strategic needs.  While some foundations are focused on regional development, many are eager to support important work in their fields of interest no matter where it’s taking place.  We also found that most of the family offices in our sample are global in scope, as are some VC and PE firms.  Wherever your life science company is located, you can look to these investors as sources of funding.

Early Stage life science investment is in transition.  This means that there is a clashing of the old ways and methodologies and the generally accepted status quo. The investor available categories have morphed as new players fill the void left by the early stage VC investors.  The challenge today is to get everybody up to speed on who’s who in the market place and educate the players on how to find the best fit for their capital needs. Below are 4 points to keep in mind when developing a fundraising strategy.

1)    Life Science fundraisers are in two camps.  One camp still hangs on to out-of-date strategy that the investor market process and protocol is as follows friends and family, angels, government grants, followed by VC’s.   This might have been true 5 years ago but is no longer relevant as new players have entered the arena and VCs have waned due to lack of funds and unproven track records.  The new process looks more like this: friends, family, angels, funding portals, government grants, followed by parsing the new investor landscape and determining who is a best fit for a fundraiser.  These new investors including single and multi-family offices, venture philanthropy, patient groups, corporate development, private equity, hedge funds, pensions and foundations.

2)    While many believe that emerging life science companies cannot canvass and get allocations from global investors and that their market place is limited to only regional investors, this is simply not true; each investor type has its own modus operandi, and while some might be local, such as angel networks or regional VCs, a corporate venture fund, foundation or a patient group may have no such requirement and will invest globally.  The profile and strategy of the life science investor determines their investment sphere.  The new investors on the stage today are typically global in scope.  Large global pharma companies that used to focus on late-stage opportunities are now looking to capture the value of emerging technologies; from the opposite direction, medical foundations that used to support only basic biology research are now focusing on getting new breakthroughs out of the lab and into the marketplace, and while some foundations are regionally based, many are looking for advancements in their field globally.  Family offices, too, are most often interested in opportunities worldwide.

3)    Investors are moving upstream and this creates a trend that in turn moves other investors to join in. Previously only certain investor types made early-stage investments, but now traditionally mid to late players are getting involved early and this then creates a pull on the rest of the investor base.  This makes early stage a topic of consideration for all the mid to late stage investor categories. Investors are demonstrating that in order to remain competitive you need to form early alliances and partnerships with emerging companies, or you will miss out.

4)    It has been well documented that VCs in general have underperformed in the early stage life science space and therefore have not been able to garner investors into their funds, forcing a tactical regrouping of their early stage strategies.

Global Investors Making Early-Stage Deals in Europe

As LSN’s mandate data makes clear, many life science investors are looking for opportunities all over the world.  Recent history bears this truth out; financing rounds for European biotech companies often feature investors whose activities are global in scope.  Here’s a few representative examples of investors from outside Europe who have participated in small, early-stage European biotech and medtech financing rounds within the last 3 years.

Broadview Ventures is a family office based in Boston that invests in early-stage cardiovascular and neurovascular breakthroughs worldwide.  The firm’s recent global investments include Finland-based Laurantis Pharma and Israel-based Vascular Graft Solutions Inc.

Industrial Bank of Taiwan Management Corporation manages a Boston-based life science venture fund that has made investments worldwide.  The firm’s portfolio includes Netherlands-based To-BBB.

New Leaf Venture Partners is a venture capital firm with offices in New York City and San Mateo.  New Leaf is primarily focused on the US but has nevertheless made several recent investments in Europe, including investing in Karus Therapeutics in 2012.

The Michael J Fox Foundation is based in New York City and provides research grants of up to $2.5m to biotech companies in the Parkinson’s disease field.  Since 2010 the foundation has offered grants to at least three European companies – Hermo Pharma Oy, AFFiRiS AG, and Sapiens Steering Brain Stimulation GmbH.

SV Life Sciences is based in Boston and has additional offices in San Francisco and London.  The firm has made several investments in Europe, including investments in seed rounds for companies such as Autifony Therapeutics, Vantia Therapeutics, and Bicycle Therapeutics.

And finally, many global pharmaceutical companies based outside Europe invest in early-stage biotech and medtech opportunities within Europe, including Merck, Johnson & Johnson, Astellas, Mitsubishi Tanabe, AbbVie, Takeda, and Baxter International.  These companies invest in Europe both via strategic in-licensing and acquisitions and also via their corporate venture capital funds.