Understanding the Mandates for Moving Science Forward: RESI Biotech Venture Philanthropy Panel Announcement

By Tom Crosby, RESI Conference Manager, LSN

Tom 2At the upcoming RESI Conference on January 13, 2015 in San Francisco, leaders from the top venture philanthropy organizations from around the world will discuss their experience with impact investing. Venture philanthropy is one of the most talked about funding models in early stage life science investments today. Because venture philanthropy organizations typically fund on a multiyear basis, these heavily donor-funded organizations are working towards making significant results possible on a quick time line.

LSN is pleased to announce the representatives for the biotech track of venture philanthropy. The complementary session on venture philanthropy in the medical-device space will be announced at a later date.

Moderated by Brian Horsburgh, Trustee of the NeuroNetworks Fund, the audience will hear from:

Panelists will address the following important questions on investing for impact: What do venture philanthropy investors look for in initial correspondence? What goes into the process of investment selection and due diligence? What value can venture philanthropists bring to your company in addition to capital? The session will also cover the metrics that are most important in evaluating progress and how grantees and donors are involved in analyzing these results.

If venture philanthropy investment is part of the plan to get your company funded, this panel presents a great opportunity to broaden your network while updating your understanding of these organizations.

RESI 4 Early Bird

Life Science Opportunities in Emerging Markets

By Shaoyu Chang, Research Analyst, LSN

Shaoyu 10*10The biotechnology industry is growing in the Asia-Pacific and Latin America regions,[1] and it is attracting local and foreign entrepreneurs and funding. Compared with companies in developed markets, ventures in these regions have unique opportunities and challenges as a result of the large populations and rising healthcare requirements. Two areas of R&D hold particular promise.

Medical devices—particularly diagnostic equipment, implantable devices, and products for the prevention of disease—represent a rapidly expanding market in China, India, and Brazil, given their aging populations. Because consumers in these countries are also often brand-conscious and willing to pay higher prices for better quality products,[2] large medical-device manufacturers from Western countries are positioning themselves to tap into the market potential by merging with or acquiring local players. [3] For example, in 2013, the UK’s Smith & Nephew announced the buyout of Indian trauma-device maker Adler Mediequip. This move followed in the footsteps of other major mergers or acquisitions by Stryker, Zimmer Holdings, and Medtronic.

The generic drug market is another area of promise in emerging economies. While big pharmaceutical companies in developed markets are plagued by patent cliffs and generic competition, generic drugs have solid double-digit growth in emerging markets. The rising prevalence of chronic diseases along with cash-strapped healthcare systems and consumers’ fear of counterfeit products have created a demand for low-cost, high-quality treatments. It is noteworthy that while multinational corporations such as Atavis, Mylan, and Abbott are gaining a more significant foothold in the emerging generic-drug markets, drug makers from the developing world, such as Ranbaxy from India and Aspen from South Africa, are now among the top players in the field and are operating on a global scale.

Therapeutics currently accounts for the largest chunk of total funding in most biotechnology hubs. However, R&D for new drugs is a high-risk path in emerging economies in light of its demand for capital, talent, and a favorable regulatory environment. “It needs 75 different kinds of expertise to develop a new drug,” warned Jonathan Flaming, General Partner with Oxford Bioscience Partners, who spoke at a recent conference in Boston. “Even in the U.S., you cannot do it everywhere.”[4] He believes that an emerging economy such as China is not well positioned to develop new therapeutics for several reasons, including the lack of professionals and the cultural issues. Mixed results from government-backed incubator initiatives, such as Malaysia’s BioValley[5] and India’s ICICI Science Park and Gujarat Science Park,[6] appear to support his point.

Emerging markets represent a vast and growing need for healthcare innovation that is underserved by lack of local infrastructure. This presents a significant opportunity for companies working on technologies in developed countries that are able to penetrate these emerging markets. LSN’s research team has uncovered a number of investors in the Asia-Pacific region that are looking for companies that are developing products for Asia and other emerging markets. Be on the lookout for more articles on this topic as we uncover additional information on the investment landscape for these regions.

[1] Gautam, A., & Yang, S. (2014). “Market watch: A framework for biomedical innovation in emerging markets.” Nature Reviews Drug Discovery, 13(9), 646-647.

[2] Weeks, L. “Five Trends Transforming the Medical Device Industry in 2014.” June 5, 2014. GxP Lifeline. Accessed from http://mastercontrolinc.blogspot.com/2014/06/five-trends-transforming-medical-device.html.

[3] Buford, T. “Trend continues as Big Orthos focus on emerging markets.” June 30, 2014. OrthoStreams. Accessed from http://orthostreams.com/2014/06/trend-continues-as-big-orthos-focus-on-emerging-markets/.

[4] Flemming, J. “What are the Best Cross Border Opportunities Today for American and Chinese Entrepreneurs and Investors?” October 25, 2014. Talk at 2014 CABA Biomedical Investment & Entrepreneurship Symposium, Boston, MA.

[5] Lerner, J. (2009). Boulevard of broken dreams: why public efforts to boost entrepreneurship and venture capital have failed–and what to do about it. Princeton University Press.

[6] Chakma, J., Sammut, S. M., & Agrawal, A. (2013). Life sciences venture capital in emerging markets. Nature biotechnology, 31(3), 195-201.


Family Offices Investing in Early Stage Medtech: RESI 4 Announces First Panel

By Tom Crosby, RESI Conference Manager, LSN

Tom 2At the RESI Conference in September, LSN hosted a panel of family office investors that attracted a standing-room-only crowd and received excellent reviews. Given the success of that session, LSN is pleased to announce the first panel for RESI 4 San Francisco, January 13, 2015: Family Offices Investing in Early Stage Medtech. This will run simultaneously with Family Offices Investing in Early Stage Therapeutics, the details of which will be announced at a later date.

In recent years, family offices and private-wealth investors have become an increasingly important pool of capital for fundraising entrepreneurs in the life science space. Unlike angels or high-net-worth individuals who generally have up to $100 million in capital and opportunistic investment mandates, family offices and private-wealth groups represent families and individuals who have $100 million to $1 billion or more in total assets and who use a more institutional investment approach.

The amount of capital that these groups manage enables them to have a dedicated staff for screening, due diligence, deal selection, and portfolio management. However, often motivated by more than only financial returns, many family offices have taken an interest in the potential social impact that investments in the life science sector can bring.

This panel spotlights family offices— One of the new categories of investor that has entered the early stage arena vacated by VC.

Moderated by Bill Brah, Founder & Executive Director of UMASS Venture Development Center, the panel includes the following speakers:

Alejandra Paradones, CEO & Founder, BSI Capital Group

Neil Wyant, Managing Director, Everett Partners

Clay Heighten, Founding Member, Green Park & Golf

Norm Gitis, Managing Partner, Lymo Investments

What motivates family offices to invest in the space? Why do they invest directly? How are family offices found? How are deals generally structured, and how do the terms of family offices differ from the terms of other investor classes? Panelists will answer these questions as well as discuss how an entrepreneur can get in touch with these investors and the information they look for in the initial correspondence.

What—in addition to capital—can these groups bring to the table for an early stage company? Find out at RESI San Francisco, January 13, 2015, at the Marines’ Memorial Club and Hotel.


RESI-4-Banner-3x8[5]

IPO’s Recycle Cash Back into Life Sciences

By Michael Quigley, Director of Research, LSN

 mike-2Several significant factors have been attracting capital to the life science sector over the past two years. An IPO explosion has provided many life science investors with positive exits, and, in turn, they have established new funds to put some of that capital back to work. In addition, new investors have come to the sector as a result of the number of successful IPOs and low interest rates; investors are looking for better returns. These factors led to life science funds raising an estimated $3.5 billion in 2013 alone.[1] Several funds have continued to raise capital this year.

This is positive news for fundraising entrepreneurs, and their next step should be to pinpoint the funds that have raised new capital and their investment targets.

The LSN research team has identified and interviewed more than 100 investors who have raised new capital since 2012. These investors fall in eight categories. (See Figure 1.)

1
Figure 1


Venture capital and private equity represent the largest number of investors; however, the other investor types represent a significant amount of new capital. Although each of these investor categories have various motivations for investing in the space—for example, financial, philanthropic, or strategic—it is promising to see so many groups with new capital to allocate to the space.

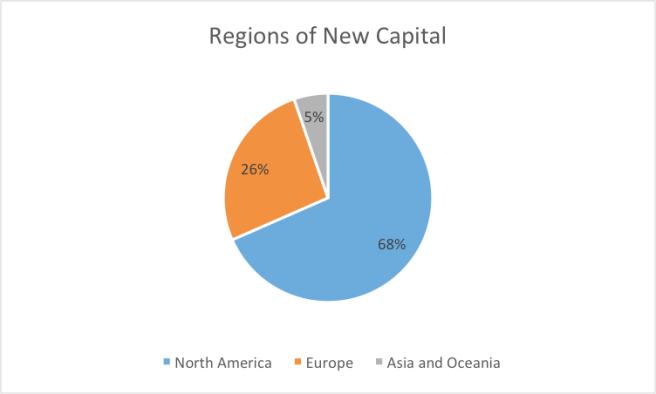
Also worth noting are the regions where these investors are based. The investors we identified are based in 20 countries in North America, Europe, and Asia, and Oceania. (See Figure 2.)

2
Figure 2

This distribution of investors with new capital reflects the IPO environment in these regions. The U.S. and therefore North America has had the highest number of IPOs, followed by Europe and Asia and Oceania. More important than where the investors are based, however, is where they are looking to allocate. Of the investors we spoke with, more than 50% are looking to invest across continents or globally. Previous articles in this newsletter have discussed the globalization of investment in the life science sector; this trend is validated by the current interests of funds and investors.

It would appear that the time is now for a start-up to execute a fundraising campaign if it has the data and team to support it. Not only is there capital to be had, but early on in a funds lifecycle, investors often consider research and technologies at earlier stages of development as the investors have the time and capital on hand to support them.


[1] Life Sci VC, “Perspectives on VC-Back Biotech: Looking Backward & Forward,” 2013 (http://lifescivc.com/2014/01/perspectives-on-biotech-looking-backward-forward/).


Partnering with Corporate Venture Capital: Tips from Industry Veterans

By Shaoyu Chang, Research Analyst, LSN

Shaoyu 10*10The role of corporate venture capital (CVC) continued its remarkable expansion in 2014. In the second quarter, CVC funding accounted for 29% of total venture capital funding. In the healthcare sector alone, CVC funding soared to a five-quarter high of $1.4 billion, up 200% from the previous quarter.[1] SR One, Novartis Venture Funds, and Johnson & Johnson Development Corporation led CVC funding in life sciences, while Aduro Biotech, Coherus BioSciences, and Principia BioPharma successfully raised more than $50 million in financing rounds with their CVC partners.

CVC funds are an attractive option for life science entrepreneurs for several reasons. Compared with other investors, CVC funds are not only able to provide more capital but also willing to take on riskier projects with promising potential. Working with industry veterans can provide start-ups with critical know-how in areas such as technology design, clinical development, and product commercialization.[2] And in some cases, CVC investments lead to an acquisition or strategic partnership.

How should a fundraising executive approach a CVC fund? At the most recent RESI conference, experts from six prominent CVC funds gave the following tips.

To begin with, entrepreneurs should understand what CVC funds are looking for and manage expectations from both sides. As discussed in our previous blog post,[3] CVC funds come in different flavors. Generally speaking, internally focused CVC funds seek innovations that can bolster the future portfolio of their parent company, while externally focused CVC funds look for technologies from a return-on-investment viewpoint, with less regard for the mission of the parent company. Aligning your goals with the expectations of a corporate partner is essential. A recent study found that this is an area where there is often a mismatch.[4]

CVC funds prefer to work with entrepreneurs who have a tight grasp of intellectual property and a good understanding of the commercial potential and the competitive landscape. They also favor an academic team with whom they have collaborated or with previous experience with another industry partner. To win the confidence of a CVC fund, first-time CEOs are advised to invite experienced entrepreneurs to join the start-up and build a team with credible advisors, consultants, and board members. “If you ask for money, you’re going to get advice. If you ask for advice, you’re probably going to get money,” a panelist said.

Entrepreneurs should invest time to foster relationships. Simply submitting proposals through the websites of pharmaceutical companies is not going to result in funding. It requires a substantial amount of energy to find key industry personnel who have the scientific expertise to understand the discovery and a senior position to make decisions. When a start-up has identified the key people, entrepreneurs should use conferences, social networks, personal referrals, email, and phone calls to engage these folks in conversation.

Finally, our panelists emphasized the importance of long-term relationships. Although the first contact with a CVC fund may not always develop into an investment, entrepreneurs are encouraged to maintain the dialogue. New opportunities may open up, investment criteria may change, or a portfolio’s requirments may change. “We have a lot of continuing dialogues that blossom into something really cool and end up different from the initial conversation,” a panelist concluded.


[1] CB Insights. “Corporate Venture Capital Report – Q2 2014 – CVCs Participated in $4B of Funding Across 187 Deals,” September 23, 2014. Accessed from https://www.cbinsights.com/blog/corporate-venture-capital-report-2014-q2/.

[2] Behr, J., & Murray, P. “In Search of Dry Powder,” Nature Biotechnology, October 31, 2013.

[3] Fuller, J. “Gorillas at the Table: Corporate Venture Capital,” Life Science Nation, August 9, 2013. Accessed from https://blog.lifesciencenation.com/2013/08/09/gorillas-at-the-table-corporate-venture-capital/.

[4] McCammon, M. G., Pio, E., Barakat, S., & Vyakarnam, S. “Corporate Venture Capital and Cambridge,” Nature Biotechnology, October 9, 2014.


 

Scientist-Entrepreneurs and Investors Made Compelling Connections at RESI 3

By Nono Hu, Senior Manager, Branding & Messaging, LSN

Nono 2Life Science Nation (LSN) is proud to release the RESI 2014 fall video, which captures the happenings and buzz from the third Redefining Early Stage Investments (RESI) Conference at Fenway Park. LSN is pleased that RESI provided scientist-entrepreneurs and investors with an opportunity to have a compelling dialogue that will lead to relationships and hopefully future capital allocations.

LSN would like to say thank you for coming to RESI, and we hope to see you at our next conference on January 13, 2015, in San Francisco.

Early Stage Therapeutics and Medical-Device Investors Are Often One and the Same

By Michael Quigley, Director of Research, LSN

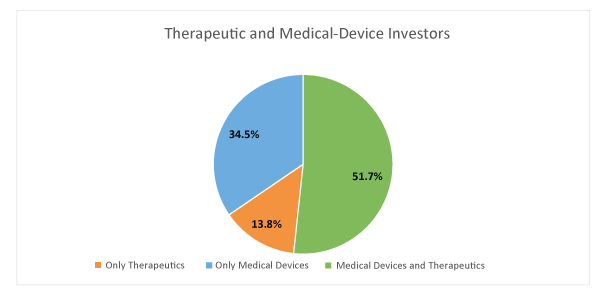
mike-2Developing therapeutics differs in many ways from developing medical devices. Therapeutics tend to have longer paths to commercialization and are more capital intensive, but they also usually deliver larger exit payouts. Interestingly, more investors are currently looking for opportunities in both of these sectors than in only one of them. An analysis of approximately 600 investment mandates gathered by our research team over the past year shows the percentage of investors interested in only medical devices, only therapeutics, or both. (See Figure 1.)

Figure 1
Figure 1

More than 50% of the investors we spoke with are looking to invest at some level in both therapeutics and medical devices. While portfolio blends may vary from investor to investor, with some looking more heavily into devices and vice versa, the bottom line is many investors are looking more opportunistically. They see great potential for ROI in these two spaces, so they leverage their networks and expertise to diversify their portfolios in hopes of capturing the upside in both. Many investors have partners or team members who are focused on therapeutics and medical devices, and other investors have vast networks of experts and industry executives to help them during the vetting process if they are unfamiliar with a particular technology.

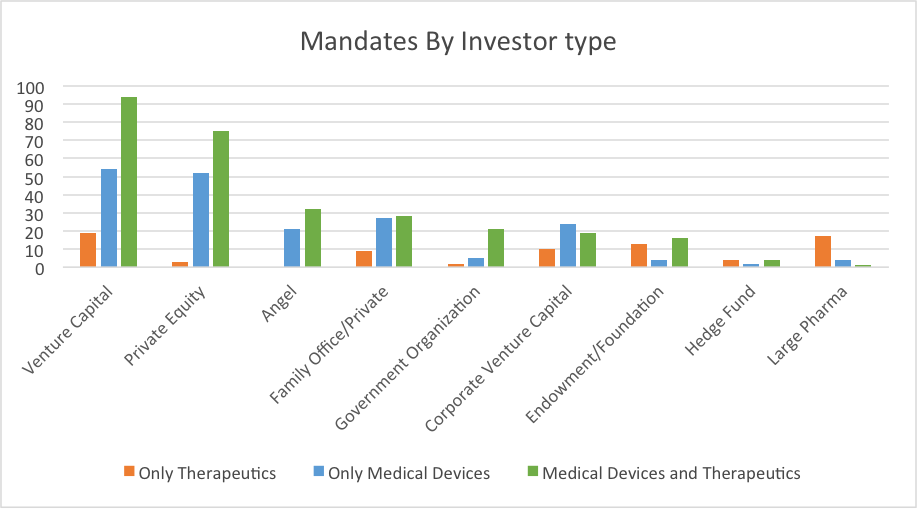
As the therapeutics approval path is a much more capital- and risk-intensive process than that of medical devices it appears logical that more investors are looking only or additionally into the medical device space. It seems that those investors are looking to diversify their portfolios and cover their bets to generate a more positive outcome. We analyzed investment mandates by investor type for only therapeutics, only devices, or both. (See Figure 2.)

Figure 2
Figure 2

It is interesting to compare mandates from the various investor types; the differences could have a number of forces driving them. Private equity groups, for example, tend to look at later-stage opportunities, such as devices that are about to reach commercialization or that have been recently approved and have begun shipping. Therapeutics at this stage, however, tend to be partnered with large pharma or biotech companies to finalize approval and distribution, making those opportunities much rarer. Given their smaller investment size compared with other investors, angel groups look to invest in companies where they can get more significant equity positions, which makes early stage devices a more viable option, compared with therapeutics that are often seeking multimillion dollar seed rounds. The corporate venture capital groups that LSN tracks also tend to favor devices because of the numerous IT and tech-based companies that are now leveraging that expertise to expand into the healthcare sector.

The most important point that can be drawn from this data is that most investors in the space are looking at both therapeutics and medical devices for new investments, and their allocations will be a function of the deals that they are presented with. As a fundraising executive, you are doing a great disservice to your company by not getting in front of investors simply because you believe they don’t invest in medical devices. Although past investment data can tell you a lot about investors, in the rapidly changing life science space, the key is uncovering which areas investors are exploring going forward. Ultimately, investors are most interested in compelling and innovative opportunities with strong teams that solve a significant problem. If you have all three things, the sheer number of high-potential investors may surprise you.