Investors Elucidate Medtech Preferences

By Lucy Parkinson, Research Manager, LSN
lucy 10*10

As highlighted in our look at the Medtech Fundraising Landscape for 2014, LSN Research contacted investors from across the medical device map.  The results show that there are more active investors in the medical device sector than in therapeutics, despite opinion to the contrary.  However, we have seen a marked difference between these two groups of investors – while therapeutic investors are more likely to be focused on early stage companies, medtech investors are distributed more evenly across a company’s lifespan.  The chart below shows the respective distributions of investors among LSN’s mandate data:

4

So when it comes to early stage companies, you may well find there is more interest in therapeutics than in devices.  However at the growth phase, you’ll find many investors taking an interest in more mature medical technology opportunities.  Many investors are only looking for companies with substantial revenues, but some we’ve spoken with also look at commercialization-stage opportunities; that is, devices that have regulatory approval and need investment to scale their manufacturing and marketing.

Here are some of the reasons that investors have given for their interest in later-stage medical device opportunities:

  • “We’ve had success investing in healthcare.”  These investors have previously invested in clinics and healthcare providers, and this familiarity with the marketplace gives them confidence that they can make the right bets in the medical device space.  Some of these investors may never have backed a device company before, but they’re receptive if the bottom line is right. LSN Research hears this perspective from family offices and from healthcare-focused PE funds. 
  • “We don’t have the capacity to invest in drug development.”  These investors are eager to invest in healthcare technologies and they’re prepared to put commercialization capital into a new product, but the capital requirements of late-stage therapeutics are beyond them. Smaller PE funds elucidate this approach.
  • “We know the business, but we don’t have a medical expert on staff.”  These investors have expertise in other relevant sectors (such as niche manufacturing or sales) but they do not feel they can accept scientific or regulatory risks.  They need assurance from a regulator that the product is scientifically sound, but with that taken care of they’re interested in applying their other skills to the early growth of a device company. Experienced generalist PE firms state this angle on the medical device sector.
  • “We’re industry agnostic, but here are our other requirements.”  These generalists are looking for companies that match fixed requirements such as a revenue figure, or a headquarters in the investor’s region.  While they might be willing to invest early, they will want to see evidence that your product has market traction.  They’re willing to consider any industry provided the company’s within their ballpark. Many debt funds that provide financing for medical device companies fit this description, as do many regional PE firms. 

LSN Research consistently found that many growth investors who, on the surface, don’t have a life science focus are in fact open to medical device opportunities.  If you’re looking for funding for a device, you never know who it might be worth speaking to, so cast your net wide.
Investing in the Future: RESI Conference Announces Corporate VC Panel

By Tom Crosby, RESI Conference Manager, LSN

Tom 2

Corporate Venture Capital (CVC) and Independent Venture Capital are two totally separate beasts with different tactics and strategies – especially regarding early stage investments. Learn from the experts in Corporate Venture Capital why there is a growing interest in early stage life science. As CVC funds continue to grow, it is increasingly important for entrepreneurs to understand these entities as a viable source of potential investment.

The RESI Conference session will feature representatives from some major players in the industry. This is a must attend, one-of-a-kind panel that will provide tremendous insight for the scientist entrepreneur.

Moderated by Vikas Goyal of SR One, the audience will hear from:

Panelists will answer the question regarding independent VCs being friend or foe, and how they are different than independent venture capital. The session will also focus on the individual investment preferences of each representative on the panel. What does their portfolio look like today? What is the best way for early stage entrepreneurs to get on their radar screens?

East Meets West: The Lessons Learned

By Laura Chess, Research Analyst, LSN

laura-10-10

If you have just read the “East Meets West: By the Numbers”, I would like to provide some additional commentary from a canvassing perspective.

As a research analyst at LSN, one of the reasons I am able to get through to investors is that the purpose of my call is to find out what an investor’s interests are so that I can provide them with qualified dealflow. I am not trying to sell them something. During Asian night, June 18, I was pleasantly surprised with how open and receptive the investor candidates we canvassed were. My goal was to conduct a one-on-one survey that reveals the needs of investors that I had targeted from the Far East. Upon explaining that LSN can help them source and filter global life science companies that are a fit for their current investment mandates, the call becomes a pretty free-flowing conversation.

Below are the two observations I made that may be of help to the reader when canvassing the Asia Oceania region:

1) Many investors in Asia are open to considering western companies and actively seeking deal flow.

Many investors in the Asia-Pacific region don’t have offices in the U.S., which is sometimes misconstrued as a lack of interest in western-based start-ups. In our conversations, however, many Asian investors said they were open to cold calls, interested in establishing relationships with western biotech and medtech companies, and seeking deal flow. These investors were especially interested in companies looking to expand to Asia.

 2) To make the most of late-night outreach, choose large cities, be organized, and add a sense of urgency.

If you have the ability to reach out internationally, choose large cities, such as Hong Kong or Beijing, where investors are well versed in English. Sort the list of investors by time zone, with start times for each. And in the weeks leading up to your outreach, consider contacting investors by email to let them know the date and time when you will call. Taking such steps will help you achieve your primary goal: making as many calls as possible.

Your Target List: Who Is Not Investing

By Michael Quigley, Director of Research, LSN

mike-2

As a fundraising entrepreneur, knowing who is actively investing and who is not has the potential to increase the efficiency of your campaign by 30%, if not more.

Who is “not currently allocating” is one of the most valuable data points that we gather on the life science investment community. In this category we put any investor who has made investments in the space over the past five years and is in the process of fundraising, winding down a fund, or moving out of the space completely. Of the investors we have spoken to over the past year, we have found that approximately 30% are not currently looking to make new investments.

Why is this important? Because investors who aren’t allocating tend to be the slowest to respond to emails and voicemails, which can mean weeks—if not months—of wasted effort, as you try again and again to reach investors that are not seeking opportunities.

When we analyzed our data further, things got even more interesting. Of the investors we have spoken with who are not currently allocating, two-thirds are VCs; of the investors who are allocating, only one-third are VCs. This demonstrates a point we have discussed in this newsletter before: a large number of previously active life science VC investors are now raising their own funds, winding down, or phasing out of the life science sector.

The bottom line is that by knowing who is not actively allocating, you can identify all the players in your space who are seeking opportunities and substantially increase the efficiency and likelihood of successfully raising capital.  Too often fundraising executives use a shotgun approach, reaching out and trying to touch everyone who may or may not be investing in their space. This tactic creates a lot of needless noise and wasted time for both parties. A little extra knowledge regarding the current state of the targeted investor can go a long way toward making a fundraising executive much more productive in seeking capital.

The Life Science Executive’s Fundraising Manifesto: Why I Wrote This Book

By Dennis Ford, Founder & CEO, LSN

If you are a life science entrepreneur who has reached the exciting phase of development when you are actively seeking investors in your firm and product, congratulations! Growing a company to this stage is not an easy process, and although attracting funding isn’t either, if you take the right approach, winning an allocation can become not only an achievable milestone but also a feat you accomplish repeatedly…

Click here to read the entire book introduction


book-signing

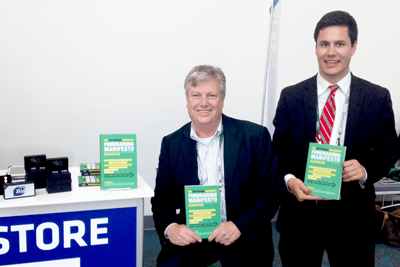
Author, Dennis Ford, and Contributor, Alejandro Zamorano
Book Signing at 2014 BIO International Convention

Heading Upstream & Investing at the Source: RESI Conference Announces Big Pharma Panel

By Tom Crosby, RESI Conference Manager, LSN

Tom 2

Don’t miss an excellent chance to hear directly from pharma executives looking to fill pipeline gaps via strategic partnerships & alliances; LSN is bringing together representatives from some of the most active big pharma companies involved in early stage life sciences.

Moderated by Bill Kohlbrenner of AbbVie, the audience will hear from:

Panelists will discuss in-depth the key motivators behind big pharma’s shift towards an early stage strategy as a way to fill the gaps in their pipelines. What indication areas are the most sought after? How does an early stage entrepreneur interface with business development executives from pharmaceutical companies? LSN’s Big Pharma RESI Panelists will shed light on these questions and more.

Hear from big pharma executives as they explain how they engage with early stage startups, and how they like to be contacted. The speakers will help the audience understand their timeline for contact, and give advice on how to create a dialogue that leads to a relationship and an eventual alliance. If you need to understand the timeframe and limitations of how big pharma corporate works, this expert session is crucial for you to attend.

RESI3


LSN Business Development Corner: Assessing Your Fundraising Acumen

By Jack Fuller, Business Development, LSN

Jack 2

The perfect fit, the good fit, and the stretcher. Those are the three types of scientist-entrepreneurs I’ve seen do well in their fundraising efforts.

Day in and day out, LSN works with life science companies that are raising capital, and we see an enormous number of talented and intelligent people who cannot conceptualize and execute an outbound fundraising campaign. For one reason or another, otherwise smart people are not able to determine who to approach for capital or discuss their ideas and technology in a clear and convincing manner.

However, some scientist-entrepreneurs are a perfect fit or a good fit for successfully running an outbound fundraising campaign, and some can stretch and make it happen.

The Perfect Fit

This is someone who has built a team to support the fundraising process. The perfect fit realizes the importance of continually updating a contact database with the latest relevant players. He or she understands that professional marketing materials are critical. And he or she is able and willing to do whatever is necessary to secure the future of the company. With little assistance, the perfect fit can take a list of qualified investors and have meaningful dialogues that eventually lead to allocations.

The Good Fit

This usually is a person who is dedicated to fundraising. The good fit has contacts in the industry, is not afraid to pick up the phone and call a stranger, and has run a meeting with potential investors. Still, despite his or her experience, this individual often has difficulty branding the company and technology, crafting a message, and presenting not only a compelling narrative to investors but also one that’s clear so investors can determine quickly if there is a fit with their investment criteria. Because of his or her experience, however, the good fit recognizes what’s missing and can get up to speed quickly.

The Stretcher

This is often a former scientist who had a great idea, which launched a company. Then, he or she wants to get to the next level and realizes that raising money from investors is different from asking friends and family. The stretcher often needs help with fundamental sales and marketing tactics, overhauling the investor materials, and tackling list and task management. Because this individual has an uncommon desire to learn and do whatever is necessary—to stretch—he or she can become a successful fundraiser.

Which one are you?