Call for Innovation: RESI Conference Presentation Applications Now Open, San Francisco, January 13, 2015

By Tom Crosby, RESI Conference Manager, LSN

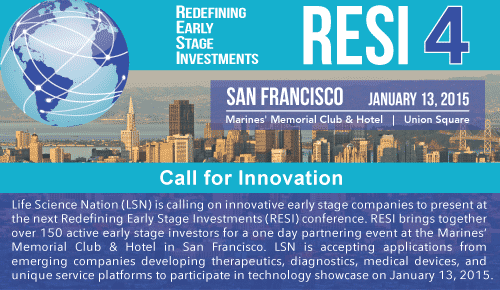
Tom 2As LSN prepares to bring the next Redefining Early Stage Investments Conference to San Francisco, we are proud to announce that emerging biotech and medical device companies are now invited to apply to showcase their technologies at the event. Over the course of the next two months, thirty innovative companies will be selected from the pool of applications for a highly sought-after presentation space during the week of the 33rd annual JP Morgan Healthcare Conference.

For its last two Boston events, RESI has employed a re-envisioned presentation model, called the RESI Innovation Challenge; rather than have CEOs pitch during a randomly allocated 10-15 minute time slot, RESI gives presenting executives a space in the exhibition hall for the full day of the conference. Typically, selected companies will use this space to present their executive summary or recent trial data on large poster boards spread throughout the hall. LSN has found that this model increases the number and frequency of investor interactions for presenting companies throughout the course of the day.

To add some friendly competition to the atmosphere of the conference, the RESI Innovation Challenge also invites all attendees to participate in a virtual investment contest between the 30 companies. At the start of the day, each attendee receives RESI Cash to allocate to the entrepreneurs whose technologies they find most influential. When all is said and done, the company receiving the most investor dollars is named the winner. In March, it was the Newton, MA-based Empiriko; September’s event crowned Boston’s ORIG3N. Who will take the top prize at RESI San Francisco? Apply to present now — it could be you!

Innovator-RESI-4-banner

Hot Life Science Investor Mandate 1: Family Office Seeking Digital Health and Novel Therapeutic Opportunities

A private investment firm funded by a single LP based in the Western United States invests in seed and early-stage health technology companies. The typical investment size for seed investment ranges from $250K to $1M (usually in equity or convertible notes). For early-stage companies, the firm typically co-invests with other VC firms in Series A and B financing and the investment size will depend on the company’s financial needs. The firm is geographically agnostic but prefers start-ups to be based on the West Coast. The firm is actively seeking new investment opportunities.

The firm has a focus on the digital health and informatics space, but also invests in novel therapeutics. Generally, the firm focuses on opportunities that avoid or mitigate FDA regulatory risks. The firm is agnostic in terms of subsectors and indications, but does not consider orphan indications. The firm will only consider technologies with proof of concept. Historically, the firm has invested in therapeutics that address oncology, infectious diseases, cardiovascular, and metabolic disorders; drug delivery; orthopedic devices; genomics.

The firm prefers to take a board seat but is generally flexible.

If you are interested in more information about this investor and other investors tracked by LSN, please email mandates@lifesciencenation.com

Hot Life Science Investor Mandate 2: Angel Group Seeking Therapeutics Devices and Diagnostics

An angel group is made up healthcare professionals is seeking to invest in technologies that significantly advance the standard of care. The group considers companies at a range of stages and is geographically agnostic. Since the members are investing their own capital, the investment size and capital structure are highly flexible. The group is actively seeking new investment opportunities, and is open to leading financing rounds.

The group is interested in therapeutics, diagnostics, and medical devices. While the group will consider most any indication and technology type, the group currently has a particular interest in cell therapy and in the oncology sector. In general, the group is not interested in dermatology. The group will only consider products that have shown human clinical efficacy; in the case of therapeutics, the group generally looks at phase II companies but if a company has obtained human efficacy data in phase I, the group would consider the opportunity. 

The group invests in both private and public companies. The group performs deep scientific due diligence on all the opportunities that the group takes part in, often conducted by the group’s members.

If you are interested in more information about this investor and other investors tracked by LSN, please email mandates@lifesciencenation.com

Hot Life Science Investor Mandate 3: Corporate Venture Arm of Japanese Biotech Seeking Investments in Europe and US

The corporate investment arm of a Japanese biotechnology company primarily makes early stage investments solely in the Life Sciences. The firm recently raised a new fund in March 2014 and looks to make about 2-3 new investments in the next 12 months. The firm typically allocates USD 1-2 million per round and up to USD 3 million per company. The firm can invest globally, with particular interests in the USA and Europe. The firm is actively seeking new investment opportunities.

The firm seeks to invest in therapeutics, in-vitro diagnostic devices, medical devices and drug discovery platforms. For therapeutics, the firm looks for small molecules, biologics, as well as biosimilars and reformulated drugs. The firm is opportunistic in terms of indications and is particularly interested in orphan indications. The firm will consider products in all stages of development. However, the firm typically invests in products that are in pre-clinical and early-clinical. For medical devices, the firm is also opportunistic in terms of indications; however the firm is only interested in devices with a therapeutic focus.   

The firm will only co-invest with other investors in opportunities outside of Japan. For that reason, the firm prefers opportunities with a syndicate in place. The firm typically requests board observation rights in its portfolio companies.

If you are interested in more information about this investor and other investors tracked by LSN, please email mandates@lifesciencenation.com

Successful Life Science Entrepreneurs Tell Their Tales from the Road

By Nono Hu, Senior Manager, Branding & Messaging, LSN

Nono 2At the third Redefining Early Stage Investments (RESI) Conference, LSN brought together successful life science entrepreneurs who were at various stages of their fundraising campaigns and asked them to share their experiences. The panel discussed what the early stage fundraising process was like for them and how others can build an outbound marketing campaign to raise money.

The panelists shared their insights on fundraising through the 4s framework: sourcing, screening, segmenting, and selling. Click on the video link below to hear the views of scientist-entrepreneurs in the life science industry.


Moderator:

Rick Berenson, CEO, Thermalin Diabetes

Panelists:

Barbara Fox, CEO, Avaxia Biologics

Fred Colen, President & CEO, BeneChill

Richard Gauthier, Head of Business Development, Microbiotix

Gabor Bethlendy, CCO & Founder, Parabase Genomics

Michael Tippie, CEO, TomegaVax


Who’s Fueling the Health Information Technology Investment Boom?

By Shaoyu Chang, Research Analyst, LSN

Shaoyu 10*10Health information technology (HIT) refers to a broad spectrum of technologies, ranging from personal health-monitoring applications to big data analytics. The venture capital firm Rock Health recently reported that venture capital funding in the HIT field reached $3 billion for 2014, well surpassing the $1.9 billion invested in the sector during 2013.[1] The LSN research team tracks investors in early stage life sciences, and we have noticed a growing interest in HIT as well.

The reason for increased interest is twofold. First, large IT corporations are diversifying their product lines and gaining exposure to the growing healthcare sector. Wireless implantable medical devices that enable remote monitoring of patients’ vital signs, smart bracelets that track an individual’s physical activity level, and algorithms that interpret genomic data are just some of the new products that corporations are hoping will reinvent how we look at healthcare. Corporate venture capital firms, such as Google Ventures and Verizon Ventures, are leveraging their expertise in electronic hardware, software, and wireless communication in order to tap into the growing number of relevant healthcare opportunities in these areas.

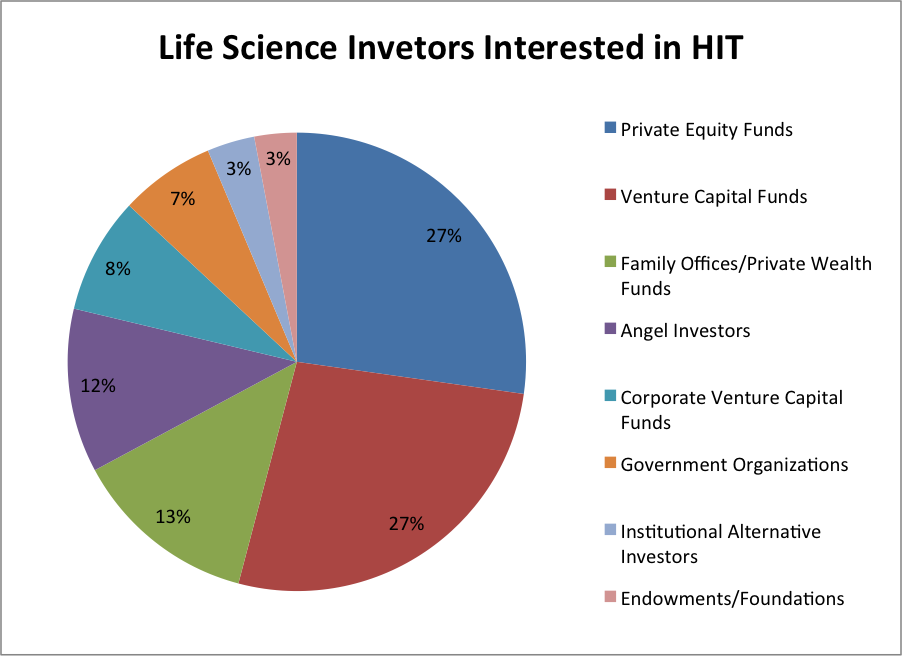
Second, traditional life science investors are being attracted to the HIT sector because of the lower risk, shorter development period, and rapid growth potential when compared with the traditional medical-device and pharmaceutical sectors. These investors are leveraging their life science expertise to capitalize on these opportunities when they can identify and comprehend the unmet needs these opportunities are solving. Of the hundreds of investors we interviewed, 88% of medical-device investors are either investing or seeking to invest in HIT, and 60% of biopharmaceutical therapeutic investors are doing so as well. Exhibit 1 shows the total composition of life science investors interested in HIT, as interviewed by the LSN team.

Exhibit 1
Exhibit 1

Investors’ enthusiasm is also supported in part by a favorable regulatory environment. The Affordable Care Act provides financial incentives for healthcare providers to use electronic medical records and make meaningful use of HIT systems.[2] Furthermore, in the eyes of regulatory authorities, HIT products differ significantly from medical devices and therapeutics in terms of risk profile. In its 2013 final guidance, the U.S. Food and Drug Administration made clear that it will take a hands-off approach on low-risk HIT technologies, making this field much more attractive to risk-adverse investors.[3]


[1] Rock Health, Q3 funding update: Digital health rakes in $3B, October 2014, accessible from http://rockhealth.com/2014/10/q3-funding-update-digital-health-rakes-3b/.

[2] U.S. Department of Health and Human Services, New Affordable Care Act tools and payment models deliver $372 million in savings, improve care, September 2014, accessible from http://www.hhs.gov/news/press/2014pres/09/20140916a.html.

[3] U.S. Food and Drug Administration, Mobile Medical Applications: Guidance for Industry and Food and Drug Administration Staff, September 2013, accessible from http://www.fda.gov/downloads/MedicalDevices/DeviceRegulationandGuidance/GuidanceDocuments/UCM263366.pdf.


Screening Potential Life Science Investors

By Michael Quigley, Director of Research, LSN
mike-2Last week, we discussed some of the tactics and tips used by the LSN research team to identify potential investors in the life science space. Identification is a multistep process, however. After you have a created list of potential investors from your personal network, the conferences you’ve attended, the databases and websites that report on financing rounds, and LinkedIn, for example, you need to go through the names one by one to determine who is worth contacting given your particular opportunity. There are several criteria that potential investors should meet to make it into your pipeline.

They Should Be an Investor

This may sound obvious, however, it is important to consider. Many companies with names like ABC Ventures or XYZ Capital may seem as though they are investors when in reality they are consultants, service providers, and investment banks—none of which allocate capital. Spending time contacting these companies for an investment is not worthwhile, as they will look to offer you their services, not capital.

They Should Be Actively Deploying Capital

Many investors in the space have elaborate websites and massive portfolios, however, they do not currently have capital to invest. To determine if investors are active, the first data point you should look for is when they closed their most recent fund. The term closed signifies the end of the fundraising period for a fund and the start of the investment period. Funds that have closed recently (within one to two years) are ideal, as they still have significant cash reserves and can hold new investments for a longer period. Generally, any fund that is six years old or older will be making investments only into existing portfolio companies or companies from which they can exit relatively quickly, which makes them less than ideal targets. If fund information is not available, then you should look to previous investments to see how recently they allocated. If they haven’t made a new investment in more than a year, then more than likely they will not be a good fit. It is important to note that not all investors make their investments known, so it may take some digging to uncover previous investments—if they are online at all.

They Should Be a Good Fit for Your Opportunity

Determining if an investor might have interest in your type of technology and its stage of development can take a significant amount of up-front time, but it will save you from wasting hours down the road. Even with referrals, it is important to understand if you fit the mandate of the investor, otherwise the meeting will likely yield nothing. There are a number of factors to consider, and the first place to look is the investor’s website. Some investors clearly spell out their investment parameters, including indications, stages, and regions of interests, as well as current and past portfolio companies. Other investors, often hedge funds and family offices, provide virtually none of this information on their websites. In cases where such information is not readily available on the website, it is best to check various news sources for reported financings rounds in which that investor was involved. You should compare your opportunity to the deals the investor has previously participated in. Look at the size of the round, the country, the type of technology, the stage of development, and the target indication.

These are all factors to consider when screening potential investors. If an investor isn’t a fit with your opportunity, it is not worth your time to reach out. If an investor has invested in your type of technology but at a later stage, it is worth presenting your opportunity and getting on the radar for when you are looking to raise further financing. However, if an investor fits all your criteria and is active, you have found a strong lead for your campaign.