RESI @ TMCx Biotech Angels Panel Announcement

By Natasha Eldridge, Marketing Manager, Life Science Nation

natashaAngel investment often acts as springboard, supplying the capital required for life science companies to generate the data necessary to garner interest and secure funding from larger institutional players. This critical pool of capital should be on the radar for every fundraising entrepreneur in the space. In order to help Resi attendees in the biotech space better understand how to go about building relationship and securing an allocation from these groups LSN has assembles a panel of 5 representative from angel group with interest in the biotech therapeutics space. With representatives from groups based Texas, California, Pennsylvania, and Nova Scotia this panel is sure to bring some unique and diverse perspective on angel investment in the space.

Moderated by Bril Flint, Board Member, Central Texas Angel Network the audience will hear from:

Bernard Rudnick, Founding Member, Mid Atlantic Bio Angels

Brian Lowe, Co-Founder & Director, First Angel Network Association

Daryl Basham, Member, Houston Angel Network

Michael Jin, Managing Partner, TEEC Angel Fund

This session will help scientist entrepreneurs understand the perspective of an angel. Angels will explain their investment preferences, and those of their respective syndicates. What types of deals are most attractive to angels? How does an angel group filter, evaluate and parse the plethora of deals that surface? What do angels look for in the initial correspondence? If you are considering angel capital to help move your technology forward, you’re not going to want to miss this panel of experts.

eb


Six Takeaways from Women In Bio Shark Tank

By Lucy Parkinson, Senior Research Manager, LSN

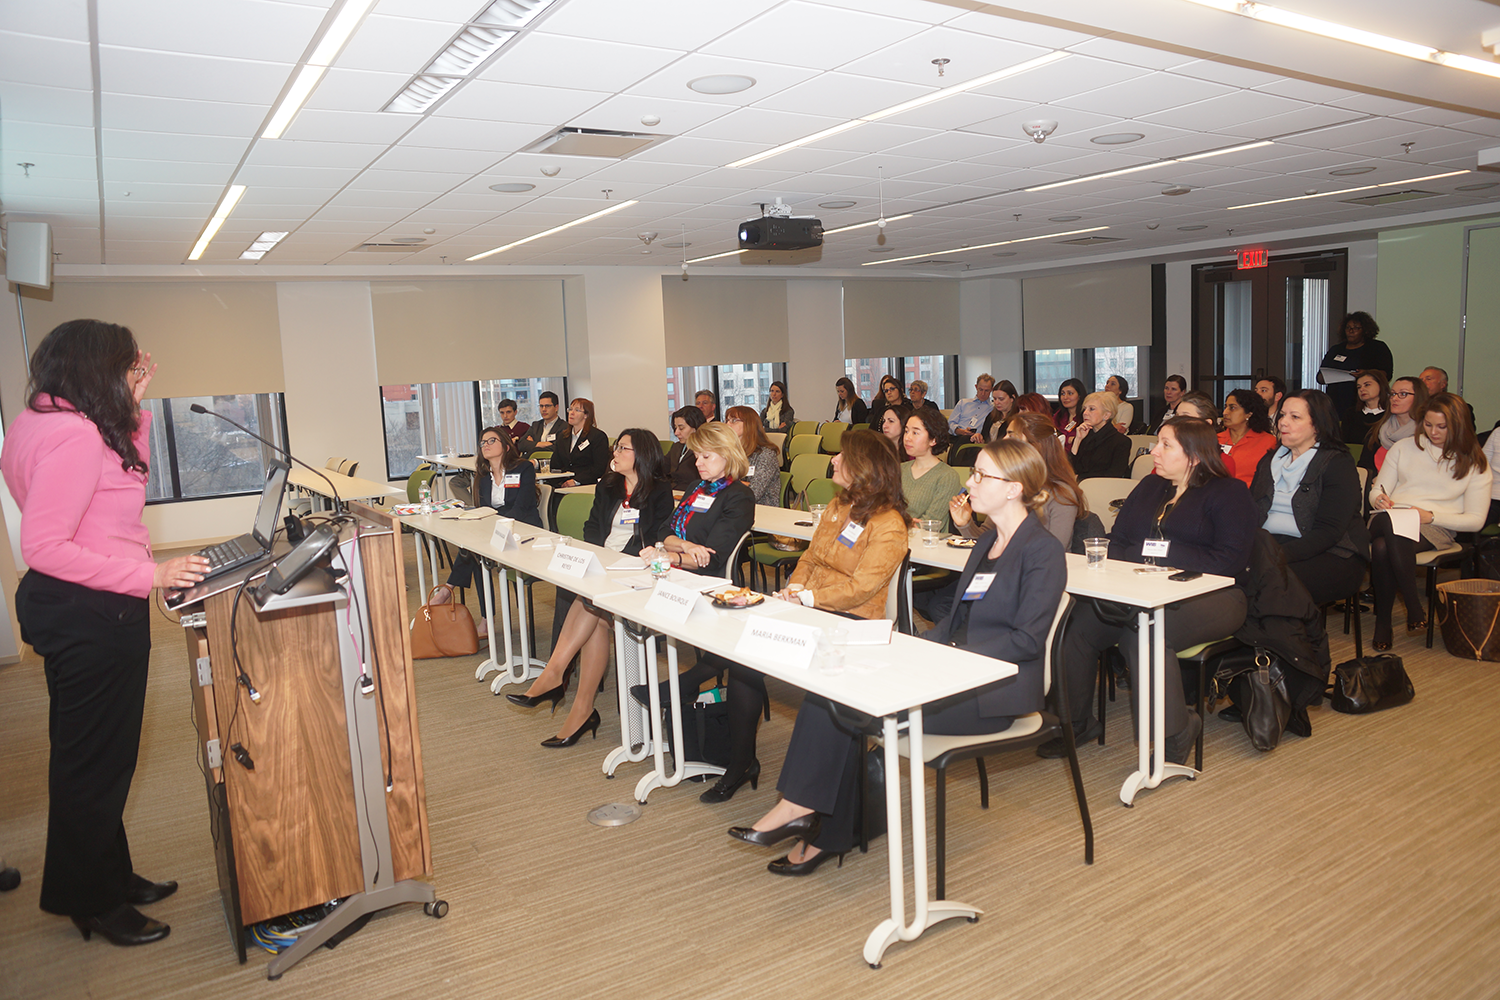
lucy 10*10Last night in Cambridge, LSN joined Women In Bio for a Shark Tank-style pitch event. The audience heard pitches from five life science entrepreneurs. Across the table from them were four experienced early stage life science investors playing the role of “sharks”.

So what did we learn from these life science innovators and from the sharks’ cutting responses to their pitches?

DSC02886wp
WIB Shark Tank Event | March 24, 2015


  1. Where women’s health meets personalized healthcare, there are significant unmet needs that startups can target.

Personalized medicine was a significant theme of the event, and three of our innovators are targeting major problems in the current standard of care for women’s cancers. By using biomarker diagnostics, personalized monitoring devices, and nanotech drug delivery mechanisms, these entrepreneurs hope to offer earlier detection, personalized treatment options, and targeted treatment to women with ovarian and breast cancer.

  1. Investors want to know how science is guiding a business.

While it’s important to deliver a business pitch, not an academic pitch, investors want explanations of how a company’s plan is backed up by research. How did the scientific research help you choose your lead asset, or your target indication? Has your research been published or patented?

  1. While personalized medicine could revolutionize healthcare, the public first needs to be educated about the technology.

As one entrepreneur explained, a company providing a new personalized health product or service is entering a nascent marketplace, and will have to educate consumers on the benefits of adopting the new technology. Any product in this field requires a marketing plan that includes education and awareness, not just a traditional sales approach, and investors may be wary due to the difficulty of developing this new marketplace.

  1. Data is central to personalized healthcare, so companies must take data science seriously.

The sharks pointed out a number of potential pitfalls for companies that are collecting and using personal health data. A startup has to demonstrate that they have the in-house expertise not only to use this data, but also to provide it to the user and to protect it adequately from unauthorized access. The ability to share data with physicians is another vital element of a data-driven healthcare product. Many startups in personalized healthcare are also considering how best to monetize their data; there is a high level of interest in partnering with pharma companies to provide data for research purposes, but it is vital to obtain full consent from patients before considering this path.

  1. New healthcare technologies have to work with physicians.

As the sharks pointed out, no physician is going to order a biomarker test unless that physician is familiar with the biomarker and believes in the information it provides. Similarly, no physician will pay attention to the data generated by a personal monitoring device unless he or she trusts that the device is producing valid and medically actionable information. In the case of diagnostics that directly affect treatment decisions, such as a test to guide breast cancer treatment, physicians may be very concerned about false positives and false negatives; it’s important that physicians know what companies have done to reduce this possibility, and how a patient may be affected by a false result.

  1. The ask is important. It has to be clear, and it has to be reasonable.

The sharks noted that this can be a difficult part of the pitch to get right, perhaps particularly for women entrepreneurs, who can often receive a negative response in the workplace when they initiate financial negotiations. However, the ask is a vital component of a pitch to investors. Investors need to know how much a company is raising, and where that money is going to take them. A sum that is out of line with expectations will raise a red flag. To help you estimate accurately, look at financing rounds for similar companies, and get a sense of the real costs of advancing an asset; if you plan to advance two lead candidates into the clinic, be realistic about the expense of moving two programs through an IND.

Four Reasons Why It Is Never Too Early to Build Relationships with Investors

By Michael Quigley, Director of Research, LSN

mike-2Entrepreneurs we work with often ask us when they should start contacting investment firms. Almost invariably, our answer is as soon as possible. That doesn’t mean a company should feel rushed into sending out unfinished, sloppy, or overly cumbersome marketing materials. You should take the time to organize your brand, from logo to tagline to pitch deck and executive summary, so that you have a professional and concise package. Any upcoming data or potential partnerships or collaborations can be easily added into the materials as they come into fruition.

If a company is waiting for an event or to receive certain data before formally fundraising, outreach can be framed as an introduction to the company, rather than a direct solicitation for funds. In this case the purpose is simply to begin a relationship. As always when reaching out to investors, it is crucial that you contact people who have interest in your sector and technology, otherwise they are unlikely to be willing to engage in even an introductory conversation or be able to help you when you are formally seeking capital. Building investor relationships early allows companies to:

  1. Establish a Communication Channel

At the very least, this practice gives companies the opportunity to cultivate an investor contact who knows who they are and what they are doing, and who will be significantly more responsive and upfront with feedback when the company formally starts to raise capital. This is the first step in developing any investor relationship, and gives fundraisers a head start on their process no matter where the company is in their development.

  1. Demonstrate Growth/Progress

Reaching out and explaining a plan and future company goals and milestones gives an entrepreneur the opportunity to show potential investors progress and growth over time. This will increase their faith in your ability to manage the product, making the company a more worthy potential investment. Investors aren’t investing in a snapshot of a company at a given date and time; they are investing in the entire lifeline of development. By providing them with a real-time window into that process, you help make the picture more clear and understandable.

  1. Build Trust

Trust is crucial in any relationship, especially when it involves financial capital. By speaking periodically, demonstrating growth, and, perhaps most significantly, explaining any hiccups that led to missed milestones or forecasts and what was learned from them, an entrepreneur can forge a strong bond with an investor. This level of trust can be invaluable, particularly when a company begins looking to secure a lead investor.

  1. Create Pipeline for Future Rounds

Early stage entrepreneurs in the life science field will almost inevitably have to raise multiple rounds of financing, and there is also a good chance that each round will include different investors. By building relationships early with investors allocated at various stages, you can decrease not only the time required to raise your first round of financing, but also that of your future rounds. Having seen a company grow over a few years further strengthens the bond and level of trust an investor feels with that startup.

Waiting until you have limited runway in terms of capital on hand can be a death sentence for an early stage company. Since the average fundraising campaign takes between 9 and 18 months, entrepreneurs must do all they can to streamline and advance the process as early as possible. It is often apparent to investors when a company is running out of cash and time, and that can negatively affect their valuation. Over the years we at LSN have seen a number of companies fall into this trap, and you do not want to join that club. Get your materials together, identify targets, and start reaching out, getting feedback, and building relationships. You will be glad that you did.

RESI @ TMCx Cardiology Investors Panel Announcement

By Nono Hu, Senior Manager, Branding & Messaging, LSN

Nono 2The cardiovascular sector presents unique challenges both to entrepreneurs and investors.  The steep cost of Phase III trials and the strict regulatory standards applied to cardio drugs make investing in cardiovascular products a risky endeavour.  Investors who dare to take on this field are rewarded with access to large markets, including a growing need for new cardio solutions in emerging economies.  In addition to investors who take on cardio for the potential ROI, nonprofit funders see the potential for their dollars to make a significant global impact by backing early-stage companies.

For RESI @ TMCx, LSN has assembled a panel of veteran investors who are focused on meeting these challenges, Moderated by William Kohlbrenner, Consulting Scientist, Boston Innovation Capital & Scientist-in-Residence, Life Science Nation the audience will hear from:

These investors will explain how they assess cardiovascular investment opportunities, what cardio entrepreneurs can do to differentiate themselves when seeking investment, and how to find investors who are interested in working with you in matters of the heart.

ncc

RESI @ TMCx Medtech Angels Panel Announcement

By Michael Quigley, Director of Research, LSN

mike-2

Angels represent an extremely important pool of capital for a fundraising entrepreneur, especially since they have been increasingly syndicating and participating in larger financing rounds. To help entrepreneurs with a medical device or technology better understand how to receive an allocation from an angel, LSN has assembled a panel of angel investors with specific interested in medical technology.

Moderated by Richard Koffler, Member, Tech Coast Angels, the audience will hear from:

This session will help scientist entrepreneurs understand the perspective of an angel. Angels will explain their investment preferences, and those of their respective syndicates. What types of deals are most attractive to angels? How does an angel group filter, evaluate and parse the plethora of deals that surface? What do angels look for in the initial correspondence?

Other topics of discussion will include their criteria for management team, stage of technology, and whether there is a preference for regional or global firms. What is the difference in presenting to an angel group versus a traditional one-on-one investor meeting — and how does the vetting process work? If you’re looking for angel capital to move your technology forward, don’t miss this session of expert insight at RESI.

QQ图片20150318172405

The Shape of A Biotech Pipeline

By Lucy Parkinson, Senior Research Manager, LSN

lucy 10*10In our recent explorations of the life science innovation landscape in various areas of the U.S., we’ve looked at how different regions shape up in terms of pipeline assets, key indication areas, and the kind of investors active in each region. One metric in which we saw substantial distinctions is where assets fall in the pipeline. Not every area with an abundance of preclinical assets also has a large amount of Phase III assets that may become marketed products in the near future.

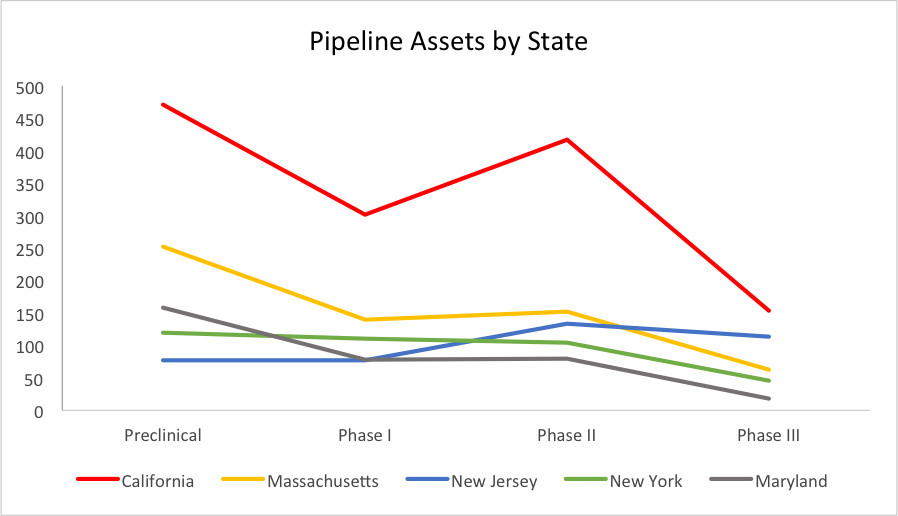
The LSN Company Platform tracks over 30,000 life science companies globally.  From this data, we took a sample of the asset distribution in five states with substantial biotech pipelines: California, Massachusetts, New York, New Jersey, and Maryland (see Figure 1). This data reveals patterns that challenge key assumptions about what a regional biotech pipeline looks like.

f1
Figure 1 | Source: LSN Company Platform, Data as of March 18, 2015

It’s natural to assume that a state that generates many preclinical assets, perhaps from a base of universities and research hospitals, will see these assets gradually winnowed through the trial process, with a certain proportion failing to progress at each stage of development. What we find is somewhat different, with diverse pathways occurring across the range of biotech hubs. In California, Massachusetts, and Maryland, we see a major drop-off after the preclinical stage of development, perhaps due to assets failing in animal trials. We don’t see this in New York and New Jersey; these states have fewer preclinical assets than the other states sampled, but healthy late stage pipelines. It’s been noted that the New York area may be a difficult place to found a biotech start-up due to factors such as high expenses and a lack of lab space in the region. However, a more established biotech company that has developed or in-licensed clinical-stage assets might have gathered the resources to thrive in this area.

The states sampled all show either a similar number of Phase I and Phase II assets, or a markedly greater number of Phase II assets. Of course, many assets undergo combined Phase I/II trials (particularly in the cancer field, which is the largest area of life science innovation in the U.S.), testing both toxicity and efficacy in their first-in-human trials. We mark these assets as being in Phase II. California, Massachusetts, and New Jersey all show an uptick in Phase II. Many small companies look for a larger partner at the Phase II stage, and these three states are all host to large pharma companies.

Another way to consider the pipeline is to ask how many preclinical, Phase I, and Phase II assets there are in each state for every asset that reaches Phase III. While in New Jersey (as previously observed) we track more Phase III assets than early stage assets, the state is a true outlier in this regard. Massachusetts, with its deep bench of early stage biotech companies, has over four preclinical assets for every asset that reaches Phase III. Maryland has a very steep pipeline funnel, with almost nine preclinical assets for every Phase III asset.

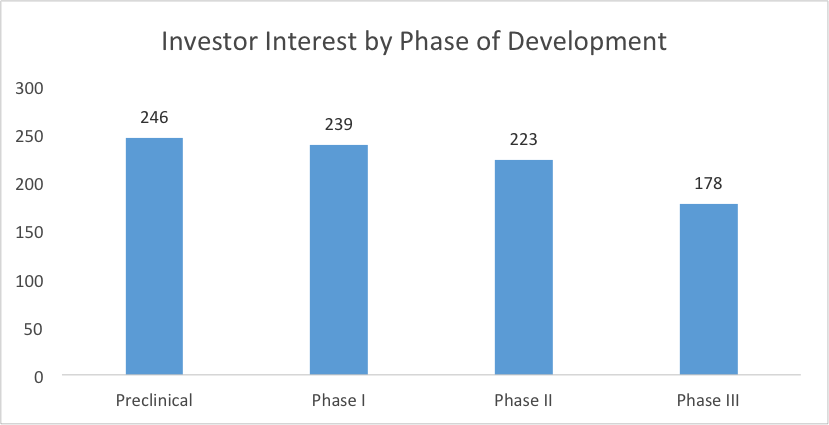
From a look into the LSN Investor Platform, we find that investors are interested in companies at every stage of the pipeline. The following figure (Figure 2) shows investors interviewed by LSN who have stated an interest in therapeutics under development in the U.S.:

f2
Figure 2 | Source: LSN Investor Platform, Data as of March 18, 2015

America’s many life science hubs have strikingly different profiles, and emerging regions without a large pharma presence might nevertheless sustain a thriving early stage biotech landscape. Early stage companies must work hard to find the investments that will keep their assets moving toward the marketplace. It’s notable that only two-thirds of investors interested in U.S. biotech companies are based within the country; the search for capital might extend globally, far from the local biotech hub where an asset began.

The Magnificent Seven-Fundraising Challenges Facing Life Science Entrepreneurs

By Dennis Ford, Founder & CEO, LSN
Dennis bookEntrepreneurs in the life science space face a myriad of challenges on the commercialization journey including fundraising. While the current open IPO window has certainly shed positive light on the sector, early stage life science companies are still facing an uphill climb when it comes to fundraising. There is simply a limited amount of capital available to fund a burgeoning number of products, ideas, and solutions that can no longer be supported by government or academic sources. However, the supply and demand of capital is not the only hindrance to an early stage life science company; below are seven fundraising pitfalls that we hear about on a daily basis in our dialogues with investors and entrepreneurs.

  1. Contributing to “White Noise”

An investor’s inbox is often bombarded with messages describing the latest and greatest opportunities; however, more often than not, these opportunities are outside of that investor’s wheelhouse.  You need to match your company to an investor’s current mandate. There are simply not enough hours in the day for an investor to read, let alone respond to, all of these messages, and as a result, many go unnoticed or do not receive an adequate review. While there are those investors who do not specify their investment interests, fundraisers in the entrepreneurial community can remedy this problem by taking the time to properly research and qualify the investors to whom they are reaching out.  Make sure when you go after an investor you know it is a fit for your company’s sector and stage of development.

  1. Lacking A Clear, Concise Message

Having a clear and concise message can significantly improve your odds of standing out amid the “white noise.” When your opportunity can be understood quickly, investors can more easily identify whether it is something to which they should allocate more time for review. Unfortunately this is not something widely accepted by many scientist-entrepreneurs, who insist on sending reams of data prior to establishing any initial interest. This not only impedes their ability to initiate contact, but it also adds to the overall problem by clogging the communication. It’s imperative to develop an ongoing dialogue with investors that are a fit. It works and makes both parties more efficient.

  1. Misunderstanding the Time, Effort, and Capital Required to Fundraise Successfully

At LSN we begin conversations with entrepreneurs with three basic questions: “Are you fundraising?” “Do you know how long it will take?” and “Do you know how much it will cost?” We do this to determine how savvy the entrepreneur is regarding raising capital. LSN staff need to gauge how well prepared a fundraising CEO is for what lies ahead. In our experience an average campaign can take anywhere from 9 to 18 months and can cost anywhere from $60,000 to $100,000, when you factor in expenses such as those associated with being on the road and the development of marketing collateral and a website, it adds up.  Understanding the time and cost commitment required is crucial in determining when you need to start your campaign. Additionally, if you are raising money to stay alive, as many in this space are, you want to make sure you have enough cash reserves to last until you can lock down an allocation.

  1. The Myriad of Third Party Capital Raising Entities that Overpromise and Under Deliver

Many entrepreneurs who lack the time or skills necessary to run a campaign on their own hire third party groups or individuals to fundraise on their behalf. At LSN we have heard countless stories of groups that promise access to a vast global network of investors, which, in reality, often consists of just a few personal contacts along with a number of investors that may not be investing in companies that match your profile. These third parties don’t often take the time to maintain the list of investors on their networks to determine who is active and what they are really looking for. This “not-being-in-synch” often leads to “mercy meetings,” which ultimately go nowhere since they are based only on a favor and not on fit. The importance of an accurate, up-to-date list of targets cannot be underestimated when fundraising. Entrepreneurs that come to LSN also report a lack of transparency from these groups regarding who they are communicating with about the opportunity and what feedback they are receiving. When considering a third party for assistance with your fundraising, it is vital to receive a valid reference from a company in your space who has worked with them in the past. At LSN we keep track of everything on SalesForce.com and our clients can log in 24/7 and see which investors have been called, when they were contacted and which staff member is responsible for following up. Additionally, the client can read all the notes from the conversation and review any action items.

  1. Not Having a Plan B

When going into due diligence and later stage conversations with potential investors or partners, countless entrepreneurs fall into the trap of becoming so confident in the likelihood of investment that they cease to continue reaching out to other groups. This path is dangerous for a number of reasons. First, despite every positive conversation, until the money is in the bank, there is always a significant chance that the investor will not make an allocation. If you put all your faith in one investor who leads you on for months while you halt other fundraising activities, you will lose valuable time in your campaign and may even have to start from scratch. Second, we have heard from investors that it can be fairly clear when the entrepreneur is not talking to other potential investors, which will have a negative impact on the leverage that the fundraising CEO has when negotiations begin.  Third, the majority of financing rounds taking place in the life science arena today are made by a syndicate of multiple investors. Even if the investor you are communicating with agrees to invest, to close out the round you will likely need others to join, and the formation of a syndicate can be expedited if you have been in constant dialogue with a number of investors.

  1. Surface Thinking

When a person is in marketing mode, he is in dialogue with investors in order to facilitate a relationship that will result in a capital allocation.  Email canvassing, phone canvassing, WebEx presentations and road shows are all part of the dynamic. Sending an email to a bevy of targets in Asia or to Family Offices in North America without thinking about how to track the number of opens with an email report is counterproductive. To get more out of the email, you can use email campaign software to track this information.  By wiring the email with a few links that can be clicked upon to take the reader to your website, or to allow the reader to download a white paper, you can determine which investors are interested in your message and would be a good fit for your company.  Surface thinking is just sending the email without thinking deeply about how to get results out of the email campaign.  You need to get past the surface concept of an email; send it to a targeted list that can be monitored and reported on based on interest shown through opens and clicks. Targeted emails can help determine fit.

Phone canvasing isn’t just making a few phone calls and leaving some hasty message.  Like email, you need to get down past the surface of a phone call and keep your elevator pitch on the tip of your tongue.  You need to be precise and compelling.  You need to think of what you will do if no one picks up, and what to do if someone does pick up.  Being cavalier and frivolous in your investor canvassing creates white noise and doesn’t move you forward in your campaign.

  1. Informed Content

When you do your research and know an investor is a fit for your sector and stage it makes sense to start to think about how you can create some content that highlights your firm and your product or service. HubSpot has preached this concept for a long time.  Basically, informed content is about showing your value by getting content into your market space that is timely and compelling.  Informed content acts as a beacon for your company. It draws and guides people to you.  LSN’s newsletter, Next Phase, goes out to 15,000 global readers on a weekly basis. There are a lot of innovators and investors that read this newsletter.  We try and offer up helpful and insightful content that sheds light on the life science investor universe.  We highlight investor trends, we carve up our investor data and present up to date metrics on who is investing in what, and we do deep dives into the 10 categories of investors that we track.  Our goal is to do anything we can do to help our innovators and or investors connect more easily and understand each other better.  As a result, we get a lot of responses flooding in over the transom every week.  This action leads to business relationships.

These are just a few of the issues that we see life science entrepreneurs struggle with when trying to raise capital. With capital in limited supply, it is crucial that you avert these mistakes at every step of your fundraising campaign. By better understanding potential pitfalls and setting up your campaign strategy to avoid them, you can greatly increase your chances for a successful fundraise at a fair valuation.